Banner Life Insurance
Banner Life Insurance for Family and Income Protection
Review term and universal life coverage from Banner Life and compare it with options from more than 30 carriers.
Banner Life offers term insurance for temporary needs and universal life for permanent protection. Its term coverage may fit families seeking substantial protection for income replacement, mortgage obligations, education, or debt during a defined period.
Compare Banner Life Insurance Options
Why Consider Banner Life?
Term-focused family protection: Term coverage can address mortgages, dependent years, and income replacement.
Renewal and conversion features: Banner describes its term policies as renewable and convertible, subject to policy rules.
Permanent option: Universal life can provide lifetime coverage when premium and policy requirements are met.
Rider flexibility: Available riders can customize protection, depending on the product, state, and applicant.
Schedule a Free Coverage Review
Banner Term Life Insurance
Term life generally offers the greatest initial death benefit for the premium and can be useful when the financial need has a clear end date. Banner positions term insurance for budget-conscious protection and temporary needs such as a mortgage or working years.
Review the selected term length, conversion deadline, renewal premiums, and rider costs before purchasing.
Compare Banner Term Life Quotes
Banner Universal Life Insurance
Universal life is a permanent policy designed for longer-term protection. Banner describes its universal life offering as providing lifetime coverage when premiums are paid, with adjustable death benefits and potential conversion from term coverage.
Permanent insurance requires careful funding and policy review. Ask for a current illustration and evaluate both guaranteed and non-guaranteed values.
Who May Be a Good Fit?
Banner may be a strong candidate for healthy applicants seeking competitively positioned term protection, families covering a mortgage or income gap, and people who value a future conversion option. Actual eligibility and price depend on underwriting.
Compare Before You Apply
Convenience is valuable, but it is not the only consideration. Life Insured By Chris can compare Banner Life with other available carriers based on your age, health, state, coverage amount, budget, and preferred policy duration.
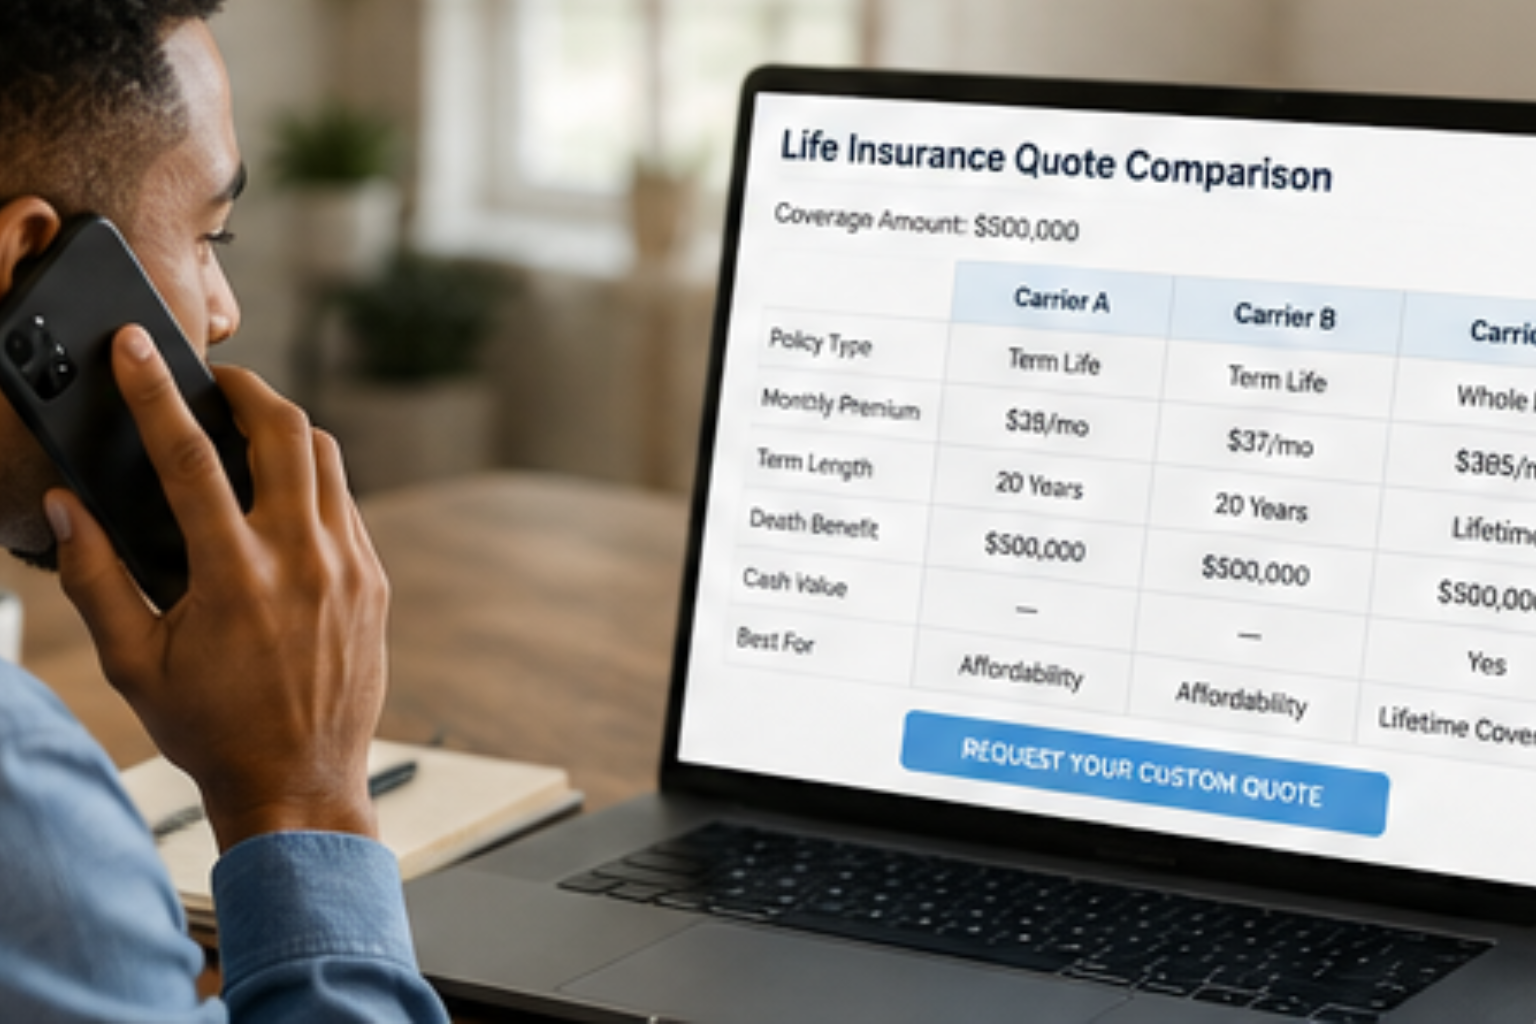
Why Work With Life Insured By Chris?
Banner Life may offer a good solution, but no single insurance company is the best fit for everyone.
Life Insured By Chris is an independent life insurance brokerage with access to more than 30 carriers. Instead of limiting you to one company, we can compare Banner Life with other available carriers based on:
Your age and health history
Tobacco use and prescriptions
Desired coverage amount
Preferred policy length
Underwriting requirements
Available riders and benefit limitations
Your monthly budget
You receive personalized guidance and a clear explanation of the policy before deciding whether to apply. There is no pressure to select Banner Life if another carrier offers a better combination of price, benefits, and approval potential.
Compare 30+ Life Insurance Carriers
Frequently Asked Questions
What kinds of life insurance does Banner offer?
Banner’s consumer site currently describes term life and universal life insurance.
Is Banner Life the same as Legal & General America?
Banner Life is part of the Legal & General America family. In New York, products may be issued by William Penn Life Insurance Company of New York.
Can I buy Banner coverage without comparing other companies?
You can, but underwriting and pricing vary significantly across insurers. An independent comparison may uncover a better match for your health and goals.
Protect the Years Your Family Depends on You
The right life insurance policy should fit more than your budget. It should match the length of time you need protection, the financial responsibilities you want to cover, and the underwriting option most appropriate for your health.
Schedule a complimentary coverage review to compare Banner Life with other available carriers and receive personalized guidance from an independent brokerage.
Schedule My Free 15-Minute Coverage Review
Life Insured By Chris is an independent life insurance brokerage and is not owned by, operated by, or exclusively affiliated with Banner Life. Product availability, issue ages, coverage amounts, riders, premiums, underwriting decisions, and policy provisions vary by state and applicant. Coverage is not guaranteed unless expressly stated in the applicable policy. Always review the policy contract for complete benefits, exclusions, limitations, and graded-benefit provisions.