Mortgage Protection
Life Insurance Made Simple. Protection Made Personal.
Mortgage Protection Life Insurance for the Home You Built
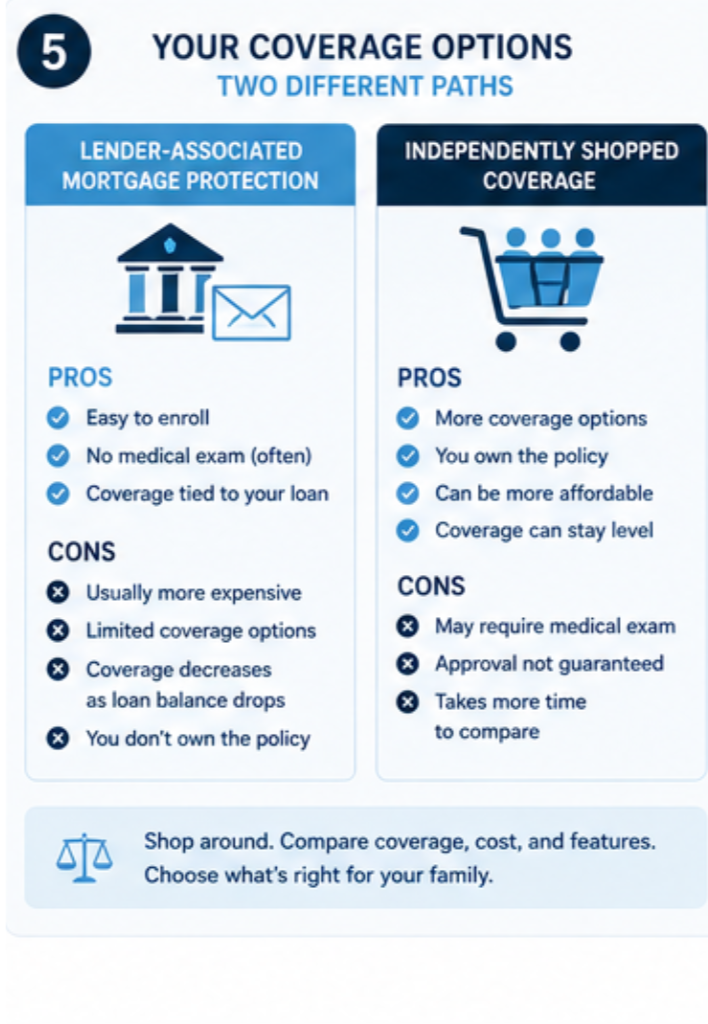
Mortgage protection life insurance is coverage intended to help loved ones manage a mortgage or other household expenses if the insured person dies while the policy is active. In many cases, it is an individually owned life insurance policy with a beneficiary selected by the policyowner, rather than coverage owned by the mortgage lender.
Life Insured By Chris compares mortgage-focused term and permanent life insurance options from multiple carriers. We help you consider the mortgage balance, household income, other debts, existing coverage, and the number of years your family may need support to determine your overall coverage amount.
Mortgage Protection Is Not the Same as PMI
Private mortgage insurance, commonly called PMI protects the lender if a borrower defaults. Mortgage protection life insurance is designed to provide a death benefit under the life insurance contract. These products serve different purposes.
What Could the Death Benefit Help Your Family Do?
- Pay off or reduce the remaining mortgage balance
- Continue monthly mortgage payments
- Cover property taxes, insurance, and maintenance
- Replace income while the household adjusts
- Pay other debts or urgent family expenses
When an individually owned life insurance benefit is paid to a beneficiary, the beneficiary determines how to use the proceeds, subject to assignments and policy terms. That flexibility can matter if keeping the home is not the family’s only priority.
Term Life Insurance for Mortgage Protection
Level term life insurance can align a fixed death benefit with a 10-, 20- or 30-year protection period. It may be useful when the mortgage and income-replacement need have a similar timeline. Compare the policy term with the remaining loan period, but do not ignore other household needs.
Learn how term coverage works before choosing a mortgage-focused policy.
How Much Mortgage Protection Should You Consider?
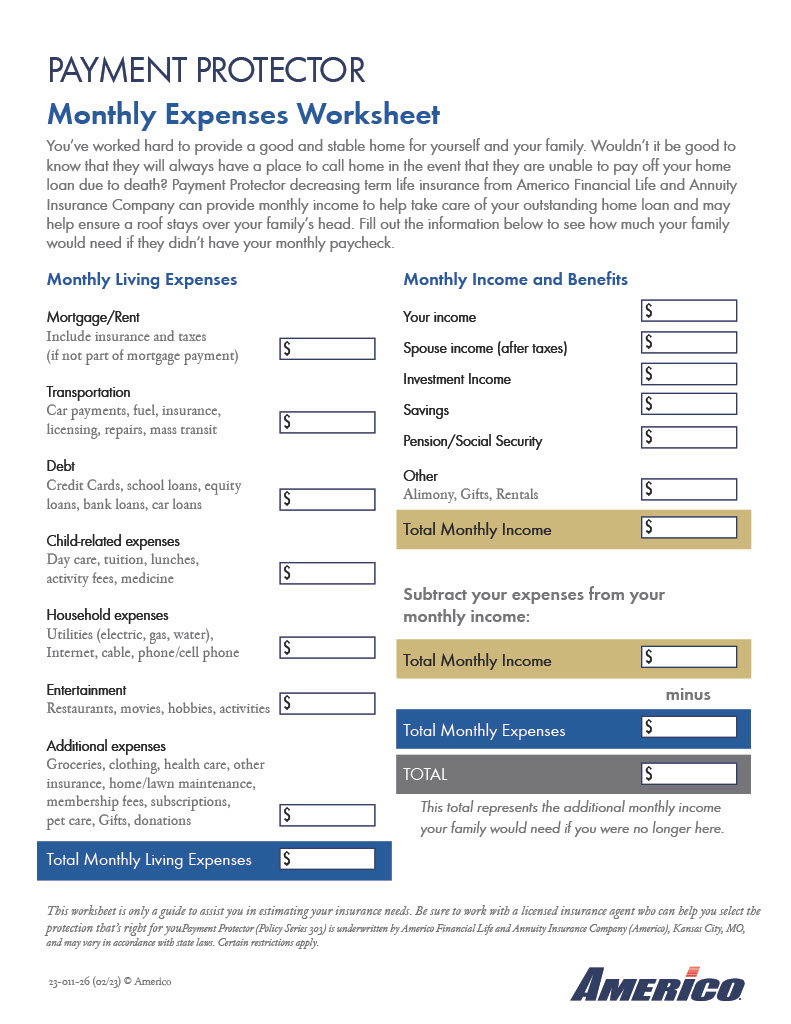
The current mortgage balance is a starting point, not always the ultimate answer. Consider whether survivors would pay off the loan, continue payments, move, replace lost income, or cover other debts. Subtract existing life insurance and liquid resources that are truly available for these goals.
Use a broader needs analysis to estimate the full protection gap.
Optional Riders and Policy Features
Depending on the policy and carrier, optional benefits may address disability, chronic or critical illness, accidental death, premium waiver, or conversion. Riders can add costs and have definitions, exclusions, and eligibility rules. Review the contract rather than relying on the rider's name alone.
Compare mortgage protection options from multiple carriers.
Or call or text (202) 641-5953
Monday–Friday, 8:00 AM–5:00 PM Eastern Time
Saturday appointments available by request
Life Insured By Chris is an independent insurance brokerage and is not owned by, operated by, or exclusively affiliated with any insurance company. Product availability, premiums, issue ages, benefit amounts, underwriting decisions, waiting periods, and policy provisions vary by carrier, state, and applicant. No coverage or rate is guaranteed until an insurance company approves the application, all delivery requirements are satisfied, and the required premium is received. Consult the policy contract for complete benefits, exclusions, limitations, and contestability provisions.
| Book My Free Coverage Review: In 15 minutes, we'll compare your options across 30+ carriers and tell you exactly what you qualify for and what it costs? → Visit: www.lifeinsuredbychris.com/schedule-a-consultation |
Frequently Asked Questions
Does mortgage protection pay the lender or my beneficiary?
It depends on the policy structure and any assignments. Many individually owned policies pay the named beneficiary. Some creditor or lender-linked coverage may work differently.
Should coverage equal the mortgage balance?
Not necessarily. A complete needs review can include income replacement, other debts, childcare, education, and existing coverage besides the mortgage.
Can I keep the policy if I refinance or move?
An individually owned life insurance policy is separate from a specific mortgage, but policy terms and assignments matter. Confirm the structure before applying.


