Mortgage Protection Life Insurance
Life Insurance Made Simple. Protection Made Personal.
Mortgage Protection Life Insurance for the Home You Built
Mortgage protection life insurance is coverage intended to help loved ones manage a mortgage or other household expenses if the insured person dies while the policy is active. In many cases, it is an individually owned life insurance policy with a beneficiary selected by the policyowner, rather than coverage owned by the mortgage lender.
Life Insured By Chris compares mortgage-focused term and permanent life insurance options from multiple carriers. We help you consider the mortgage balance, household income, other debts, existing coverage, and the number of years your family may need support to determine your overall coverage amount.
Who Mortgage Protection Is Best For
Mortgage protection life insurance is a smart fit for homeowners who want to make sure their family can stay in the home. It's often the right choice for:
- New homeowners and first-time buyers taking on a 15- or 30-year mortgage.
- Single-income households where one paycheck covers the mortgage.
- Dual-income couples who couldn't afford the payment on one income.
- Single parents who want their children to keep their home.
- Homeowners who refinanced or took out a home equity loan and increased their balance.
If your needs go beyond the house, such as income replacement, childcare, or education, a larger term life policy can cover the mortgage and everything else together.
How Much Does Mortgage Protection Insurance Cost?
Most mortgage protection is level term life insurance matched to your loan length. That makes it one of the most affordable ways to protect your home. Here are average monthly rates for a 40-year-old nonsmoker with $500,000 of coverage:
| Term Length | Women | Men |
| 20-year | $47 | $59 |
| 30-year | $82 | $104 |
Rates are lower at younger ages and for smaller balances. A 25-year-old pays an average of $30 to $32 a month for a 20-year, $500,000 policy.
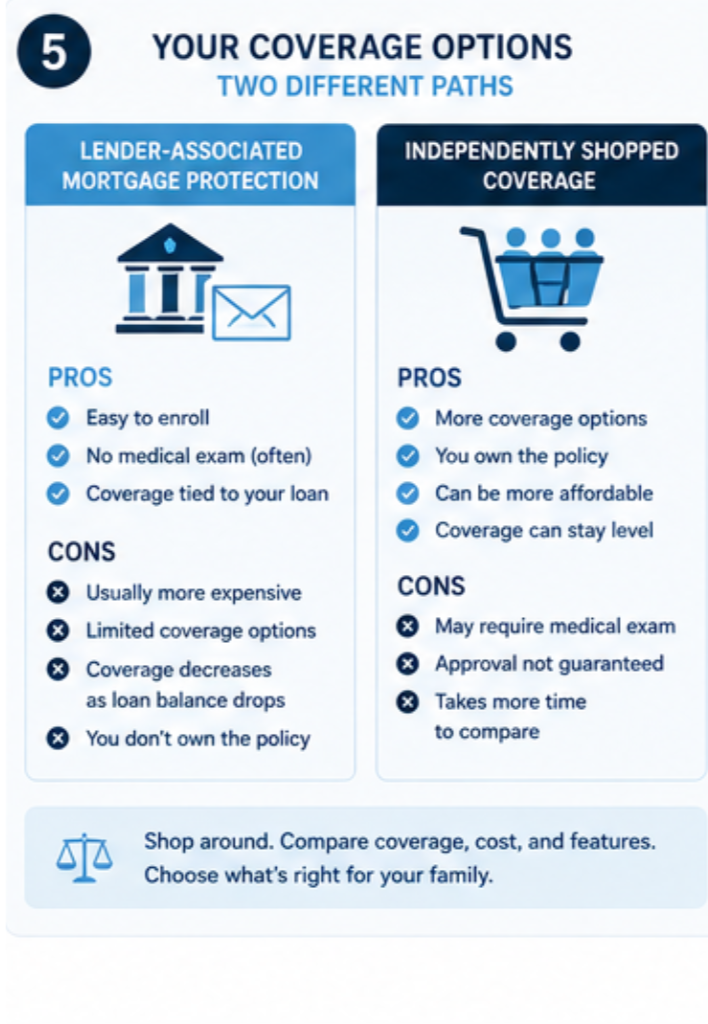
Mortgage Protection vs. Lender Mortgage Life Insurance
| Feature | Mortgage Protection (individual policy) | Lender Mortgage Life Insurance |
| Who gets paid | Your chosen beneficiary | The lender |
| Death benefit | Stays level for the whole term | Usually shrinks as the loan is paid |
| If you refinance or move | Policy stays with you | Coverage often ends |
| Underwriting | Priced on your health; healthy applicants often pay less | Often one rate for everyone |
Source: MoneyGeek 2026 term life national averages. Averages are not quotes. Lender product features vary, so review your lender's terms.CTA:Protect My Home
Mortgage Protection Is Not the Same as PMI
Private mortgage insurance, commonly called PMI, protects the lender if a borrower defaults. Mortgage protection life insurance is designed to provide a death benefit under the life insurance contract. These products serve different purposes.
What Could the Death Benefit Help Your Family Do?
- Pay off or reduce the remaining mortgage balance
- Continue monthly mortgage payments
- Cover property taxes, insurance, and maintenance
- Replace income while the household adjusts
- Pay other debts or urgent family expenses
When an individually owned life insurance benefit is paid to a beneficiary, the beneficiary determines how to use the proceeds, subject to assignments and policy terms. That flexibility can matter if keeping the home is not the family’s only priority.
Term Life Insurance for Mortgage Protection
Level term life insurance can align a fixed death benefit with a 10-, 20- or 30-year protection period. It may be useful when the mortgage and income-replacement need have a similar timeline. Compare the policy term with the remaining loan period, but do not ignore other household needs.
Learn how term coverage works before choosing a mortgage-focused policy.
How Much Mortgage Protection Should You Consider?
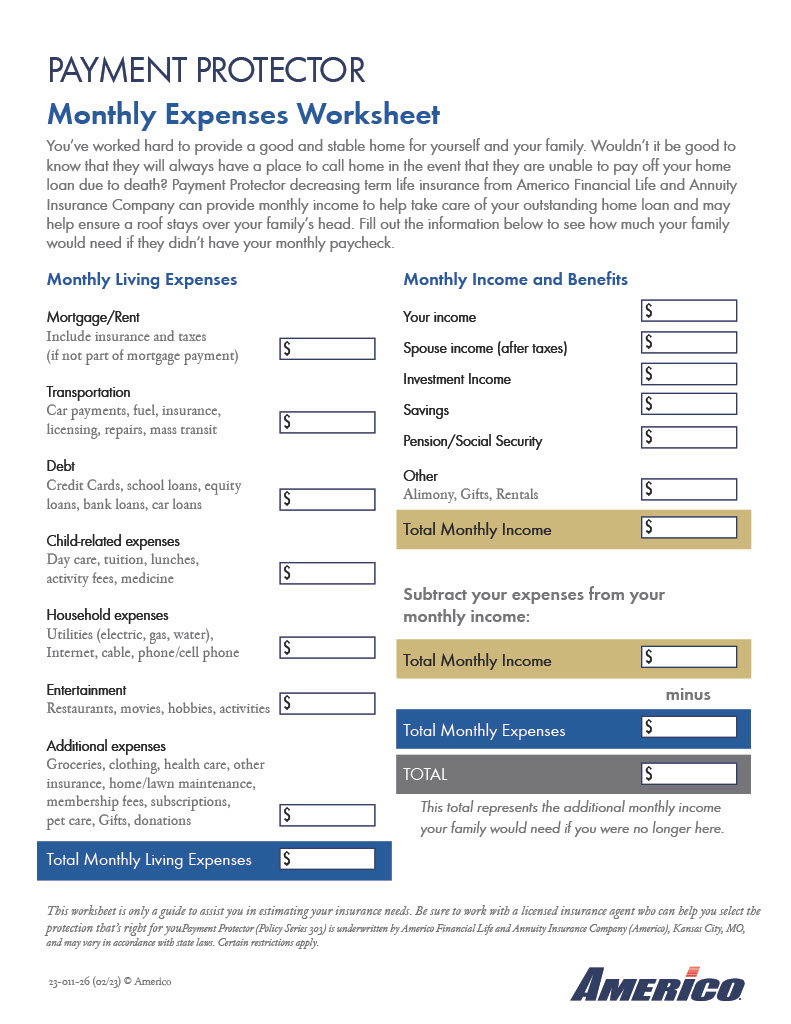
The current mortgage balance is a starting point, not always the ultimate answer. Consider whether survivors would pay off the loan, continue payments, move, replace lost income, or cover other debts. Subtract existing life insurance and liquid resources that are truly available for these goals.
Use a broader needs analysis to estimate the full protection gap.
Optional Riders and Policy Features
Depending on the policy and carrier, optional benefits may address disability, chronic or critical illness, accidental death, premium waiver, or conversion. Riders can add costs and have definitions, exclusions, and eligibility rules. Review the contract rather than relying on the rider's name alone.
Compare mortgage protection options from multiple carriers.
Or call or text (202) 641-5953
Monday–Friday, 8:00 AM–5:00 PM Eastern Time
Saturday appointments available by request
Life Insured By Chris is an independent insurance brokerage and is not owned by, operated by, or exclusively affiliated with any insurance company. Product availability, premiums, issue ages, benefit amounts, underwriting decisions, waiting periods, and policy provisions vary by carrier, state, and applicant. No coverage or rate is guaranteed until an insurance company approves the application, all delivery requirements are satisfied, and the required premium is received. Consult the policy contract for complete benefits, exclusions, limitations, and contestability provisions.
| Book My Free Coverage Review: In 15 minutes, we'll compare your options across 30+ carriers and tell you exactly what you qualify for and what it costs. → Visit: www.lifeinsuredbychris.com/schedule-a-consultation |
Mortgage Protection Carriers We Compare
- Americo: term built for mortgage protection, with return-of-premium (CBO) options
- SBLI: level term with a dedicated mortgage protection program
- Protective: terms up to 40 years to match long mortgages
- Banner Life: competitive term for healthy homeowners
- Ethos and Fidelity Life: fast, no-exam options for new homeowners
Frequently Asked Questions
Does mortgage protection pay the lender or my beneficiary?
It depends on the policy structure and any assignments. Many individually owned policies pay the named beneficiary. Some creditors or lender-linked coverage may work differently.
Should coverage equal the mortgage balance?
Not necessarily. A complete needs review can include income replacement, other debts, childcare, education, and existing coverage besides the mortgage.
Can I keep the policy if I refinance or move?
An individually owned life insurance policy is separate from a specific mortgage, but policy terms and assignments matter. Confirm the structure before applying.
Is mortgage protection insurance required?
No. Lenders may require PMI or homeowners' insurance, but mortgage protection life insurance is optional coverage you choose for your family.
Can I get mortgage protection without a medical exam?
Often, yes. Many carriers offer no medical exam term policies for mortgage protection, especially for healthy applicants.
What's the difference between mortgage protection and homeowners insurance?
Homeowners insurance covers damage to the house. Mortgage protection life insurance pays your family if you die, so they can keep the house.
Do mortgage protection policies include living benefits?
Many do. Riders may pay part of the benefit early for a critical, chronic, or terminal illness, or waive premiums if you become disabled. Riders vary by carrier and may cost extra.