Indexed Universal Life Insurance
Life Insurance Made Simple. Protection Made Personal.
Permanent Protection with Flexible Premiums and Index-Linked Cash Value
Indexed universal life insurance (IUL) is permanent life insurance that pairs a death benefit with cash value that can earn interest based on the performance of a market index, such as the S&P 500. Your cash value is not invested directly in the market. Instead, the carrier credits interest using a formula that includes a floor, which protects against index losses, and a cap or participation rate, which limits upside.
Life Insured By Chris helps you compare IUL policies from multiple top-rated carriers. We explain caps, floors, fees, illustrations, and the tradeoffs between IUL, whole life, and term life insurance in plain language.
Who IUL Is Best For
- Higher-income earners who have maxed out their 401(k) and IRA and want another tax-advantaged option.
- Business owners planning key-person coverage, buy-sell funding, or executive bonus plans.
- Parents in their 30s and 40s who want lifelong protection plus cash value they can access later.
- Families planning a legacy who want flexibility in how much they pay each year.
- People with a long time horizon, 15 years or more, who can fund the policy consistently.
IUL is not right for everyone. If your main goal is the most coverage for the lowest cost, term life insurance is usually a better fit. If you want fixed premiums and guaranteed cash value, compare whole life insurance. Not sure how much coverage you need? Start with our life insurance calculator.
How Much Does IUL Cost?
IUL has no single price. Your premium depends on how the policy is designed. A minimum-funded policy buys the death benefit at the lowest cost. A maximum-funded policy puts in as much as tax rules allow, to build cash value.As a benchmark, universal life insurance for nonsmokers averages:
| Age at Purchase | Monthly Premium ($500,000) |
| 25 | $182 to $210 |
| 40 | About $336 (average) |
| 60 | $765 to $930 |
That's roughly half the cost of whole life at the same age, but with fewer guarantees. Funding above the minimum raises the premium and increases cash value potential.
Source: MoneyGeek 2026 universal life averages. IUL pricing varies by carrier, index strategy, and funding level. Averages are not quotes or illustrations.
How Indexed Universal Life Insurance Works
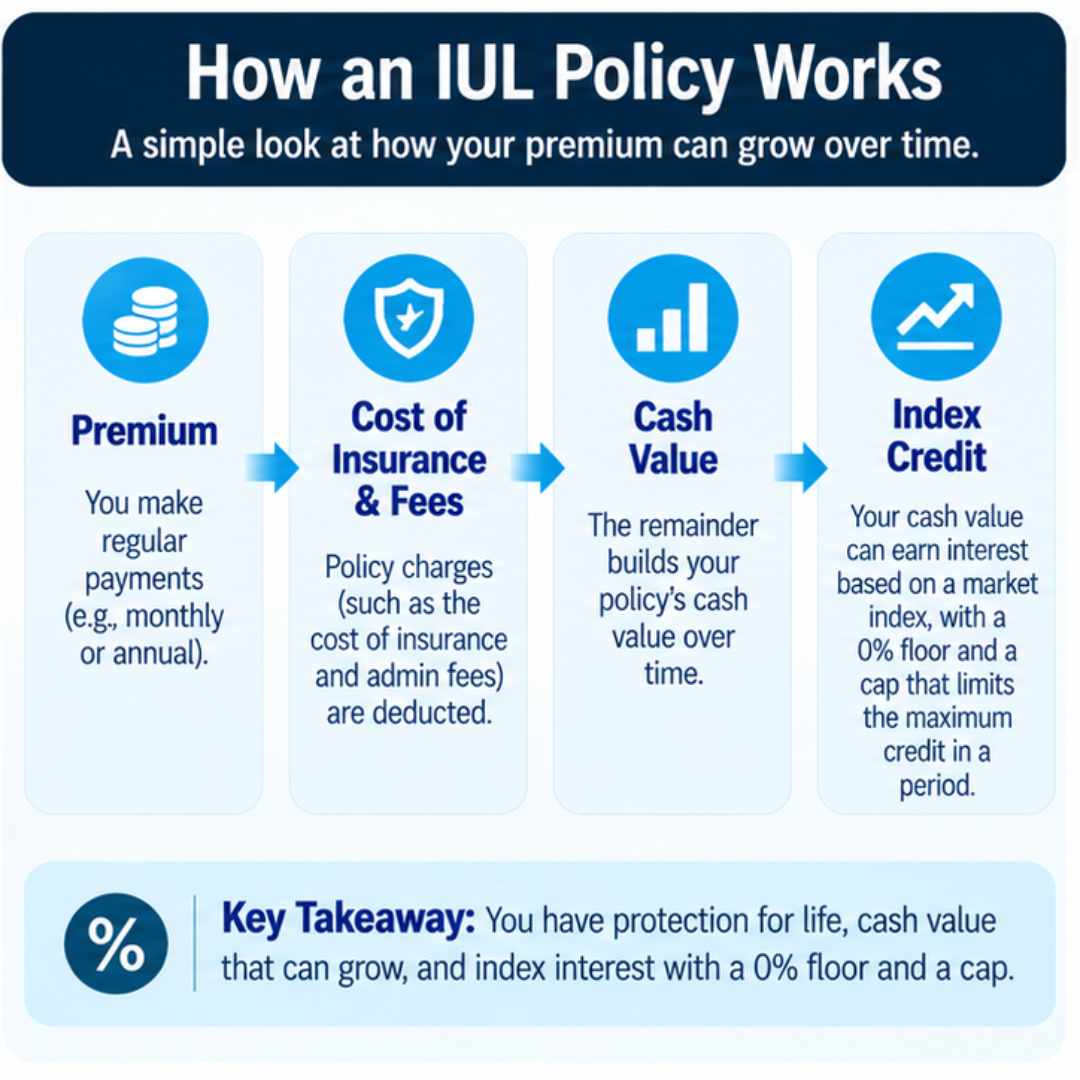
Each premium payment goes into the policy. The carrier deducts the cost of insurance and policy fees, and the remainder builds cash value. At the end of each crediting period, usually one year, the carrier credits interest based on how the chosen index performed, subject to the policy's floor, cap, and participation rate.
- Flexible premiums: within limits, you can pay more, pay less, or skip payments, as long as the cash value covers policy charges.
- Adjustable death benefit: the coverage amount may be increased (with underwriting) or decreased as needs change.
- Downside protection: a floor, typically 0%, means a down year in the index won't reduce credited interest below the floor. Policy charges are still deducted.
- Limited upside: caps and participation rates limit how much of the index gain is credited. The carrier sets these, and they can change over time.
- Optional riders: living benefit, chronic illness, or long-term care riders may be available at additional cost or subject to eligibility.
Key IUL Terms to Understand
- Cap rate: the maximum interest credited in a period, even if the index gains more.
- Floor: the minimum interest credited, usually 0%, even if the index loses value.
- Participation rate: the share of the index gain used to calculate your credit.
- Cost of insurance: the monthly charge for the death benefit. It generally increases with age.
- Illustration: a carrier projection of how the policy may perform. Illustrations are not guarantees.
IUL vs. Whole Life vs. Term Life
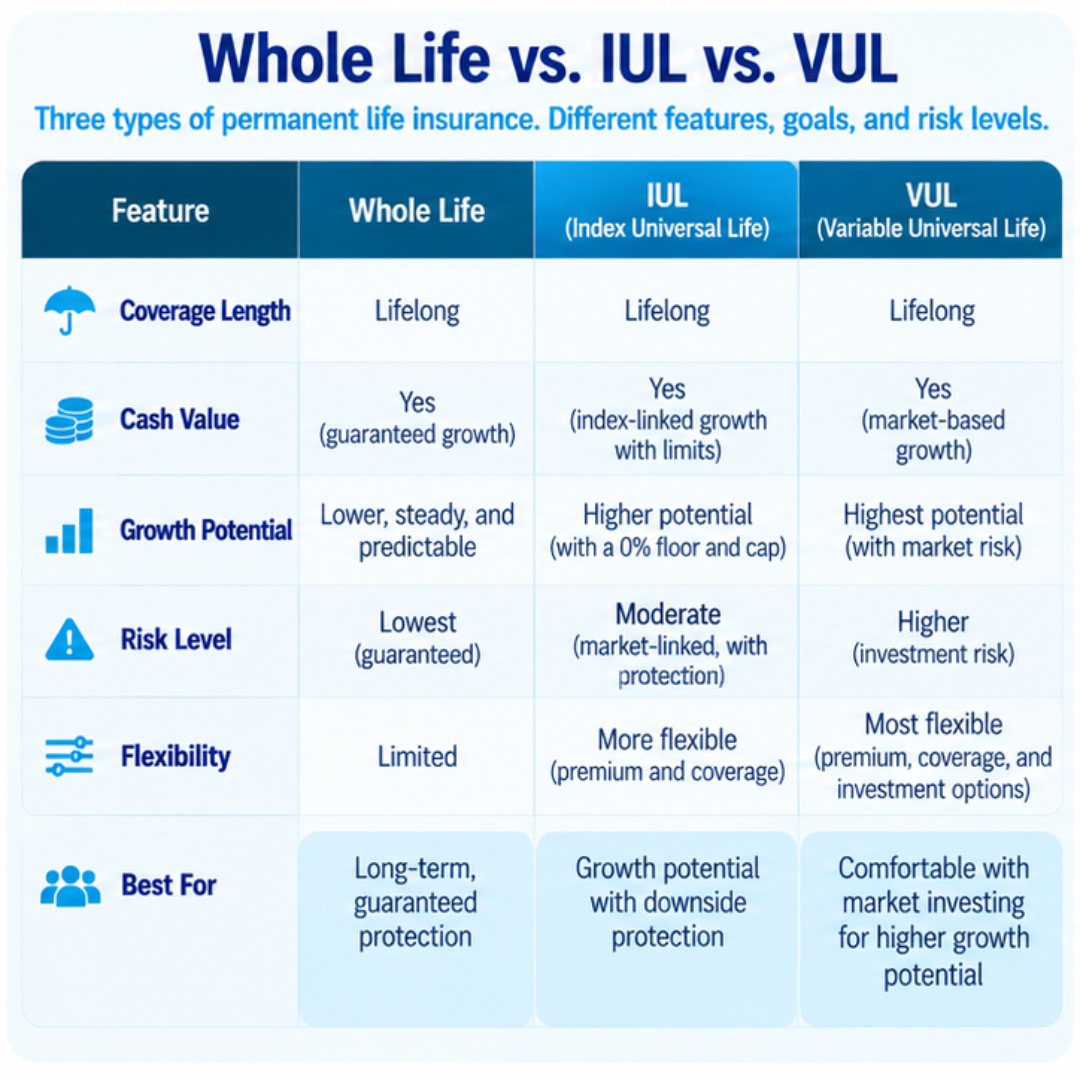
| Feature | Term Life | Whole Life | Indexed Universal Life |
| Length of coverage | 10, 20, or 30 years | Lifetime, if premiums are paid | Lifetime, if the policy is funded adequately |
| Premiums | Level for the term | Fixed and scheduled | Flexible within limits |
| Cash value | None | Guaranteed growth schedule | Index-linked interest with a floor and cap |
| Cost | Lowest | Highest | Varies with funding design |
| Best for | Income replacement during working years | Predictability and guarantees | Flexibility and growth potential |
Compare Term, Whole, and IUL Options
IUL Cash Value and Retirement Planning
Many people use IUL cash value to supplement retirement income through policy loans or withdrawals. When a policy is properly structured and stays in force, loans are generally not taxable income. However, loans accrue interest and reduce the cash value and death benefit. If the policy lapses with a loan outstanding, the gain may become taxable.
Funding a policy above IRS limits can turn it into a modified endowment contract (MEC), which changes how loans and withdrawals are taxed. Consult a tax professional about your situation. Looking for index-linked growth without a death benefit focus? Compare fixed index annuity options.
Risks to Understand Before You Buy
- Caps and participation rates can be lowered by the carrier, which reduces future growth.
- Rising cost of insurance can erode cash value, especially at older ages or if the policy is underfunded.
- Underfunding or heavy loans can cause the policy to lapse, sometimes when coverage is needed most.
- Surrender charges typically apply during the early years.
- Illustrations depend on assumptions. Ask to see results at lower crediting rates, not just the illustrated maximum.
This is why carrier selection and policy design matter. As an independent brokerage, we compare IUL designs from carriers such as North American Company and Protective to find a structure that fits your goals and budget.
What Affects IUL Cost?
Pricing can depend on age, health, tobacco or nicotine use, sex where permitted, state, death benefit amount, premium funding level, index strategy, and riders. Most IUL policies require full underwriting, and some carriers offer accelerated underwriting without an exam for qualifying applicants.
Get help comparing IUL caps, costs, and illustrations across carriers.
Or call or text (202) 641-5953
Monday–Friday, 8:00 AM–5:00 PM Eastern Time
Saturday appointments available by request
Life Insured By Chris is an independent insurance brokerage and is not owned by, operated by, or exclusively affiliated with any insurance company. Indexed universal life insurance is not an investment in the stock market or any index. Index-linked interest is subject to caps, participation rates, and other limits set by the carrier, which may change. Policy loans and withdrawals reduce cash value and the death benefit and may cause the policy to lapse or create tax consequences. Illustrations are hypothetical and not guaranteed. Product availability, premiums, issue ages, underwriting decisions, and policy provisions vary by carrier, state, and applicant. No coverage or rate is guaranteed until an insurance company approves the application, all delivery requirements are satisfied, and the required premium is received. Consult a tax advisor regarding your situation.
| Book My Free Coverage Review: In 15 minutes, we'll compare your options across 30+ carriers and tell you exactly what you qualify for and what it costs. → Visit: www.lifeinsuredbychris.com/schedule-a-consultation |
IUL Carriers We Compare
- National Life Group: IUL with living benefits, including RapidProtect no-exam IUL
- North American Company: IUL focused on long-term planning and retirement strategies
- Protective: IUL with optional chronic illness features
- Transamerica: Financial Foundation IUL and Financial Choice IUL
Frequently Asked Questions
Can I lose money in an IUL?
Index losses won't reduce credited interest below the floor, but policy charges are deducted every month. In years with low or zero credits, cash value can decline.
Is IUL better than whole life insurance?
Neither is better for everyone. Whole life offers guarantees and fixed premiums. IUL offers flexibility and growth potential, but with fewer guarantees.
Is IUL a good retirement plan?
IUL can supplement retirement income for some people, but it is life insurance first. It typically works best after you've used other retirement accounts and when the policy is funded consistently for many years.
How much does IUL cost?
Cost depends on your age, health, coverage amount, and how you fund the policy. A broker can compare illustrations from multiple carriers side by side.
Can I access my IUL cash value?
Yes. You can take withdrawals or policy loans from available cash value. Both reduce the death benefit and cash value and can affect whether the policy stays in force.
Do I need a medical exam for IUL?
Many IUL policies require full underwriting, but some carriers offer accelerated underwriting with no exam for qualifying healthy applicants.
Can IUL premiums or costs go up?
Your premium is flexible, but internal costs can rise. Cost of insurance generally increases with age, and carriers can lower caps. Underfunded policies may need higher payments later to stay in force.
IUL vs. 401(k): which is better?
They serve different purposes. A 401(k) is a retirement account, often with an employer match. IUL is life insurance with cash value. Most people should capture their employer match first.
Why use a broker for IUL?
Caps, fees, and illustration assumptions vary widely between carriers. An independent broker can compare illustrations side by side before you commit.