Whole Life Insurance
Life Insurance Made Simple. Protection Made Personal.
Whole Life Insurance for Lifetime Protection
Whole life insurance is permanent life insurance designed to remain in force for the insured person’s lifetime when required premiums are paid and the policy remains in good standing. It combines a death benefit with guaranteed cash-value growth based on the policy contract.
Life Insured By Chris helps consumers compare whole life insurance options from multiple carriers. We explain premiums, guarantees, cash value, riders, surrender provisions, and the tradeoffs between permanent and temporary coverage in plain language.
How Whole Life Insurance Works
A whole life policy typically offers level premiums, a guaranteed death benefit, and a contractual cash-value schedule. The policyowner may be able to access available cash value through withdrawals or loans. Loans and withdrawals can reduce cash value and the death benefit, may cause the policy to lapse, and can create tax consequences. Policy-specific terms control.
- Coverage designed to last for life when policy requirements are met
- Premiums that are scheduled to remain level
- A death benefit for named beneficiaries
- Cash value that grows according to policy guarantees
- Optional riders that may be available at additional cost or subject to eligibility
When Whole Life Insurance May Be Worth Considering
Whole life insurance may fit people who want permanent protection, predictable premiums, a final-expense or legacy benefit, or a policy with contractual cash value. It can also be considered when a need is expected to continue beyond a 10-, 20- or 30-year term.
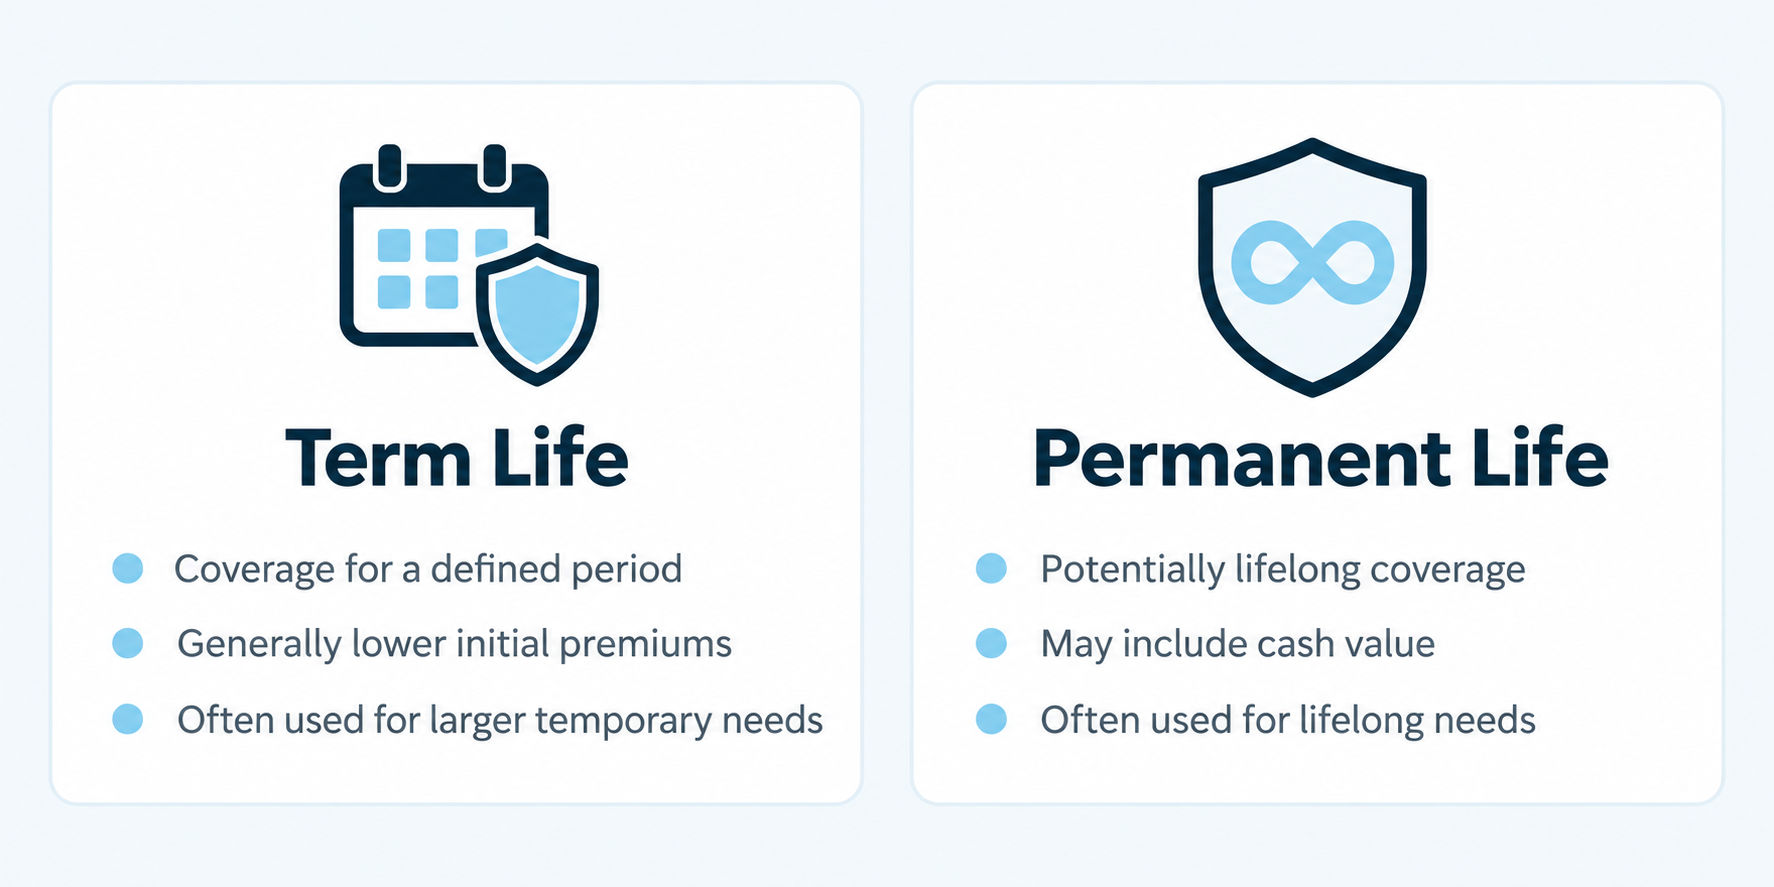
It is not automatically the right choice for every household. Whole life premiums are higher than term life premiums for the same initial death benefit. The appropriate balance depends on the protection needs, budget, and time horizon.
Compare permanent protection with temporary coverage before deciding.
Compare Term and Whole Life Insurance
Whole Life Insurance and Cash Value
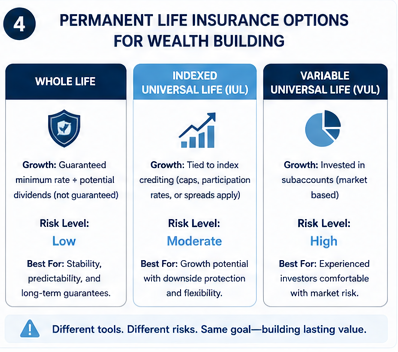
Cash value is part of the policy, not a separate savings account. Growth, access, loan interest, and surrender charges depend on the contract. Participating policies may be eligible for dividends, but dividends are not guaranteed. Ask for a carrier illustration showing both guaranteed and non-guaranteed values, then review how the policy performs under more conservative assumptions.
What Affects Whole Life Insurance Cost?
Pricing can depend on age, health, tobacco or nicotine use, sex where permitted, state, coverage amount, payment design, and riders. Some products use simplified underwriting and may not require an exam, while others require more extensive review.
Get help comparing whole life benefits, costs, and underwriting requirements.
Or call or text (202) 641-5953
Monday–Friday, 8:00 AM–5:00 PM Eastern Time
Saturday appointments available by request
Life Insured By Chris is an independent insurance brokerage and is not owned by, operated by, or exclusively affiliated with any insurance company. Product availability, premiums, issue ages, benefit amounts, underwriting decisions, waiting periods, and policy provisions vary by carrier, state, and applicant. No coverage or rate is guaranteed until an insurance company approves the application, all delivery requirements are satisfied, and the required premium is received. Consult the policy contract for complete benefits, exclusions, limitations, and contestability provisions.
| Book My Free Coverage Review: In 15 minutes, we'll compare your options across 30+ carriers and tell you exactly what you qualify for and what it costs? → Visit: www.lifeinsuredbychris.com/schedule-a-consultation |
Frequently Asked Questions
Does whole life insurance expire?
Whole life insurance is intended to provide lifetime coverage, provided required premiums are paid, and the policy stays in force under its contract.
Are whole life premiums fixed?
Many traditional whole life policies have scheduled level premiums. Review the policy illustration and contract because payment periods and designs vary.
Can I borrow from a whole life policy?
Policyowners may borrow against available cash value. Loans accrue interest and can reduce the death benefit and cash value or contribute to a lapse if not managed carefully.


