Term Life Insurance
Life Insurance Made Simple. Protection Made Personal.
Term Life Insurance That Protection What Matters Most
Term life insurance provides coverage for a selected period, commonly 10, 20, or 30 years. If the insured person dies while an eligible policy is active, the carrier pays the policy death benefit to the named beneficiary according to the contract. Because term insurance is designed primarily for protection rather than cash-value accumulation, it can provide a larger initial death benefit than many permanent policies for the same starting budget.
Life Insured By Chris compares term life insurance options from more than 30 top-rated carriers. Instead of limiting your search to one company, we review your goals, budget, age, health history, and preferred coverage period before helping you evaluate available options.
Not sure how much protection to consider?
Call or Text Life Insured By Chris: (202) 641-5953
Free 15-minute coverage review • No obligation to purchase • Licensed in 20 states
What Can Term Life Insurance Help Protect?
Term coverage is often considered when a financial responsibility has a foreseeable timeline compared to whole life insurance. The policy can help provide funds your beneficiaries may use for obligations such as:
- Replacing income while children or other dependents still rely on you
- Paying a mortgage or other outstanding debts
- Supporting childcare and education expenses
- Helping a spouse maintain household stability
- Protecting a business loan or other time-limited obligation
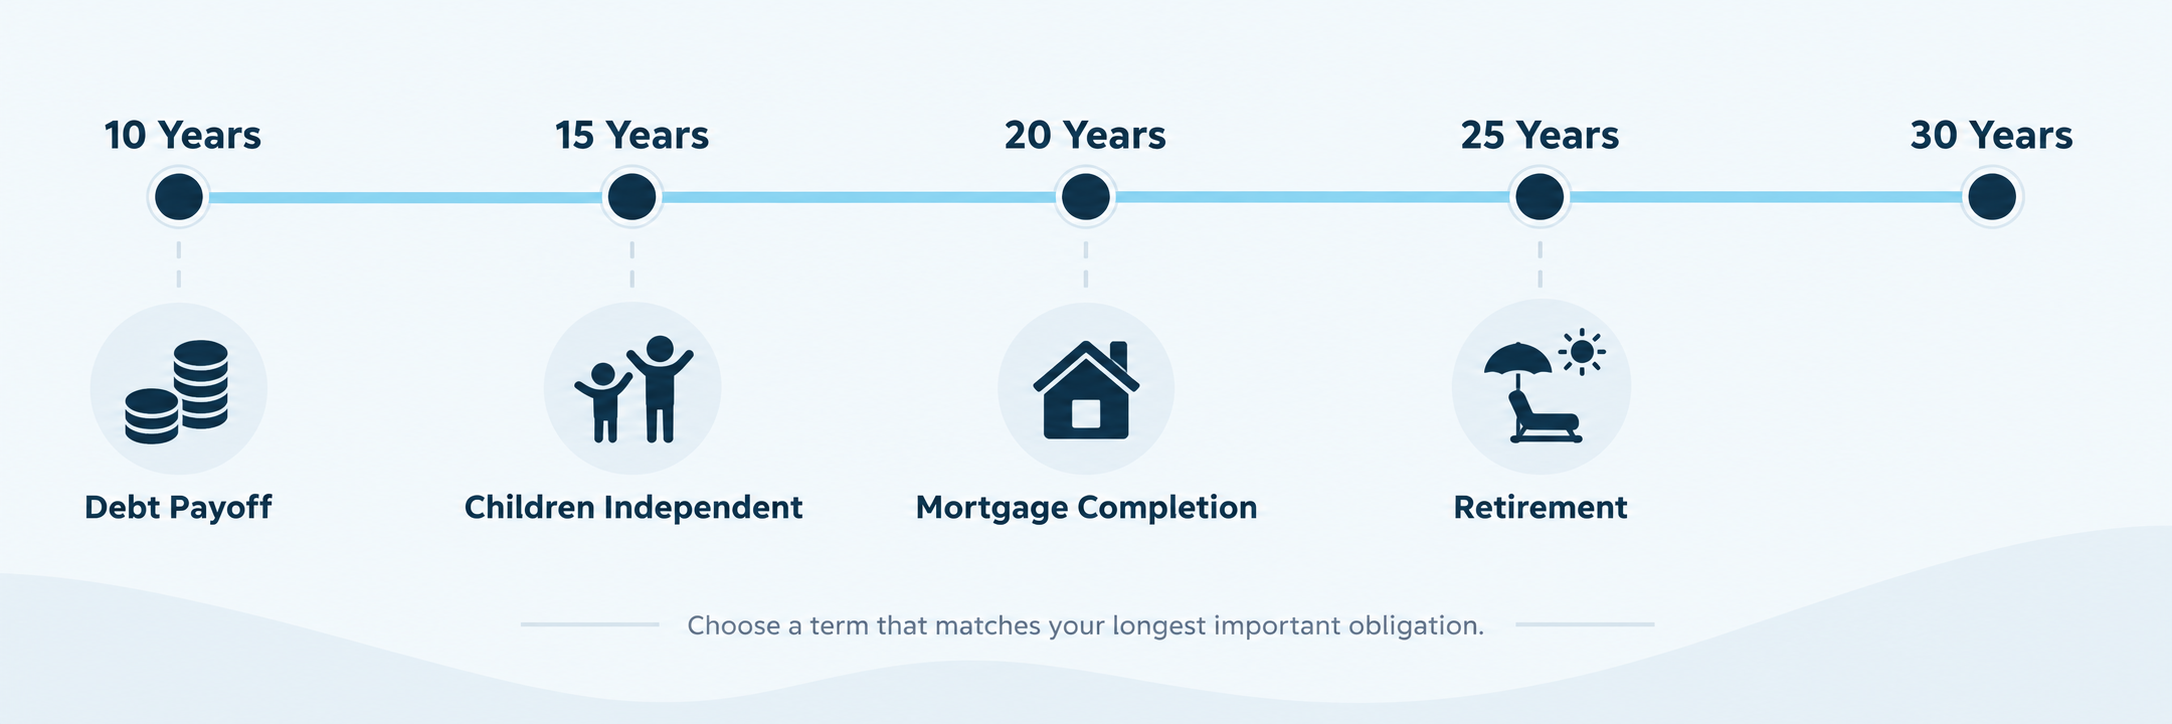
Choosing a 10-, 20-, or 30-Year Term
10-year term life insurance
A shorter term may fit someone approaching retirement, covering a remaining loan, or filling a temporary protection gap. Although a shorter term can cost less than a longer term with otherwise similar policy details, your age and health at any future reapplication can affect availability and price.
20-year term life insurance
A 20-year term may align with income-replacement needs, a mortgage timeline, or the years before children become financially independent.
30-year term life insurance
A 30-year term may be appropriate for younger families, new homeowners, or people who expect dependents to need support for several decades. Longer terms carry higher premiums than shorter terms for the same applicant and coverage amount.
How Term Life Insurance Pricing Works
Carriers commonly consider age, health history, medications, tobacco or nicotine use, occupation, driving history, coverage amount, and term length. Some applicants may qualify for accelerated or no-exam underwriting, while others may need medical records, a telephone interview, laboratory work, or a paramedical exam.
An advertised rate is not an ultimate offer. Your actual premium and eligibility are determined by the carrier after underwriting.
Compare term options with personal guidance and no obligation to purchase.
Or call or text (202) 641-5953
Monday–Friday, 8:00 AM–5:00 PM Eastern Time
Saturday appointments available by request
Life Insured By Chris is an independent insurance brokerage and is not owned by, operated by, or exclusively affiliated with any insurance company. Product availability, premiums, issue ages, benefit amounts, underwriting decisions, waiting periods, and policy provisions vary by carrier, state, and applicant. No coverage or rate is guaranteed until an insurance company approves the application, all delivery requirements are satisfied, and the required premium is received. Consult the policy contract for complete benefits, exclusions, limitations, and contestability provisions.
| Book My Free Coverage Review: In 15 minutes, we'll compare your options across 30+ carriers and tell you exactly what you qualify for and what it costs? → Visit: www.lifeinsuredbychris.com/schedule-a-consultation |
Frequently Asked Questions
Does term life insurance build cash value?
Traditional term life insurance rarely builds cash value. It is designed to provide a death benefit during the stated term. Some products may offer additional features or conversion rights, which vary by policy.
Can I buy term life insurance without a medical exam?
Possibly. Some carriers offer accelerated or simplified underwriting, but they may still review health questions, prescriptions, and consumer databases. Eligibility depends on the applicant and carrier.
What happens when the term ends?
Depending on the contract, coverage may end, renew at a higher rate, or offer a conversion option. Review renewal and conversion provisions before purchasing. Compare our life insurance carriers today.


