No Medical Exam Life Insurance
Life Insurance Made Simple. Protection Made Personal.
No Medical Exam Life Insurance Without the Guesswork
No-medical-exam life insurance allows eligible applicants to apply without a traditional paramedical exam. Depending on the product, a carrier may still ask health questions and review prescription history, motor-vehicle records, consumer reports, or other data. “No exam” does not automatically mean no underwriting, instant approval, or guaranteed acceptance.
Life Insured By Chris compares options across multiple carriers and helps you understand which underwriting path may fit your age, health history, timing, and desired coverage amount.
Three Common No-Exam Underwriting Paths
Accelerated underwriting
Accelerated underwriting uses application information and available data to determine whether an exam may be waived. Some applicants receive a faster decision; others may be referred for additional underwriting.
Simplified-issue life insurance
Simplified-issue coverage uses a shorter health questionnaire and does not require a traditional exam. Coverage amounts and pricing may differ from fully underwritten policies.
Guaranteed-issue life insurance
Guaranteed-issue coverage rarely asks health questions, but it often has restricted ages, smaller face amounts, and a graded period for natural death. It should not be confused with every no-exam product.
Who May Consider No-Exam Coverage?
- Applicants who value a more convenient application process
- People seeking coverage on a shorter timeline
- Applicants who prefer not to complete blood or urine testing
- Consumers with certain health histories who need carrier-specific options
- Older adults considering final expense or smaller permanent coverage
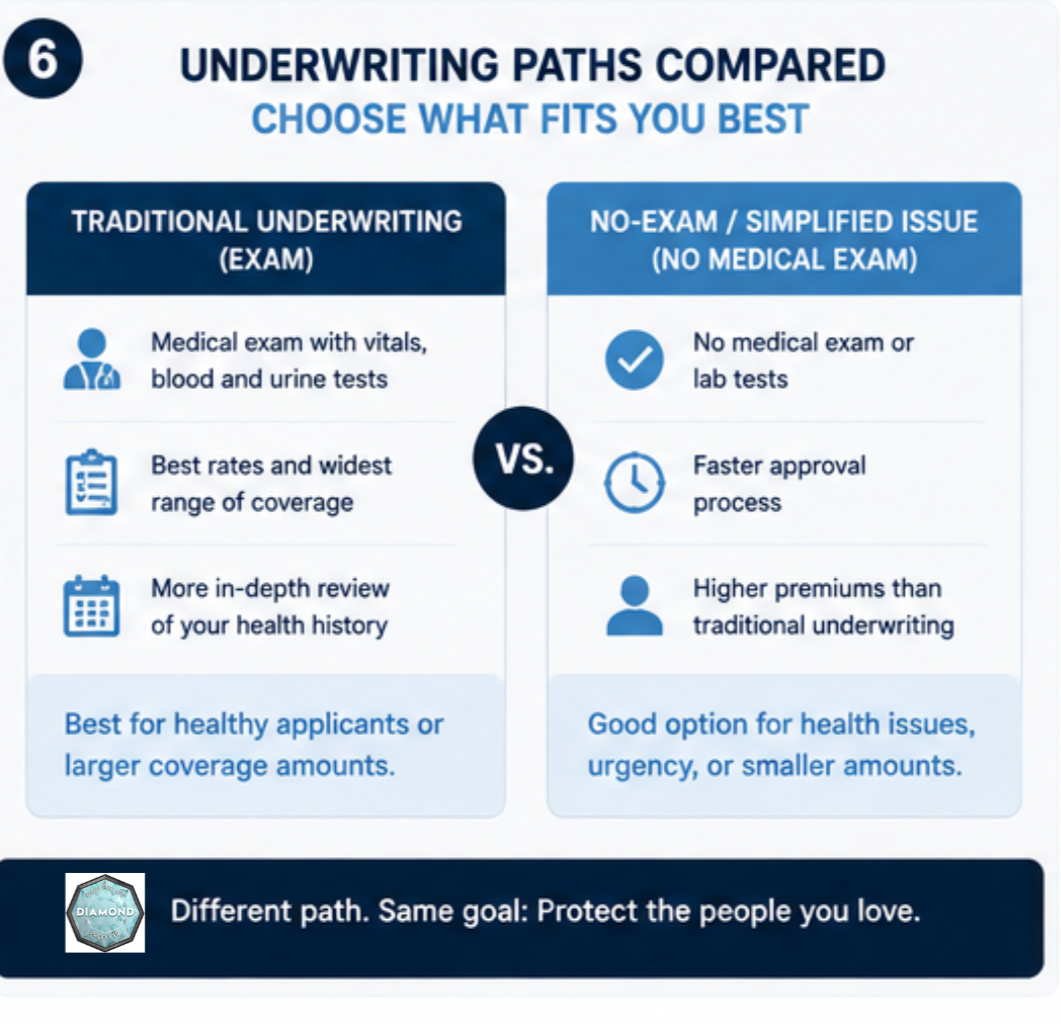
No-exam coverage is not always the lowest-cost option. A healthy applicant may receive better pricing through traditional underwriting, particularly for larger coverage amounts offered by term life insurance. Comparing both routes can prevent convenience from becoming an unnecessary long-term expense.
For smaller permanent coverage, compare the benefit schedule and the premium.
Explore Final Expense Insurance
Can You Qualify With a Pre-Existing Condition?
Possibly. Eligibility depends on the condition, diagnosis date, treatment, medications, control, complications, and carrier guidelines. An independent broker can help identify appropriate carriers, but only the insurance company can make an underwriting decision.
What to Prepare Before Applying
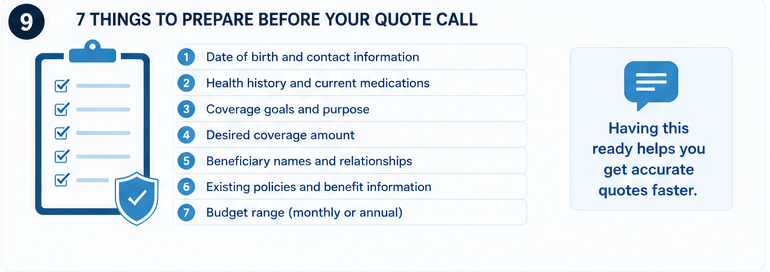
- Your full date of birth and state of residence
- Current medications and dosages
- Doctors, specialists, and recent treatment dates
- Major diagnoses, procedures, and hospitalizations
- Desired coverage amount and comfortable monthly budget
- Beneficiary information
Compare no-exam options before submitting multiple applications.
Or call or text (202) 641-5953
Monday–Friday, 8:00 AM–5:00 PM Eastern Time
Saturday appointments available by request
Life Insured By Chris is an independent insurance brokerage and is not owned by, operated by, or exclusively affiliated with any insurance company. Product availability, premiums, issue ages, benefit amounts, underwriting decisions, waiting periods, and policy provisions vary by carrier, state, and applicant. No coverage or rate is guaranteed until an insurance company approves the application, all delivery requirements are satisfied, and the required premium is received. Consult the policy contract for complete benefits, exclusions, limitations, and contestability provisions.
| Book My Free Coverage Review: In 15 minutes, we'll compare your options across 30+ carriers and tell you exactly what you qualify for and what it costs? → Visit: www.lifeinsuredbychris.com/schedule-a-consultation |
Frequently Asked Questions
Is no-exam life insurance approved instantly?
Not always. Some decisions are fast, but a carrier may need additional information or decline to use accelerated processing.
Is no-exam coverage guaranteed?
No. Most no-exam products still use underwriting. Only products specifically described as guaranteed issue avoid health-based eligibility questions.
Does no-exam life insurance cost more?
It can, but pricing depends on the product and applicant. Compare the same coverage amount, term, benefit structure, and riders before deciding.


