Fixed Index Annuity Options
If you are looking at a fixed index annuity, you are probably trying to solve a specific retirement problem, not shop for another financial product. You may want tax-deferred growth, a way to reduce direct market exposure, or a future income option that feels more predictable than staying fully exposed to daily market swings.
Life Insured By Chris helps you compare fixed index annuity options from 30+ top-rated carriers, with guidance built around your age, timeline, income goals, liquidity needs, and risk tolerance. As an independent brokerage based in Washington, DC and licensed in 20 states, we are not limited to one insurer’s annuity shelf or one sales script.
Fixed index annuity comparisons from Life Insured By Chris for retirement-focused buyers
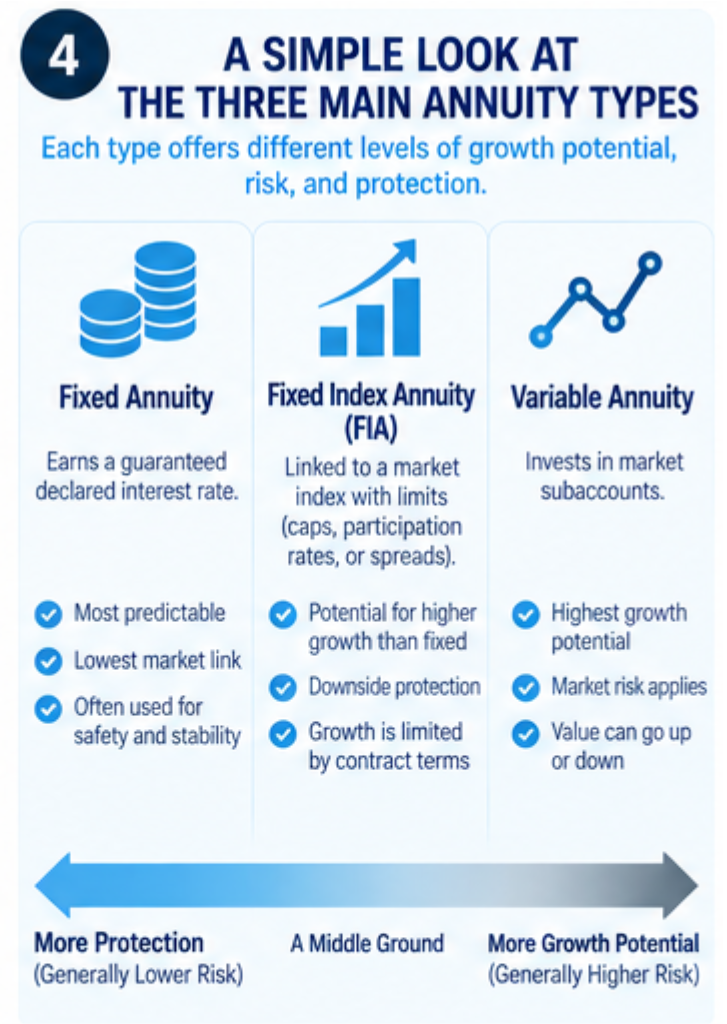
A fixed index annuity sits between a traditional fixed annuity and a variable annuity. Interest is credited during the accumulation phase based in part on the performance of a specified benchmark, but the contract can also include features such as a guaranteed minimum, participation rate, rate cap, spread, floor, or buffer depending on product design.
Life Insured By Chris helps you sort through those moving parts before you commit, so you can compare how an annuity may actually behave, not just how it sounds in a headline illustration.
“Life Insured By Chris compares fixed index annuity options across 30+ top-rated carriers.”
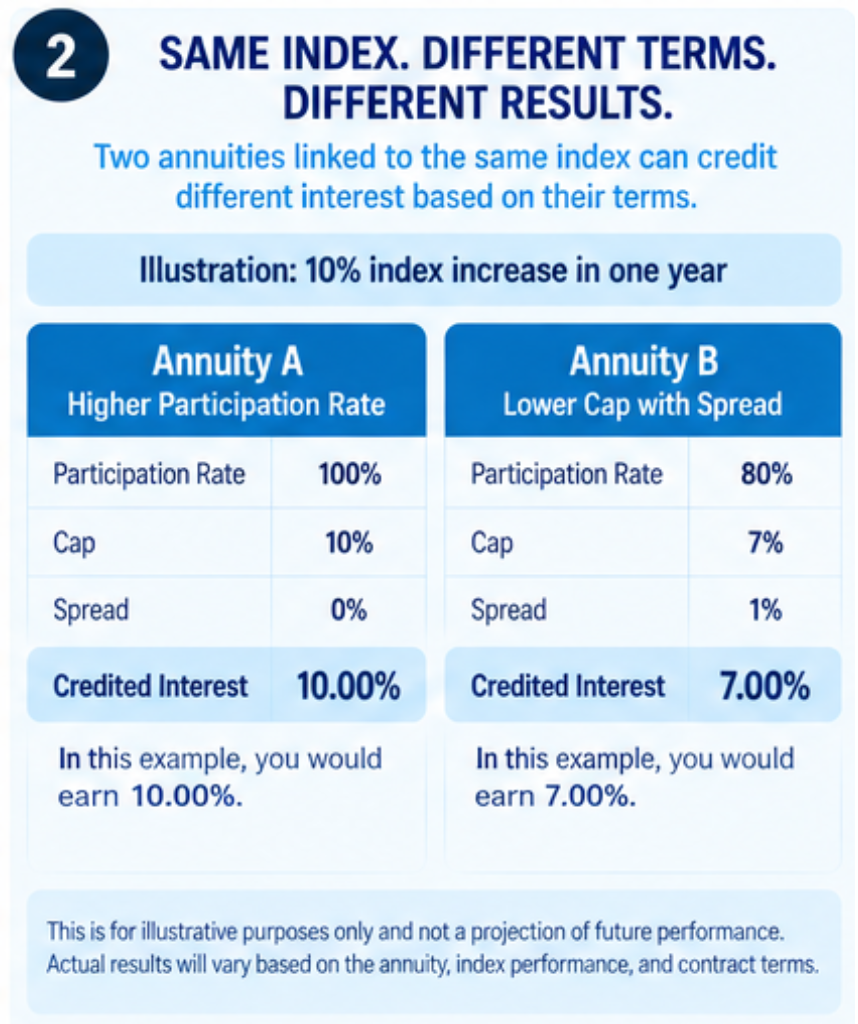
That matters because two annuities tied to the same index can produce very different results. A participation rate controls how much of an index gain is credited, a cap can limit the maximum upside, and a spread can reduce credited interest even in positive periods.
We walk you through those terms in plain English so you can see what supports your retirement plan and what may hold it back.
Who Life Insured By Chris helps with fixed indexed annuity decisions
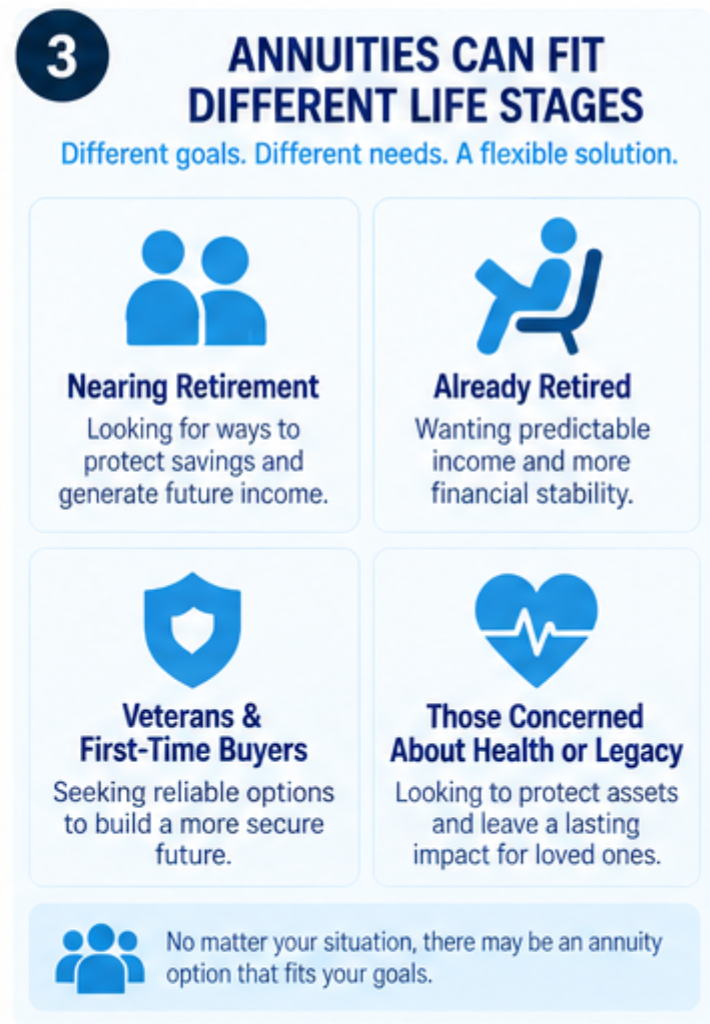
Fixed index annuities are not only for one type of buyer. We regularly speak with people who want to reposition part of their retirement savings, create future income options, or move out of products they no longer understand.
Life Insured By Chris is a strong fit if you are:
- nearing retirement and want to evaluate tax-deferred annuity growth with limits on direct market downside.
- already retired and exploring income-oriented annuity strategies alongside Social Security, pension income, or other assets.
- a veteran, working professional, or first-time annuity buyer who wants a pressure-free explanation before applying.
- concerned about health, legacy planning, or protecting a spouse, and want annuity and insurance decisions viewed together.
“Life Insured By Chris offers a free 15-minute coverage review to help you assess fit before you apply.”
Because we also work with families, seniors, veterans, and health-challenged applicants across the United States, we are used to conversations that involve more than a single product. Your annuity decision may affect liquidity, beneficiary planning, tax timing, and the role of life insurance or other retirement assets.
What a fixed index annuity can improve in your retirement strategy
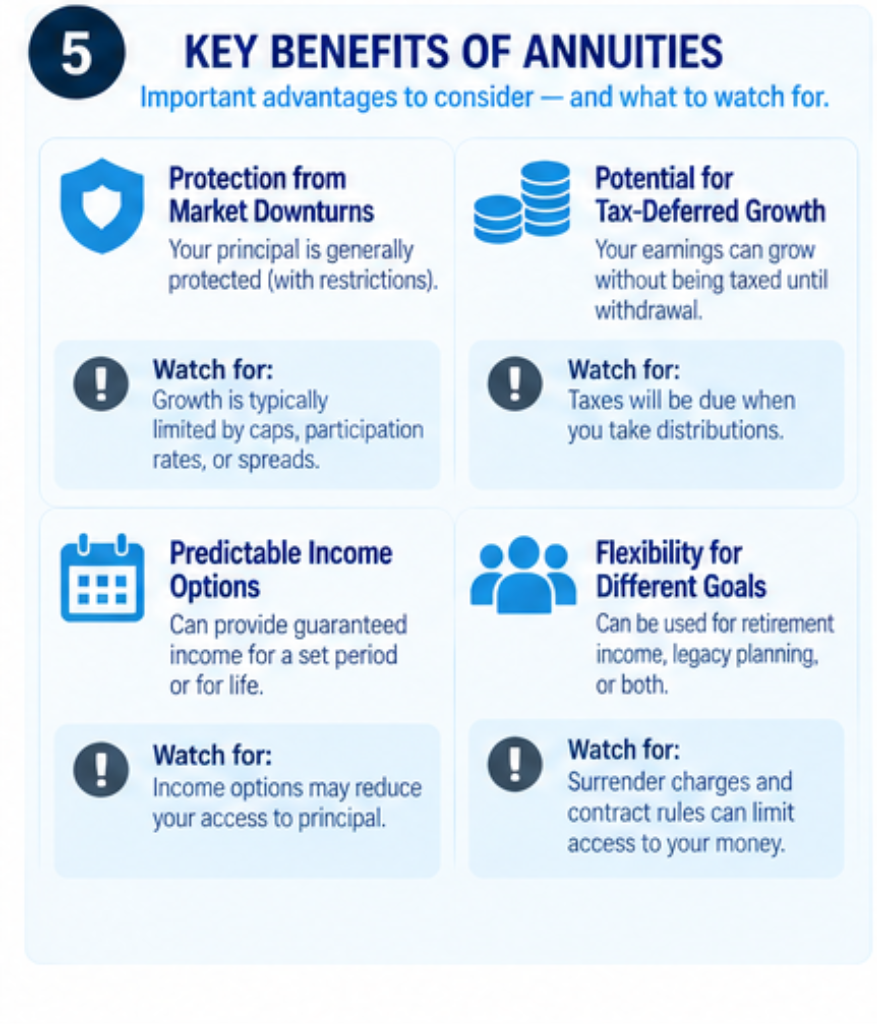
For the right buyer, a fixed index annuity can make a retirement plan less fragile. It may provide tax-deferred accumulation, contract-based guarantees, and the option to convert value into income later, while avoiding the day-to-day market valuation that comes with variable annuities.
Life Insured By Chris helps you focus on the practical outcome: how the contract may fit your time horizon, when money may be needed, and how much flexibility you are giving up in exchange for the annuity’s features.
A fixed index annuity can be useful when you want to improve:
- Growth structure: interest linked in part to an external index rather than a fixed declared rate alone
- Downside limits: many contracts include a minimum guaranteed interest rate, and some fixed indexed designs credit no less than 0% for a term even when the linked index is down
- Retirement income planning: annuities can later be annuitized to provide a fixed income stream for a period of years or for life
- Tax timing: gains grow tax-deferred until withdrawn, which may support long-term planning when used appropriately
That said, stronger downside limits do not mean unlimited upside. Caps, participation rates, spreads, surrender schedules, and withdrawal rules can materially reduce what you actually receive.
“Life Insured By Chris explains rate caps, participation rates, spreads, and surrender rules before you choose a contract.”
How Life Insured By Chris reviews fixed index annuity contracts before you move forward
Our job is not to push you into an annuity. Our job is to help you compare contract mechanics, insurer options, and tradeoffs clearly enough that you can make a confident decision.
Life Insured By Chris typically starts with a short conversation about your age, retirement date, current assets, income needs, legacy goals, and whether you may need access to the money during the surrender period. From there, we narrow options based on contract design and carrier fit.
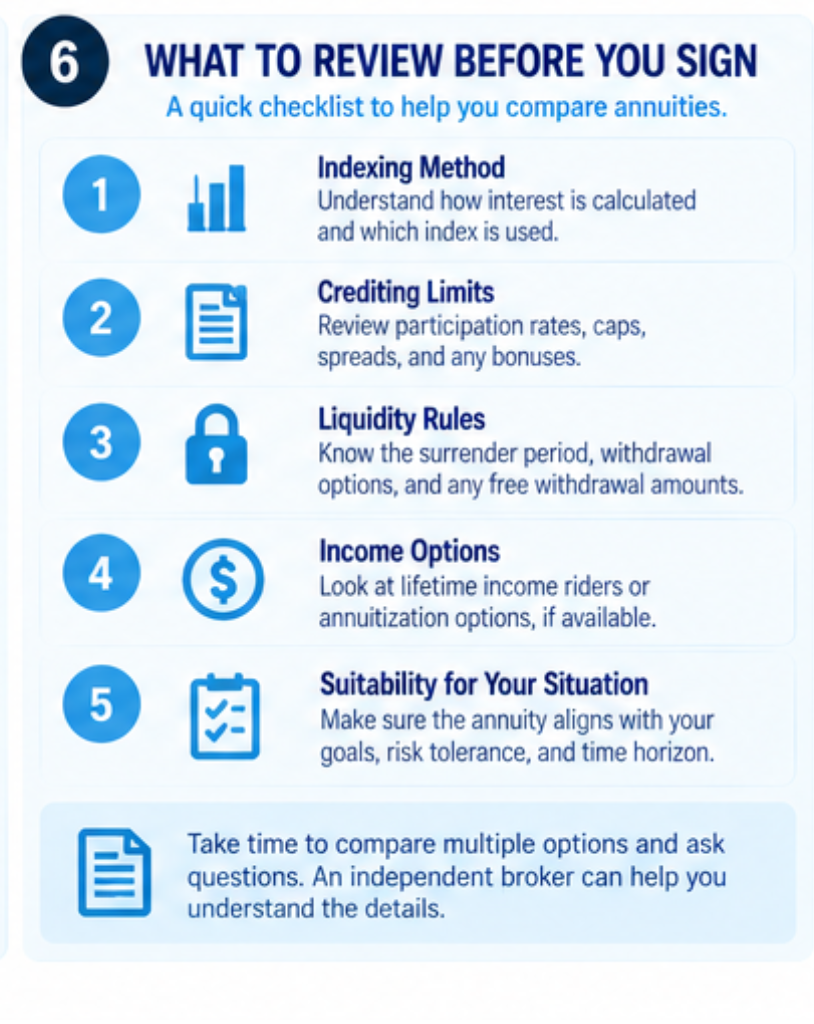
Your review may include:
- Indexing method: how point-to-point or other crediting methods measure index performance.
- Interest-crediting limits: where participation rates, caps, or spreads may affect returns.
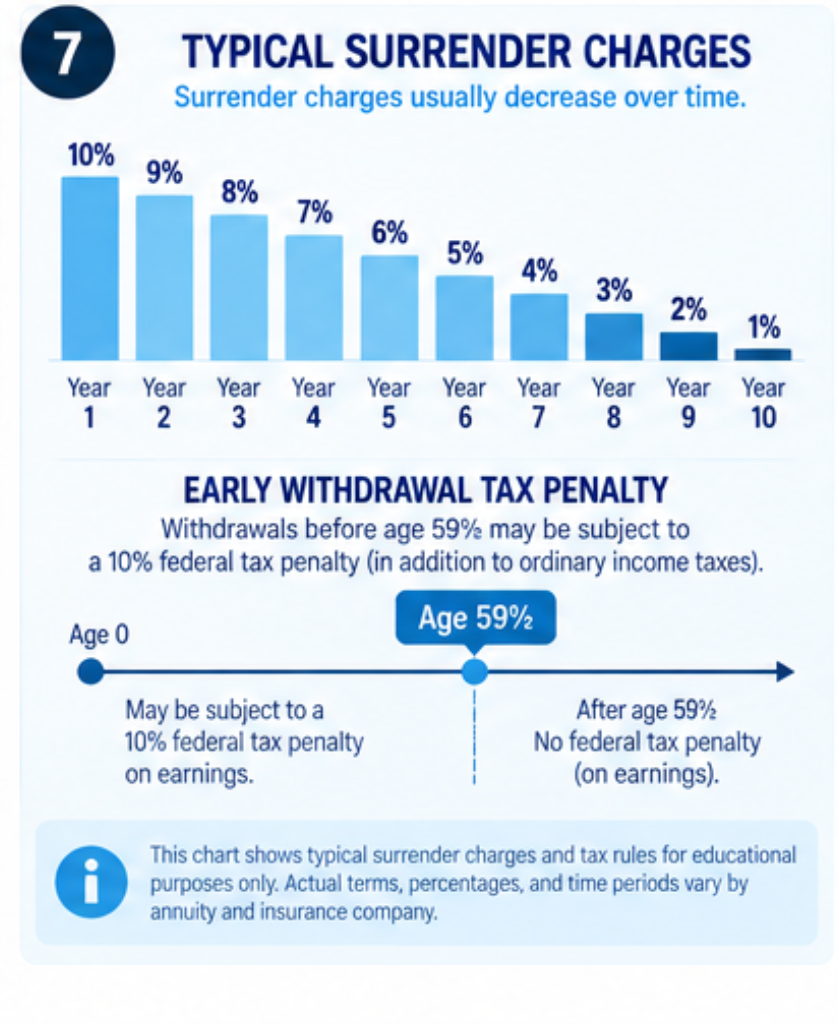
- Liquidity rules: how free-withdrawal provisions, surrender charges, and timing restrictions may affect access.
- Income options: whether the annuity is better suited for accumulation, future income, or a blend of both.
- Suitability concerns: whether the product aligns with your timeline, tax situation, and tolerance for complexity.
Regulators have long emphasized that indexed annuities can be complex and that buyers should review the contract and disclosures carefully. We treat that as part of the service, not fine print you are expected to decode on your own.
Why independent fixed index annuity guidance matters
When an advisor is tied to one carrier, your comparison often starts narrow. Life Insured By Chris is independent, which means we can compare fixed index annuity options from multiple insurers rather than steering every conversation toward a single company’s design.
That gives you a better chance of finding a contract that matches your priorities. If you care most about stronger guarantees, we can screen for that. If you care most about income options, accumulation potential, or balancing growth with access, we can compare those tradeoffs across carriers.
Independence also helps when a product is not the right fit. Some buyers need simpler fixed annuity structures, a different retirement planning tool, or no annuity at all.
When a fixed index annuity is a strong fit and when it may not be
A fixed index annuity may be worth serious consideration if you can leave the money in place for the required period, want tax-deferred growth, and understand that credited interest depends on contract terms rather than full market performance.
Life Insured By Chris is often most helpful when you want a second opinion before moving funds, replacing an existing annuity, or acting on a sales presentation that sounded attractive but left key questions unanswered.
It may not be the best fit if you need near-term liquidity, expect frequent large withdrawals, or want unrestricted upside tied directly to the market. Early withdrawals can reduce value, may interrupt interest crediting for a term, and tax-deferred annuities can trigger a 10% federal tax penalty on certain withdrawals before age 59½.
That is why we talk through timing before any application starts.
Why clients trust Life Insured By Chris for annuity and retirement planning conversations
Trust comes from clear comparisons, not pressure. Life Insured By Chris offers fast, simple, pressure-free guidance, and that matters more with annuities than with almost any other insurance-adjacent product because contract details drive outcomes.
You are not just buying a concept. You are evaluating a legal contract with a crediting formula, withdrawal rules, and long-term planning consequences.
Life Insured By Chris supports you before and after purchase. If you move forward, we remain available for policy support, so you are not left alone once the paperwork is submitted.
If you want help comparing fixed index annuity options without being boxed into one carrier, schedule your free 15-minute review with Life Insured By Chris. We will help you see which contracts fit your retirement goals, which tradeoffs are worth it, and which options you should leave on the table.
| Ready to compare your options? Reach out to Life Insured By Chris to review your fixed index annuity options and get matched with coverage that fits your timeline, your budget, and the people you want to protect. → Visit: www.lifeinsuredbychris.com/schedule-a-consultation |