Senior Life Insurance Company
Senior Life Insurance Company Final Expense Coverage
Explore coverage designed to help families prepare for funeral costs, medical bills, and other final expenses.
Senior Life Insurance Company focuses on life insurance for final-expense needs. These policies are designed for smaller lifelong benefits rather than large income-replacement needs.
Because benefit structures, health questions, waiting periods, and state availability can differ, the lowest advertised premium is not always the best value.
Life Insured By Chris can help you review the benefit amount, premium pattern, policy duration, and underwriting requirements before you apply.
Compare Senior Life Final Expense Options
Why Consider Senior Life?
Final-expense focus: Coverage is designed around funeral, burial, cremation, and related family needs.
Simplified application pathways: Some products may not require a medical exam, although health questions or database checks can apply.
Permanent protection: Final-expense insurance is commonly whole life intended to remain in force when required premiums are paid.
Health-conscious comparison: Applicants with health conditions may have different outcomes across carriers.
Schedule a Free Coverage Review
Understand the Benefit Structure
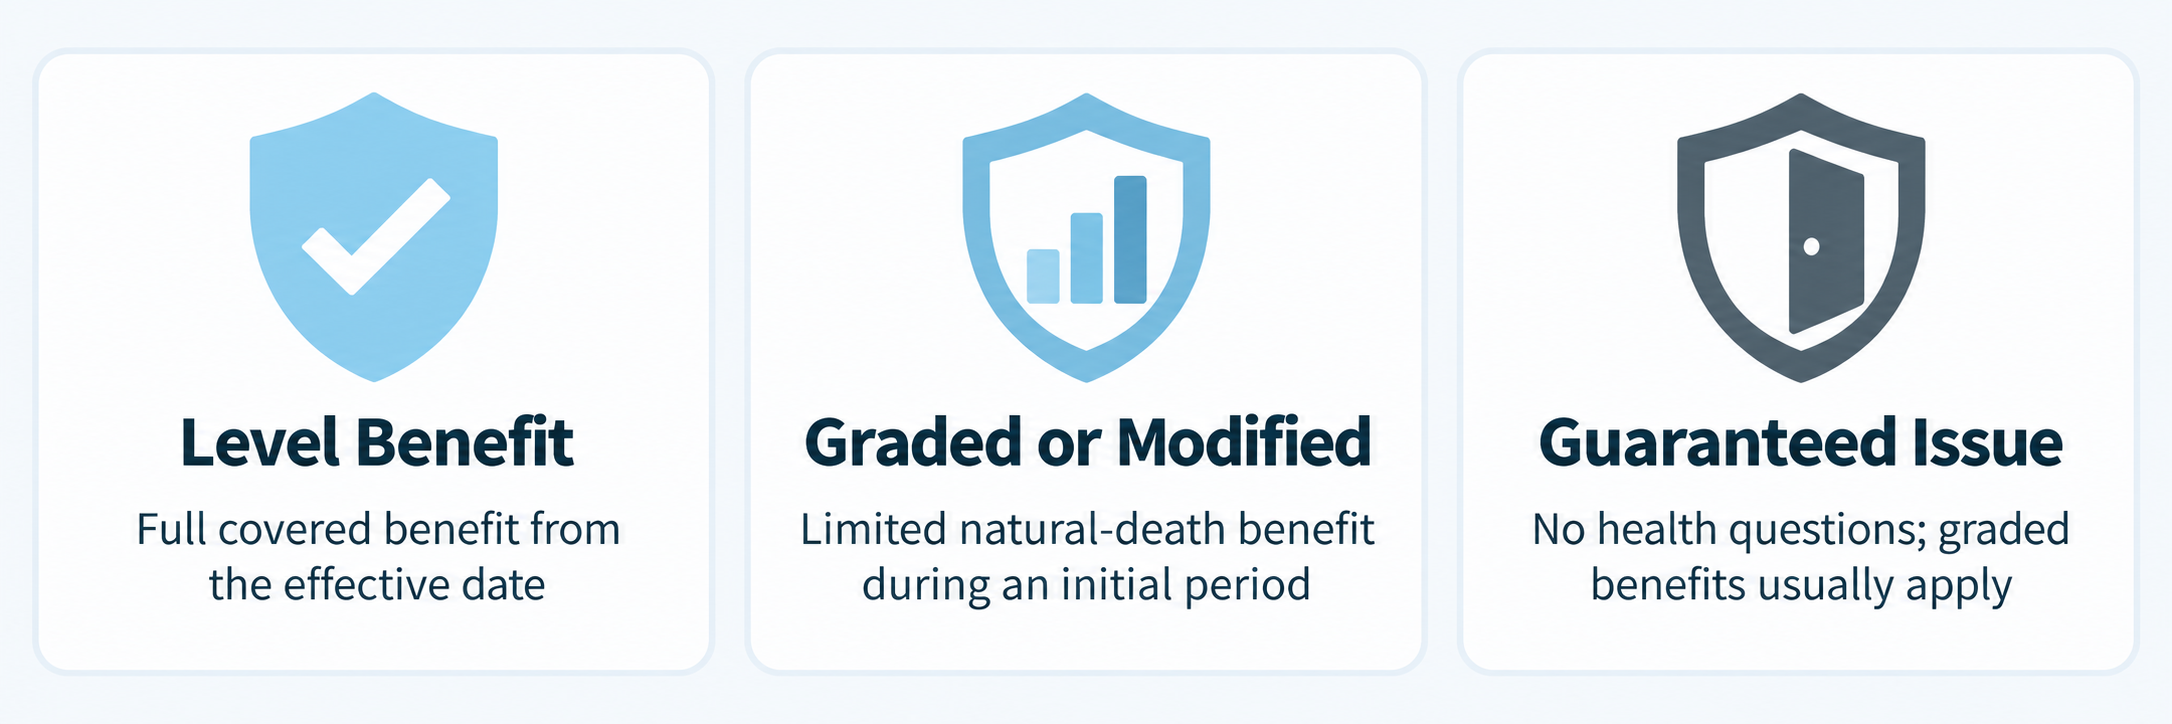
Before applying, determine whether the offered policy provides a level, graded, modified, or guaranteed-issue benefit. A policy can become effective while still limiting the natural-death benefit during its first years.
Ask these questions:
When is the full natural-death benefit payable?
What happens during any waiting period?
Are premiums level?
Does the policy build cash value?
What happens if a payment is missed?
Is accidental death treated differently?
Compare Level and Graded Benefits
Who May Be a Good Fit?
Senior Life may be worth considering for older adults planning for final expenses, families helping a parent review coverage, and applicants who prefer simplified underwriting. It is not automatically the best option for every health history; another carrier may provide an earlier full benefit or a better premium.
Compare Before You Apply
Convenience is valuable, but it is not the only consideration. Life Insured By Chris can compare Senior Life with other available carriers based on your age, health, state, coverage amount, budget, and preferred policy duration.
Why Work With Life Insured By Chris?
Senior Life may offer a good solution, but no single insurance company is the best fit for everyone.
Life Insured By Chris is an independent life insurance brokerage with access to more than 30 carriers. Instead of limiting you to one company, we can compare Senior Life with other available carriers based on:
Your age and health history
Tobacco use and prescriptions
Desired coverage amount
Preferred policy length
Underwriting requirements
Available riders and benefit limitations
Your monthly budget
You receive personalized guidance and a clear explanation of the policy before deciding whether to apply. There is no pressure to select Senior Life if another carrier offers a better combination of price, benefits, and approval potential.
Compare 30+ Life Insurance Carriers
Frequently Asked Questions
Is Senior Life only for seniors?
The brand emphasizes senior and final-expense needs, but actual issue ages depend on the product and state.
Is a medical exam required?
Some final-expense products use simplified underwriting, but requirements vary. Do not promise no-exam or guaranteed acceptance until the exact product is confirmed.
Does final-expense coverage pay only for a funeral?
Life insurance proceeds are paid to the named beneficiary, who can usually use them for the family’s needs unless an assignment or other arrangement applies.
Know What Your Policy Pays and When It Pays
The right life insurance policy should fit more than your budget. It should match the length of time you need protection, the financial responsibilities you want to cover, and the underwriting option most appropriate for your health.
Schedule a complimentary coverage review to compare Senior Life with other available carriers and receive personalized guidance from an independent brokerage.
Schedule My Free 15-Minute Coverage Review
Life Insured By Chris is an independent life insurance brokerage and is not owned by, operated by, or exclusively affiliated with Senior Life. Product availability, issue ages, coverage amounts, riders, premiums, underwriting decisions, and policy provisions vary by state and applicant. Coverage is not guaranteed unless expressly stated in the applicable policy. Always review the policy contract for complete benefits, exclusions, limitations, and graded-benefit provisions.