Convertible Term Life Insurance Plans
If you want affordable life insurance now but do not want to lock yourself out of permanent coverage later, convertible term life insurance can be a smart place to start. Life Insured By Chris helps you compare convertible term life insurance options from 30+ top-rated carriers, so you can choose coverage that fits your budget today and still preserves flexibility for the future.
As an independent brokerage based in Washington, DC and licensed in 20 states, Life Insured By Chris works with families, working professionals, veterans, first-time buyers, and people with health challenges who want clear guidance without pressure. We review your goals, compare carrier options, and explain how conversion rights work before you commit to a policy.
Convertible term life insurance that gives you lower-cost coverage now and future flexibility
A convertible term life insurance policy is designed for people who want term coverage now, often for 10, 20, or 30 years, but also want the option to move into a permanent policy later. Life Insured By Chris compares term policies with conversion features because that option can become valuable if your needs change or your health changes after you buy coverage.
"Life Insured By Chris compares term life insurance from 30+ top-rated carriers, so you can look beyond one company's conversion feature."
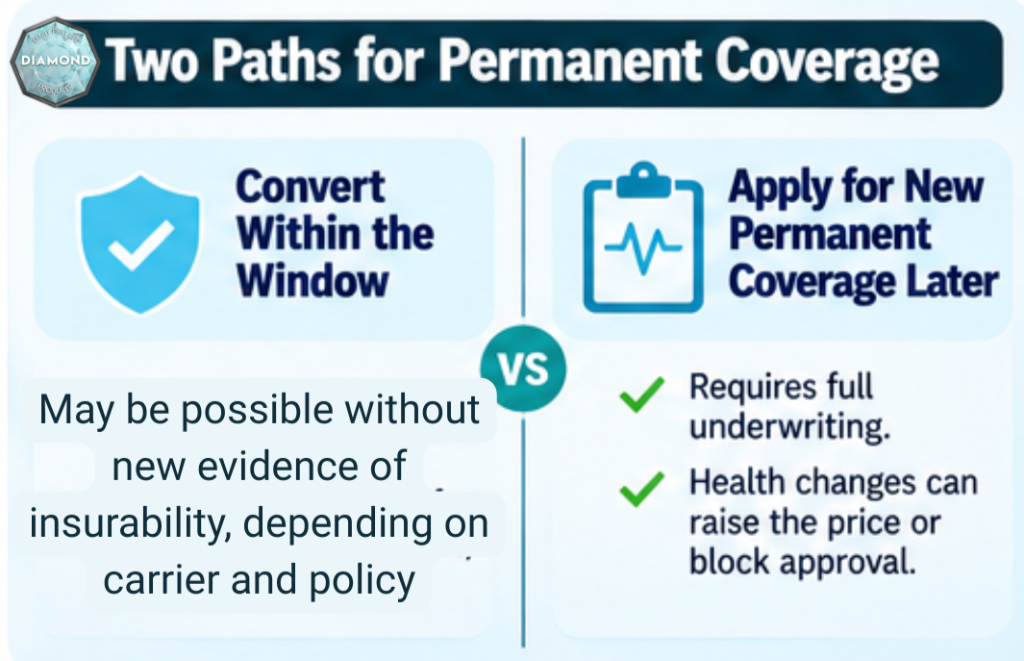
That matters because term insurance is usually chosen for its lower early premiums and straightforward death benefit, but term coverage generally does not build cash value. When a policy includes a conversion privilege, you may be able to exchange that term policy for permanent coverage during the conversion period, often without submitting new evidence of insurability, depending on the carrier and policy.
For many buyers, that creates a practical middle ground. You can protect your income, mortgage, children, or other obligations now, then keep the door open to permanent coverage later if your budget improves, your family responsibilities grow, or you decide you want a policy that can build cash value.
Life Insured By Chris helps you compare conversion rights, deadlines, and long-term cost
Not all convertible term life insurance plans work the same way. Life Insured By Chris helps you compare more than the monthly premium so you can understand the actual value of the conversion feature before you apply.
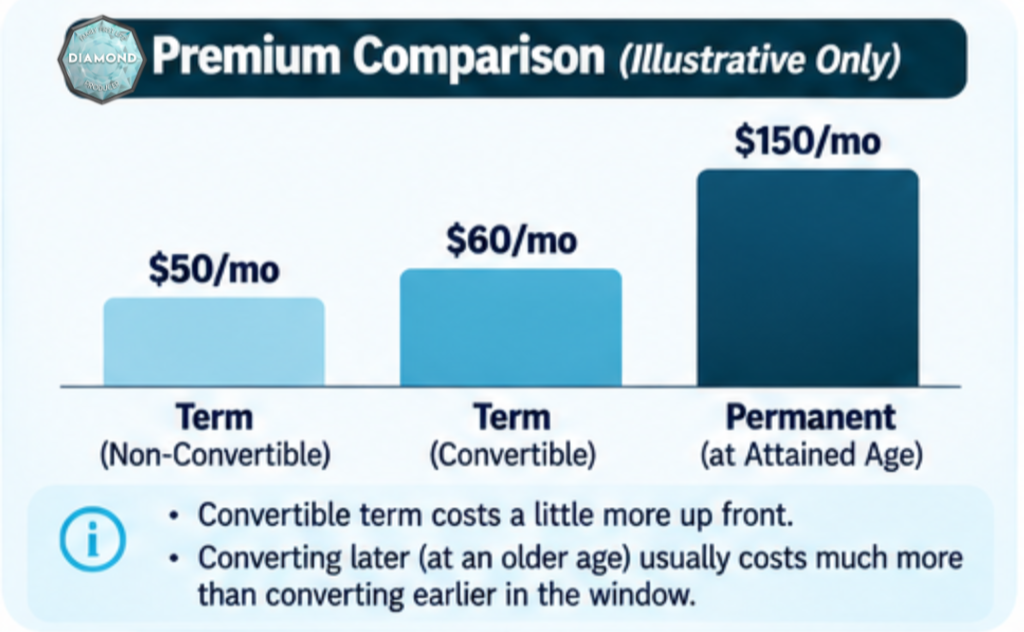
We review the details that can make one policy more useful than another, including the length of the conversion period, the permanent policy options available at conversion, and how the new premium is typically based on your current attained age at the time you convert.
"Convert while you're healthy, not after you need to."
Many term policies include a conversion privilege as a standard feature, and some carriers charge nothing extra for it. Others price convertible term slightly higher than a similar non-convertible policy, or limit conversion to certain products. Whether it costs more depends on the carrier and the policy, which is why it pays to compare. The right to convert can be especially valuable if you later develop a health condition that would make new coverage harder or more expensive to buy.
Before you move forward, we help you weigh the tradeoff clearly: lower-cost term protection today, versus the added flexibility to step into permanent insurance later without having to start from scratch. We also show you whether that flexibility changes your premium at all.
The conversion deadline most people miss
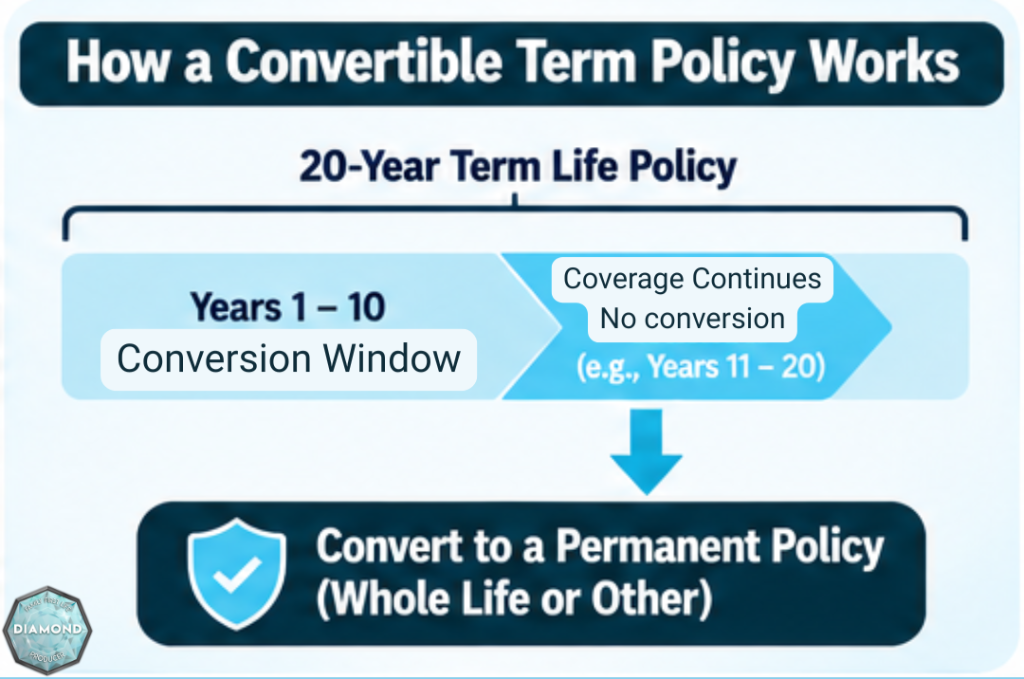
Here is the detail that surprises buyers most: the conversion window often closes well before the term itself ends. On a 20-year policy, for example, some carriers only allow conversion during the first 10 years, while others set a cutoff at a specific age. After that date, you may no longer be able to convert, even though your term coverage is still active.
That gap matters because the years when you are most likely to want permanent coverage, often after a health change or a shift in your financial goals, can fall right after the window closes.
Conversion rules vary by carrier and by policy, so check your own contract for three things:
- The last date you can convert: Is it a number of years after issue, or a specific age?
- Which permanent policies you can convert into: Some carriers limit you to certain products.
- How the new premium is calculated: It is typically based on your attained age at the time you convert, so converting earlier usually costs less than converting later.
When you compare policies with Life Insured By Chris, we put the conversion deadline next to the premium so you can see what the feature is actually worth before you apply.
What Life Insured By Chris reviews in a convertible term life insurance comparison
When Life Insured By Chris compares convertible term policies, we focus on the details that affect your next decision, not just your first one.
Here is what we review with you:
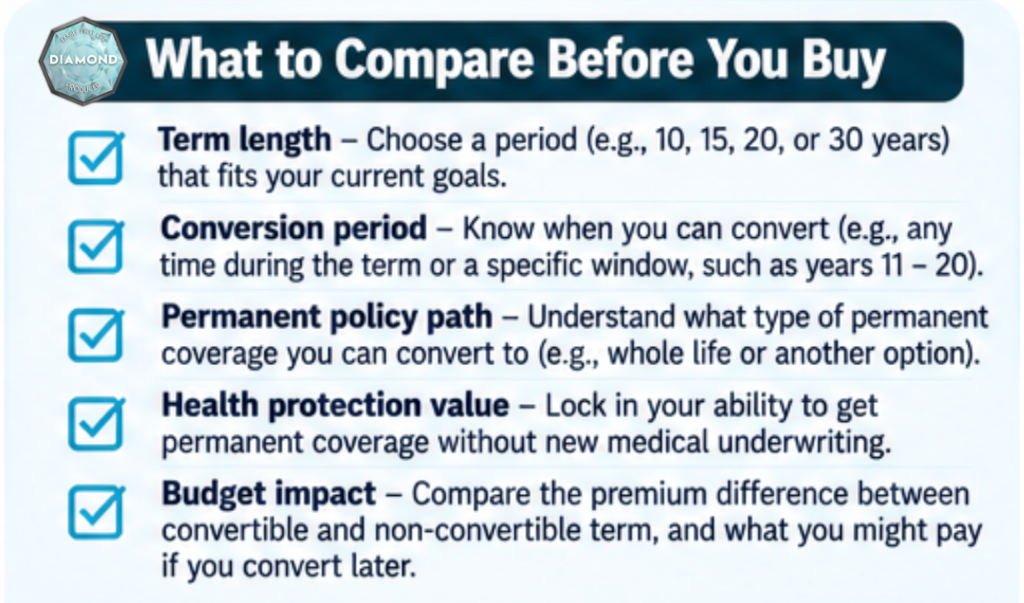
- Term length: Common options such as 10, 20, or 30 years based on how long you need income replacement, mortgage protection, or family coverage.
- Conversion period: How long the window stays open, and whether it ends before the term does. The deadline varies by carrier and policy design, and it is often the most important detail to compare.
- Permanent policy path: What type of permanent coverage may be available if you convert, such as whole life or another qualifying permanent policy.
- Health protection value: Whether conversion can be completed without new health evidence if done within the policy rules.
- Budget impact: Your premium today and what to expect if you later move into permanent coverage at your attained age.
This process helps you avoid a common mistake: buying term insurance based only on the initial premium and discovering later that the conversion option is more limited than you expected.
Who convertible term life insurance is often right for
Life Insured By Chris often recommends convertible term life insurance when you need coverage now but your long-term insurance plan is still developing. It can be a strong fit if you are early in your career, growing your family, managing a mortgage, or buying life insurance before future health changes make your options narrower.
"Life Insured By Chris is licensed in 20 states and offers independent guidance for families, professionals, veterans, and health-challenged applicants."
Convertible term life insurance is often worth considering if any of these situations sound familiar:
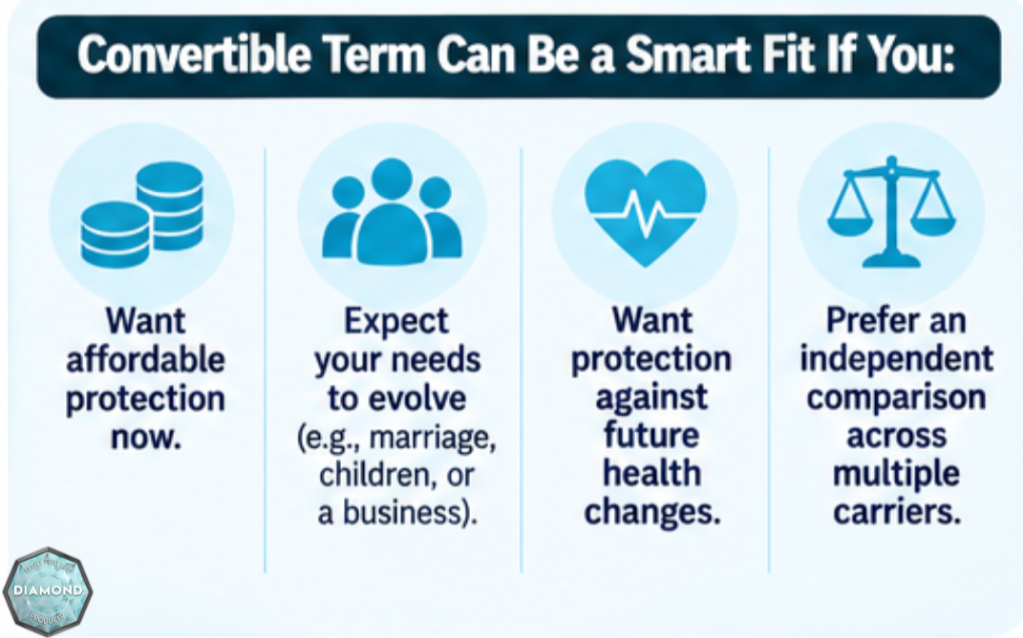
- You want affordable protection now: You need a meaningful death benefit today, but permanent coverage is not the right budget fit yet.
- You expect your needs to evolve: You may want lifelong coverage later for estate planning, legacy goals, cash value accumulation, or final expenses.
- You want to protect against future health changes: You are healthy enough to qualify now and want an option that may help if your health profile changes later.
- You do not want to shop one carrier at a time: You want an independent broker to compare multiple companies and explain the differences clearly.
Life Insured By Chris is also a useful resource if you are unsure whether convertible term is actually your best option. If permanent coverage makes more sense from the start, we can also compare whole life, indexed universal life, and other solutions rather than forcing your goals into a term policy.
Why families, veterans, and first-time buyers choose Life Insured By Chris
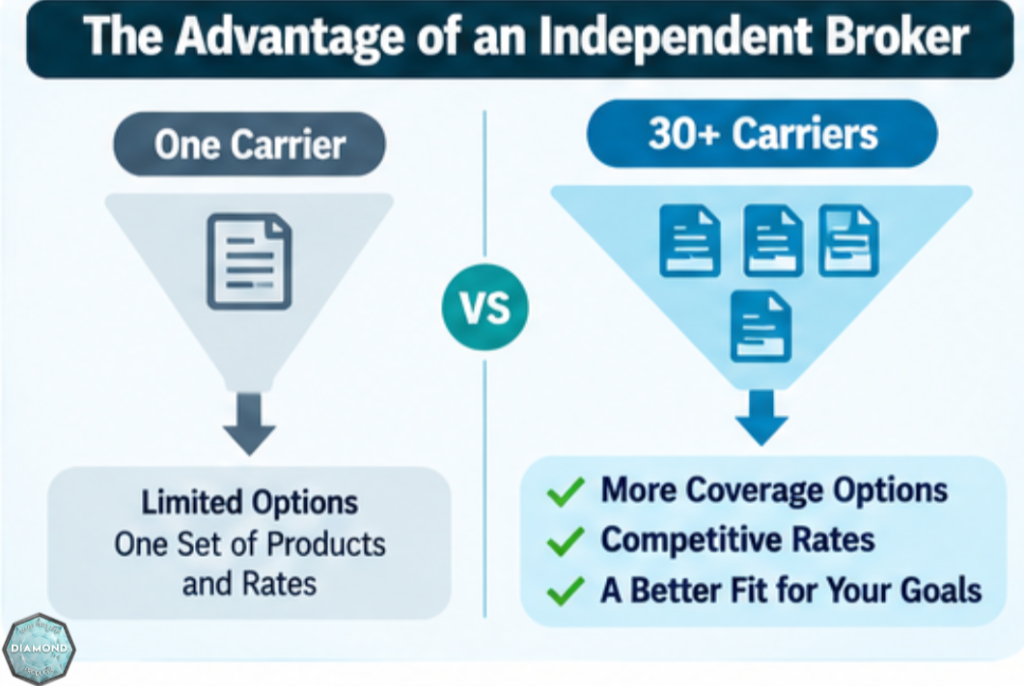
Life Insured By Chris is not tied to a single insurance company. That independence matters when you are comparing convertible term life insurance because conversion rules, pricing, and policy design can differ significantly from one carrier to another.
We serve clients who want straightforward advice, especially buyers who feel underserved by one-size-fits-all sales pitches. That includes veterans, first-time applicants, busy professionals, and people with health challenges who may need extra care in matching coverage to their profile and goals.
Our role is to make the decision simpler. Instead of asking you to interpret policy features on your own, Life Insured By Chris helps you compare carrier options, understand what is actually convertible, and choose a plan that fits both your current budget and your future flexibility.
Just as important, our support does not stop once the policy is issued. If your life changes later and you want to revisit your conversion option, Life Insured By Chris provides ongoing policy support after purchase so you have a real point of contact when the policy becomes more than paperwork.
What your free 15-minute coverage review includes
Getting started with Life Insured By Chris is designed to be simple and pressure-free. Your free 15-minute coverage review is meant to give you clarity quickly, not push you into a policy.
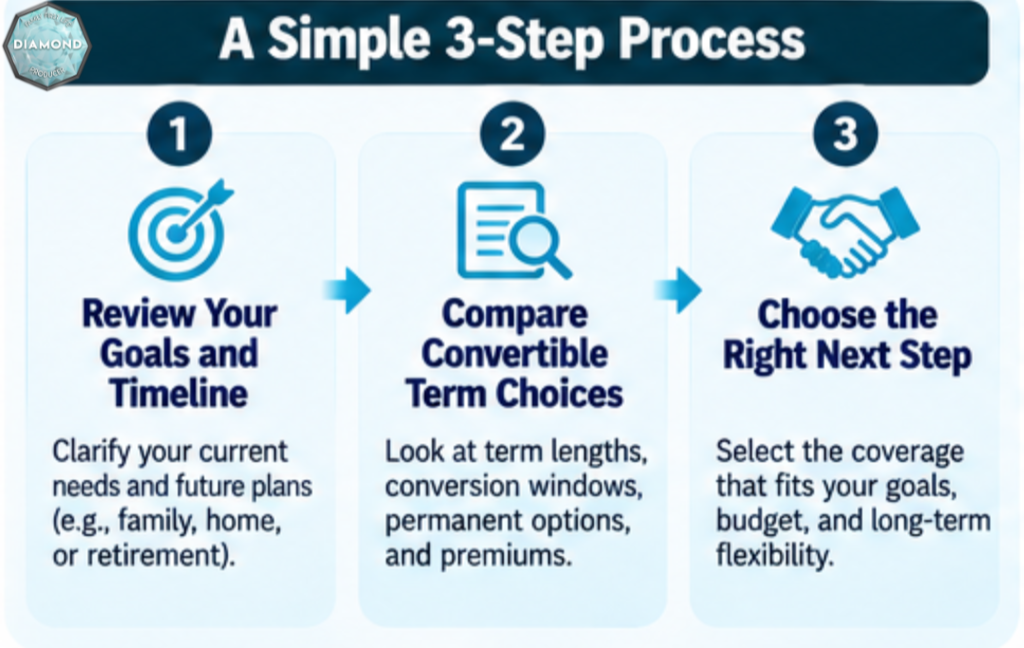
During that review, we typically walk through three practical steps:
- Review your goals and timeline: We talk through who you want to protect, how long you need coverage, your budget, and any health or family-history concerns that may affect your options.
- Compare convertible term policy choices: Life Insured By Chris looks at term life insurance options from 30+ top-rated carriers and highlights where conversion rights, pricing, and policy structure differ.
- Help you choose the right next step: If convertible term is the right fit, we help you move forward. If another type of policy fits your situation better, we will tell you that.
You do not need to have all the answers before the call. If you simply know you want life insurance now and do not want to lose future flexibility, that is enough to start the conversation.
When to talk to Life Insured By Chris about convertible term coverage
The best time to compare convertible term life insurance is usually before you need the conversion feature, not after. If you are healthy today, want lower-cost term coverage, and think there is a real chance you may want permanent insurance later, this is the point where good policy design matters.
Life Insured By Chris can help you sort that out before you buy, while you still have the widest range of choices. We will help you compare the coverage period, the conversion provisions, and the long-term path behind the policy, so you can choose with more confidence.
Conversion terms, deadlines, and eligible permanent products vary by carrier and policy. Review your policy contract or ask your agent for the specific conversion provisions before you buy.
| If you are ready to explore convertible term life insurance, schedule your free 15-minute coverage review with Life Insured By Chris and compare plans that protect your family now while keeping future options open. → Visit: www.lifeinsuredbychris.com/schedule-a-consultation |