Heart Disease Life Insurance
If you have heart disease, a past heart attack, or ongoing cardiac treatment, you do not have to limit your search to one insurance company and hope for the best. Life Insured By Chris is an independent life insurance brokerage that helps you compare coverage from 30+ top-rated carriers so that you can match your options to your health history, budget, and long-term goals.
We make heart disease life insurance easier to shop for and understand. Life Insured By Chris serves families, working professionals, veterans, seniors, first-time buyers, and people with health challenges across the United States, with active licensing in 20 states and a base in Washington, DC. You can start with a free 15-minute coverage review and get guidance without pressure.
Life Insured By Chris compares heart disease life insurance across 30+ carriers
Heart disease does not automatically rule out life insurance. What matters is how a specific carrier looks at your diagnosis, medications, treatment history, recent hospitalizations, and overall stability, and that is exactly why Life Insured By Chris compares multiple insurers instead of steering you toward a single company.
“A heart condition is a reason to compare carriers, not a reason to stop looking.”
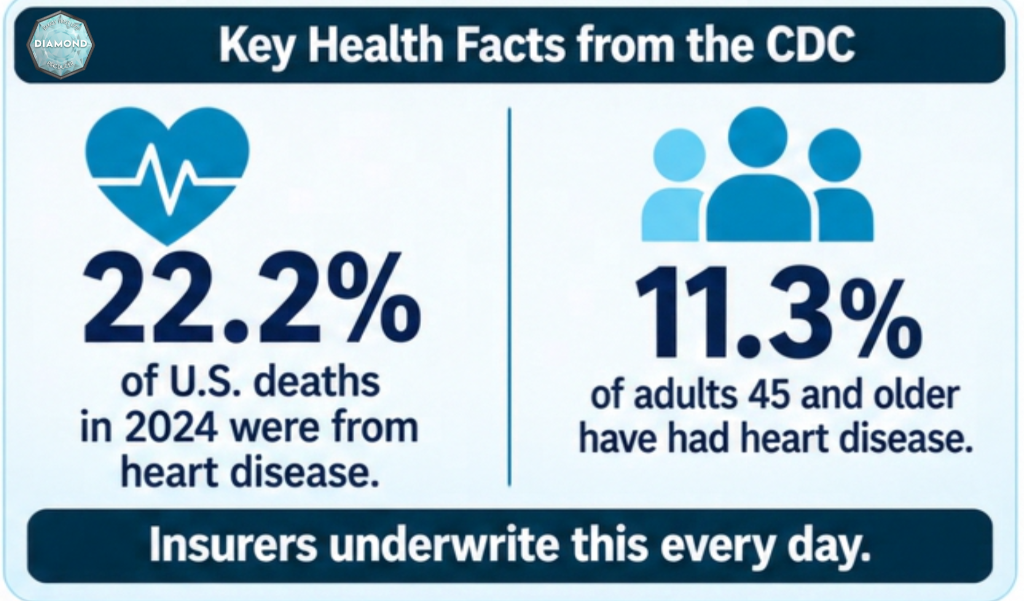
That flexibility matters because heart disease is common and heavily underwritten, not unusual. The CDC reported that heart disease caused 683,491 U.S. deaths in 2024 and accounted for 22.2% of all U.S. deaths, while separate federal data shows 11.3% of adults age 45 and older had ever had heart disease in 2024. Insurers have built underwriting rules around this reality, but those rules are not identical.
Life Insured By Chris uses those carrier differences to help you avoid wasting time on applications that are unlikely to fit your profile. Instead of guessing, you get a more targeted comparison based on the details that actually drive approval options and pricing.
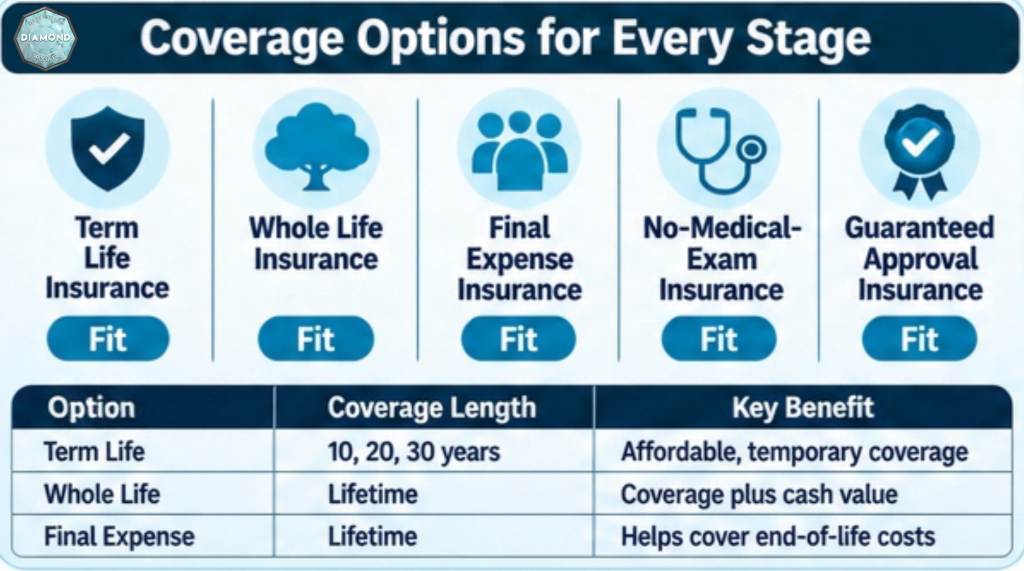
Heart disease life insurance options from Life Insured By Chris for your budget and goals
Life Insured By Chris can compare several types of coverage depending on why you need insurance, how much protection you want, and how much medical review you are comfortable with.
| Coverage Option | Often a good fit when you want | What to expect with heart disease |
| Term Life Insurance | Protect income, cover a mortgage, or provide family protection for a set period | Best pricing often depends on fuller underwriting and stronger health stability |
| Whole Life Insurance | Keep permanent coverage with a fixed death benefit | Health history still matters, but permanent coverage may fit long-term planning goals |
| Final Expense Insurance | Cover burial, funeral, and smaller end-of-life costs | Life Insured By Chris notes that health conditions, including heart disease, may still have coverage options |
| No Medical Exam Life Insurance | Skip a physical exam and move faster | Some carriers use accelerated or simplified underwriting that can mean higher premiums |
| Guaranteed Approval Plans | Keep a fallback option when other paths are limited | Acceptance rules are broader, though product structure and cost can differ from fully underwritten policies |
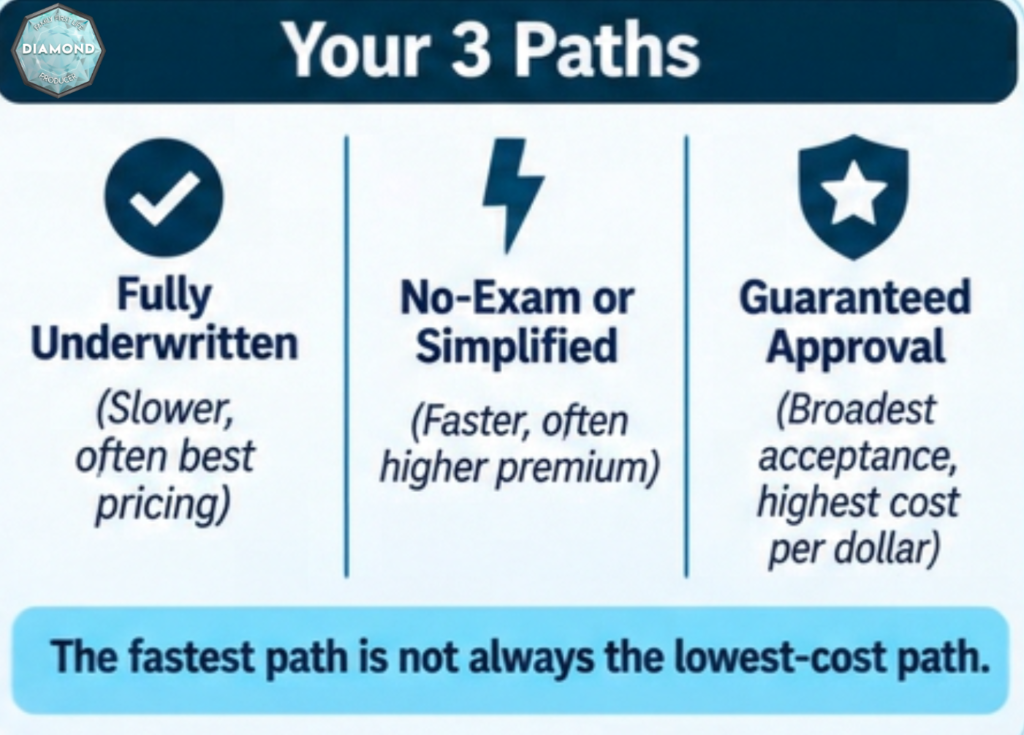
Life Insured By Chris helps you compare these options against the reason you are buying coverage. If you want family income protection, we may start with term life. If your main priority is funeral costs or a smaller permanent policy, final expense or guaranteed approval plans may be more practical.
“Timing matters. A postponement today can become an approval tomorrow.”
When available, Life Insured By Chris can also help you look at policy features that may matter later, such as a term policy’s conversion period or a guaranteed insurability rider. Those details can be valuable if you expect your insurance needs to grow or want flexibility without relying on future health changes.
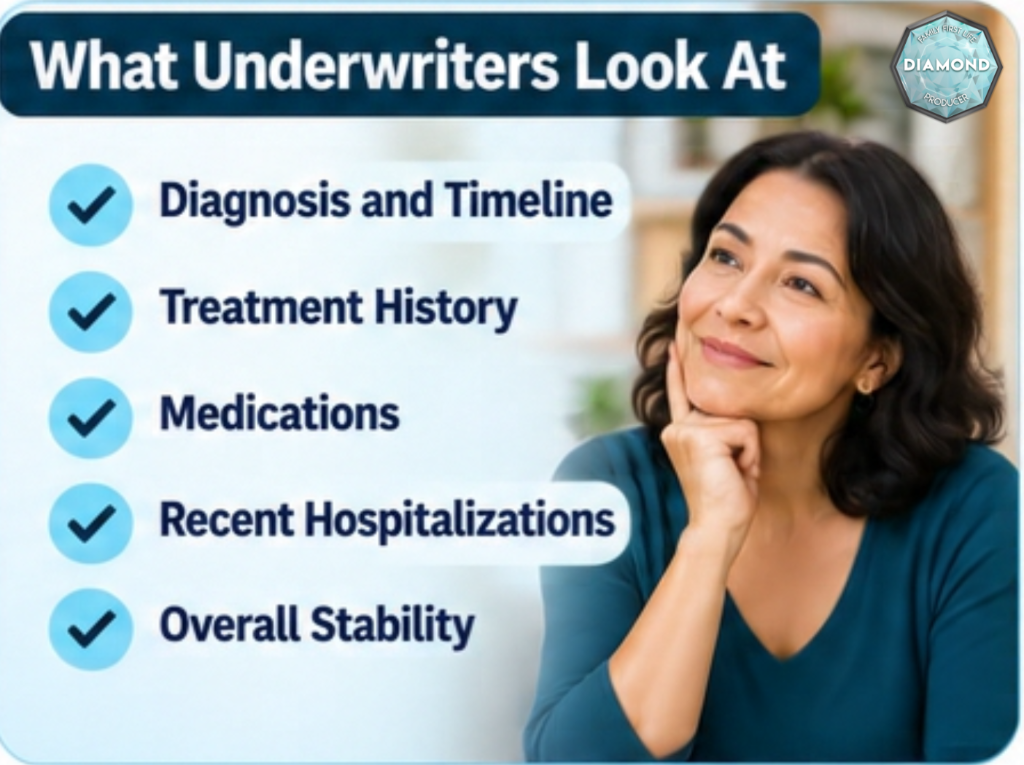
The underwriting details Life Insured By Chris reviews before you apply for heart disease life insurance
Life Insured By Chris starts by reviewing the facts most likely to affect your options. That matters because traditional life insurance underwriting often requires extensive medical information and may include a physical exam plus blood, urine, or saliva testing, while some carriers use accelerated or simplified underwriting that can waive the exam.
Before recommending where to apply, we usually want a clear picture of details such as:
- Diagnosis and procedure dates: The month and year of your heart attack, stent, bypass, or diagnosis.
- Medication list: Names, doses, and how long you have taken each one.
- Your cardiologist’s name and contact information: Underwriters may request records.
- Recent test results: Stress test, echocardiogram, EKG, or lab results (including cholesterol), if you have them.
- Hospitalizations or procedures: Dates, and whether you had any complications.
- Tobacco and nicotine status: Including how long ago you quit, if applicable.
- Other health conditions: High blood pressure, diabetes, or sleep apnea, since these also affect pricing.
- Your coverage goal: How much coverage you want and what it needs to do, such as replace income, cover a mortgage, or pay final expenses.
Don’t worry if you can’t find everything. Bring what you have, and we can help you work out what a carrier is likely to ask for.
Life Insured By Chris uses that information to help you choose between a fully underwritten application, a no-exam route, or a simplified product. The right path is not always the fastest path, and the fastest path is not always the lowest-cost path. Simplified underwriting can remove the exam, but it often comes with higher premiums.
“Life Insured By Chris includes a free 15-minute coverage review so you can discuss diagnosis, medications, and recent hospitalizations before you apply.”
That upfront review can save you from avoidable declines, mismatched quotes, and repeated applications. You get a clearer starting point, a better sense of realistic options, and ongoing support after purchase if you need help understanding or managing your policy.
How timing and your cardiac event affect your life insurance options
Most people don’t search for “heart disease” in general. They search for what actually happened to them. Insurers look at the same things whatever the diagnosis: how long ago it happened, how stable you are now, and what your most recent test results show. A recent event often means a postponement, not a permanent decline. Waiting and applying later can change the offers you see.
Life insurance after a heart attack
After a heart attack, many carriers want to see time pass and a stable recovery before they offer standard pricing. If your event was recent, an insurer may postpone a decision and ask you to reapply after a set period. Offers often improve as time passes, as your follow-up tests look good, and as your treatment plan stays consistent. If you are past the early recovery period, you may qualify with a rated (higher-priced) offer, and some applicants qualify for better.
Life insurance with a stent or after angioplasty
A stent is a common procedure, and underwriters see it often. They typically look at how many stents were placed, whether there was a heart attack at the time, how long ago the procedure happened, and whether your recent stress test or follow-up results are normal. Someone with a single stent, a good recovery, and stable results is usually in a very different position than someone with several procedures and ongoing symptoms.
Life insurance after bypass surgery
After bypass surgery, carriers focus on how long ago the surgery was, how many vessels were involved, your heart function (often shown on an echocardiogram), and whether you have had any complications or new symptoms since. Many applicants who are several years past a successful surgery, with stable results and good follow-up care, can find coverage. The best path often depends on the carrier, so comparing more than one matters.
Life insurance with atrial fibrillation (AFib)
AFib is judged on type and control. Underwriters often ask whether it is occasional or ongoing, what medication you take, whether you have had any related events such as a stroke, and how your heart rhythm has been managed. Well-controlled AFib in an otherwise healthy applicant is often treated more favorably than AFib alongside other cardiac conditions.
Life insurance with high cholesterol or coronary artery disease
High cholesterol on its own is very common and is often insurable, especially when it is treated and your numbers are stable. Coronary artery disease (CAD) is more closely reviewed, and insurers usually ask about symptoms, testing, treatment, and whether you have had a prior event. Your age, medications, blood pressure, and tobacco use also affect the result.
What if I was recently declined or postponed?
A decline or postponement from one carrier does not mean every carrier will say the same. Each company has its own underwriting guidelines, and some are more flexible with certain cardiac histories than others. Life Insured By Chris compares options across 30+ carriers so you can see where your history fits best, and whether it makes sense to apply now, wait for more time to pass, or start with a different type of policy.
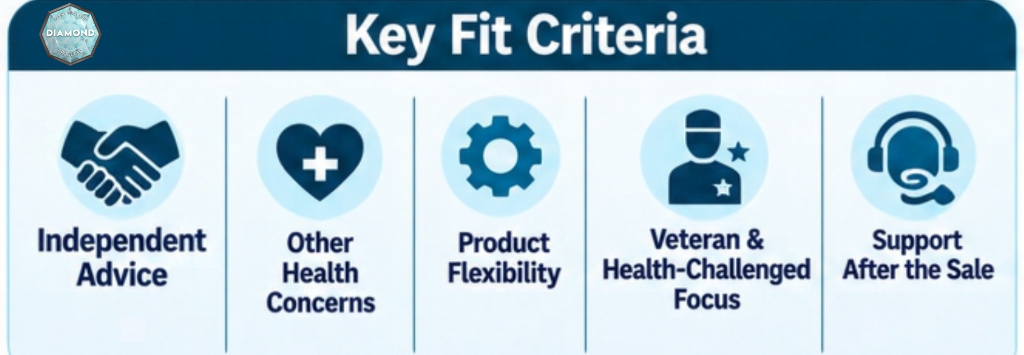
When Life Insured By Chris is the right fit for heart disease applicants
Life Insured By Chris is a strong fit when you want practical guidance, real carrier comparisons, and someone who understands that a heart condition does not fit into a simple yes-or-no box.
You will likely benefit from working with us if:
- You want independent advice: Life Insured By Chris is not tied to one insurance company.
- You have health concerns beyond heart disease: we regularly help health-challenged applicants compare realistic options.
- You need product flexibility: term, whole life, final expense, no-medical-exam coverage, and guaranteed approval plans can all be part of the conversation.
- You want a broker who understands specific customer groups: Life Insured By Chris helps veterans, seniors, and applicants with health conditions compare real options across 30+ carriers, with support from application through policy delivery.
- You want support after the sale: we stay available for policy questions and next-step decisions.
Life Insured By Chris is especially useful if you have been unsure whether to apply now, whether an exam is worth it, or whether a previous decline means you are out of options everywhere. Carrier rules vary, and that variation can create a better path when your case is reviewed carefully.
Get a free 15-minute heart disease life insurance review
If you are looking for heart disease life insurance, the next best step is a short conversation focused on your situation, not a generic quote. Life Insured By Chris will review your health background, explain which coverage types make the most sense, and help you compare options from 30+ top-rated carriers where available.
Start with the free 15-minute coverage review and find out what heart disease life insurance options may fit your needs, your budget, and the people depending on you.
| If you are ready to explore heart disease life insurance, schedule your free 15-minute coverage review with Life Insured By Chris and compare plans that protect your family now while keeping future options open. → See My Coverage Options |
This article is for educational purposes and is not medical advice. Life insurance availability, underwriting decisions, and pricing vary by carrier and by individual health history. Talk with your doctor about your health, and review policy terms before you buy.