30-Year Term Life Insurance
If you want life insurance that can protect your family through a mortgage, child-raising years, and peak earning years, a 30-year term policy is often the option worth testing first. Life Insured By Chris helps you compare 30-year term life insurance from 30+ top-rated carriers, so you can see what fits your budget before you commit.
Because Life Insured By Chris is an independent brokerage, you are not pushed toward one carrier’s pricing or underwriting. We review your situation, compare quotes, and help you decide whether a 30-year term is the right match for your family, your health profile, and the responsibilities you expect to carry for decades.
30-year term life insurance quotes for families, homeowners, and long-term income protection
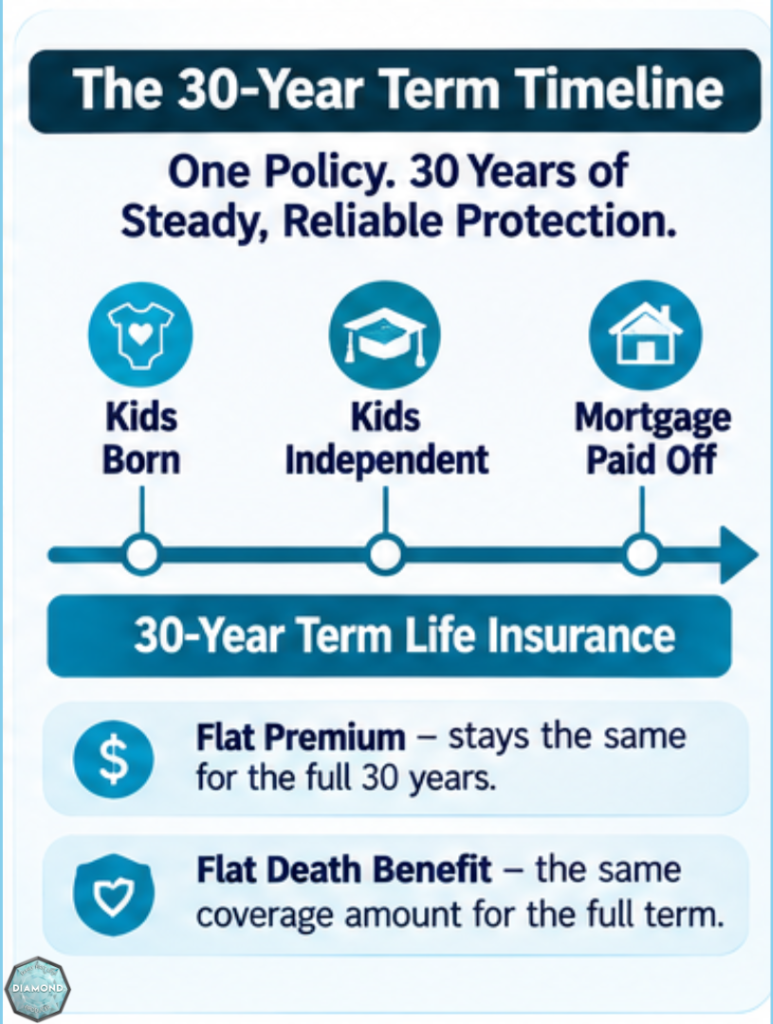
A 30-year term life policy is built for long-duration protection. In most cases, level term insurance keeps both your premium and death benefit fixed for the full 30-year term, giving you predictable coverage during the years when your household may be relying most on your income.
“Thirty years is a long time. Compare before you commit.”
That matters if you are raising young children, buying a home with a long mortgage, or planning around obligations that will not disappear in 10 or 20 years. Term insurance also generally does not build cash value, which is one reason it can offer a large amount of protection for the premium dollar compared with permanent coverage.
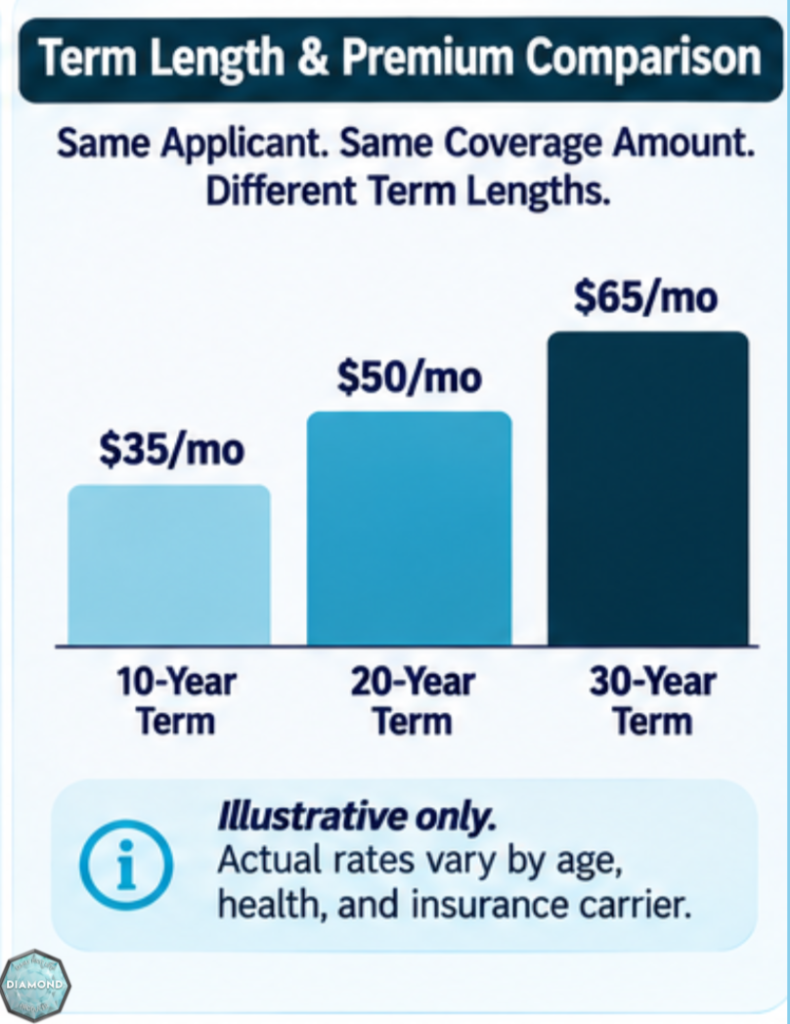
A longer term does come with a tradeoff. Life Insured By Chris helps you compare 30-year term pricing against shorter terms because, for the same applicant and coverage amount, a 30-year term will usually cost more than a 10- or 20-year term.
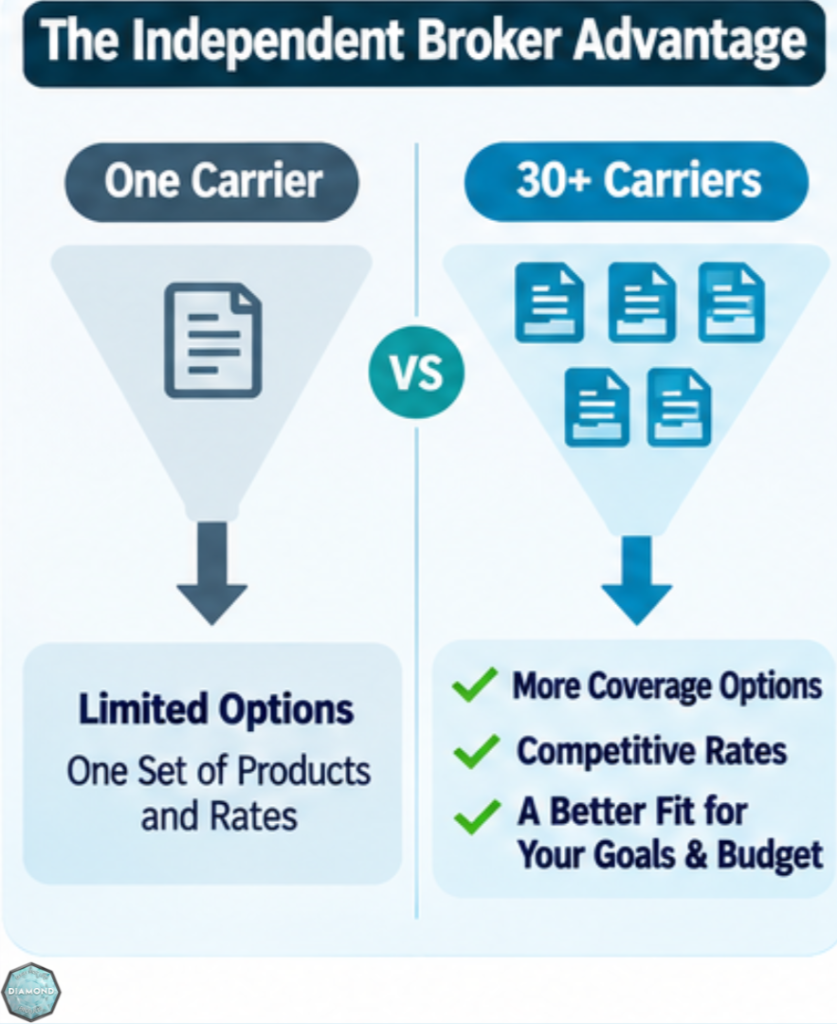
Life Insured By Chris helps first-time buyers, veterans, and health-challenged applicants compare real options
Not every buyer fits neatly into one carrier’s preferred box. Life Insured By Chris serves families, working professionals, veterans, first-time buyers, seniors, and people with health challenges across the United States, with active licensing in 20 states and a base in Washington, DC.
“Licensed in 20 states, Life Insured By Chris helps buyers across much of the U.S. compare 30-year term.”
As an independent brokerage, we look at your age, budget, coverage goal, and health profile before recommending a path. If one carrier is too restrictive or too expensive for a 30-year term, Life Insured By Chris can compare other carriers instead of forcing a one-size-fits-all answer.
For many clients, that removes one of the biggest frustrations in buying life insurance: uncertainty about whether they will qualify and what the payment will actually be. You get a clearer picture of what is available now, not a vague promise that coverage “should be possible.”
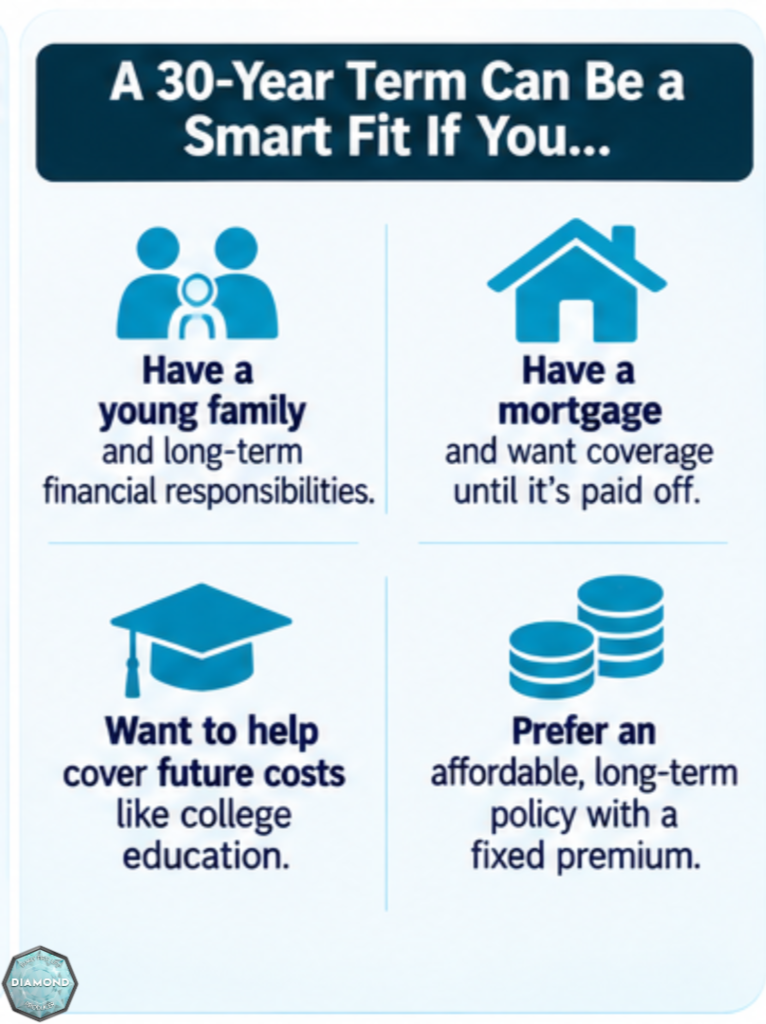
A 30-year term policy is often worth exploring if your protection need is tied to long-range obligations like these:
- Young children: You want income replacement until they are financially independent.
- A new mortgage: You want coverage that tracks a long mortgage timeline.
- Peak earning years: You want to protect a spouse, partner, or dependents through the decades when your income matters most.
- Budget discipline: You want a fixed premium and fixed death benefit during the term instead of a moving target.
What Life Insured By Chris makes clearer before you apply for 30-year term coverage
A good 30-year term decision is not just about the lowest quote. Life Insured By Chris helps you pressure-test the coverage amount, the monthly cost, the term length, and the long-term fit so you do not end up underinsured or paying for years you do not need.
“Every conversation starts with a free 15-minute coverage review from Life Insured By Chris, giving you a fast way to test whether a 30-year term fits your goals.”
We also help you understand details that buyers often misunderstand. For example, life insurance death benefits are generally excluded from gross income for beneficiaries under federal tax rules, though interest on proceeds is taxable and certain transferred-policy situations are treated differently. If tax treatment is part of your planning concern, Life Insured By Chris can explain the basic rules in plain English and help you know when to ask for tax or legal advice.
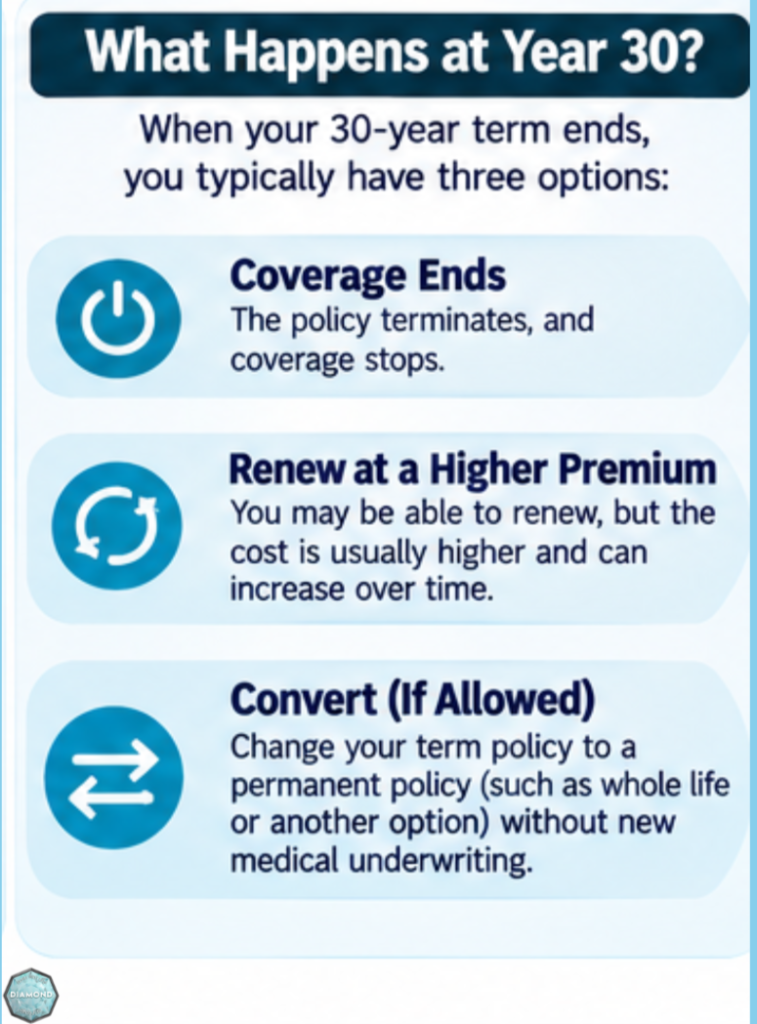
Another key point is what happens at the end of the term. Many term policies can be renewed, but renewal premiums often rise sharply and are based on your age at that point, so renewal is rarely the affordable answer 30 years later. If you think you may need coverage beyond the term, look at convertible term life insurance, which may let you convert part or all of the policy to permanent coverage without a new medical exam. Conversion windows and eligible policies vary by carrier, and the window often closes before the term ends, so check the conversion deadline before you buy. We help you think through timing on the front end so you are not relying on a renewal you cannot afford.
What age can you buy 30-year term life insurance?
Most carriers only offer 30-year term life insurance to applicants up to roughly age 50 to 55, and some stop earlier. The reason is simple: a 30-year policy issued at 55 would run to age 85, and insurers limit how far past that they will price a level premium. Maximum issue ages for each term length vary by carrier, so the cutoff for your age and health profile may be higher or lower than that range.
If you are in your 50s and searching for 30-year term life insurance, you still have options:
- Choose a shorter term: A 10-, 15-, or 20-year term is often available at older ages and may match your actual need better, since a mortgage or dependent years may not run another 30 years.
- Compare more carriers: Age cutoffs differ by company, so one carrier may issue a 30-year term where another will not.
- Consider permanent coverage: If you need protection that lasts for life, whole life or final expense insurance may be a better fit than a long term.
The younger and healthier you are when you apply, the more term lengths you are likely to have available, and the lower the premium you can lock in. Life Insured By Chris compares maximum issue ages and pricing across 30+ carriers so you can see which term lengths are actually available to you before you apply.
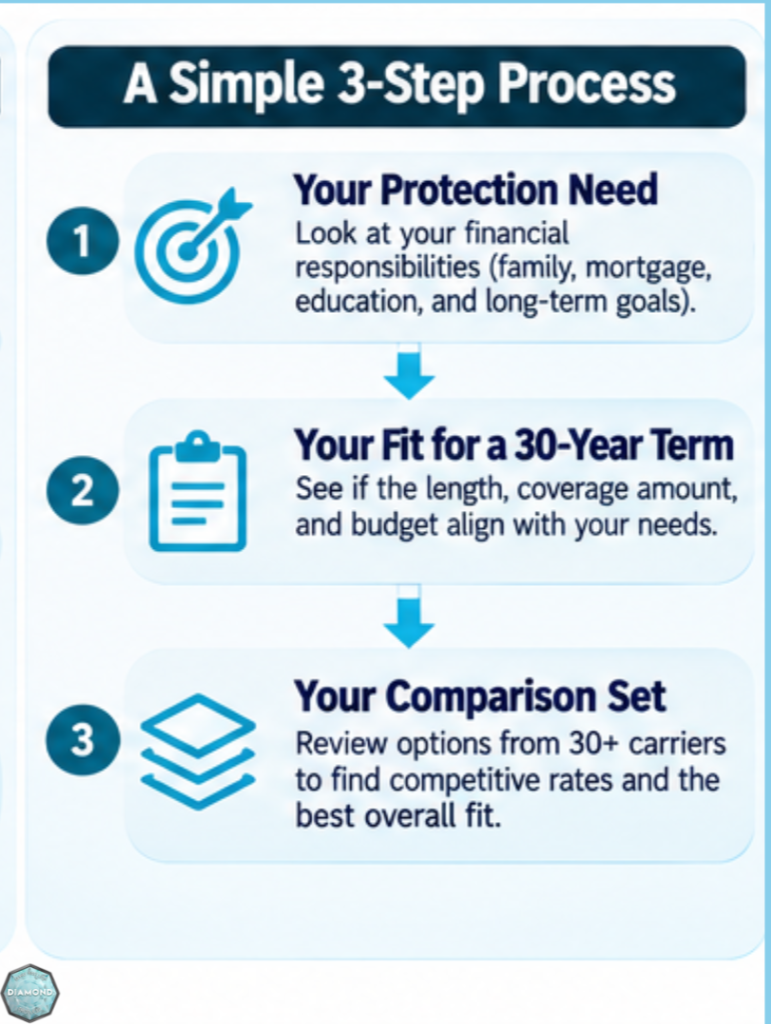
A simple 15-minute review to shop 30-year term life insurance with less guesswork
Life Insured By Chris keeps the process simple and pressure-free. You do not need to become an expert before you reach out, and you do not need to sort through dozens of carrier websites on your own.
Here is what the review typically focuses on:
- Your protection need: income replacement, mortgage balance, dependents, and long-term family goals.
- Your fit for 30-year term: age, health profile, budget, and whether a shorter or different policy type may make more sense.
- Your comparison set: quotes and carrier options available through our brokerage in the states where Life Insured By Chris is licensed.
That process is especially useful if you are buying life insurance for the first time. Life Insured By Chris turns the broad need for life insurance into a practical next step by helping you compare options you can actually apply for.
When a 30-year term policy is the right fit, and when another option may serve you better
A 30-year term is often the right fit when your need truly spans decades. If you want protection until children are grown, a long mortgage is paid down, or your household has had time to build assets, the added years can be worth the added premium.
But Life Insured By Chris will also tell you when a 30-year term may not be the best answer. If your main goal is final expenses, lifelong coverage, or a solution shaped around a different health or budget situation, we can also discuss whole life, final expense insurance, no medical exam options, guaranteed approval plans, or other solutions we offer.
That independence matters. Life Insured By Chris is not tied to one carrier or one product line, so the recommendation can stay centered on what you need to protect and what you can comfortably afford.
Talk through 30-year term life insurance with Life Insured By Chris
If you are weighing 30-year term life insurance, the next step does not need to be complicated. Start with a free 15-minute coverage review from Life Insured By Chris, and get a clearer answer on pricing, fit, and which carriers are worth considering for your situation.
When you are ready to protect your family for the long haul, reach out to Life Insured By Chris and compare 30-year term options with an independent broker who works for your decision, not a single carrier’s sales target.
| If you are ready to explore 30-year term life insurance, schedule your free 15-minute coverage review with Life Insured By Chris and compare plans that protect your family now while keeping future options open. → See My Coverage Options |