Cancer Survivor Life Insurance
If you have a history of cancer and need life insurance, the real question is usually not whether coverage exists. It is which carrier, policy type, and underwriting path make sense for your diagnosis history, current health, budget, and family goals.
Life Insured By Chris is an independent life insurance brokerage based in Washington, DC that helps cancer survivors compare coverage from 30+ top-rated carriers. We work with families, working professionals, veterans, seniors, first-time buyers, and people with health challenges across the United States, with active licensing in 20 states and a free 15-minute coverage review to help you start with clarity instead of guesswork.
Cancer survivor life insurance options matched to your medical history
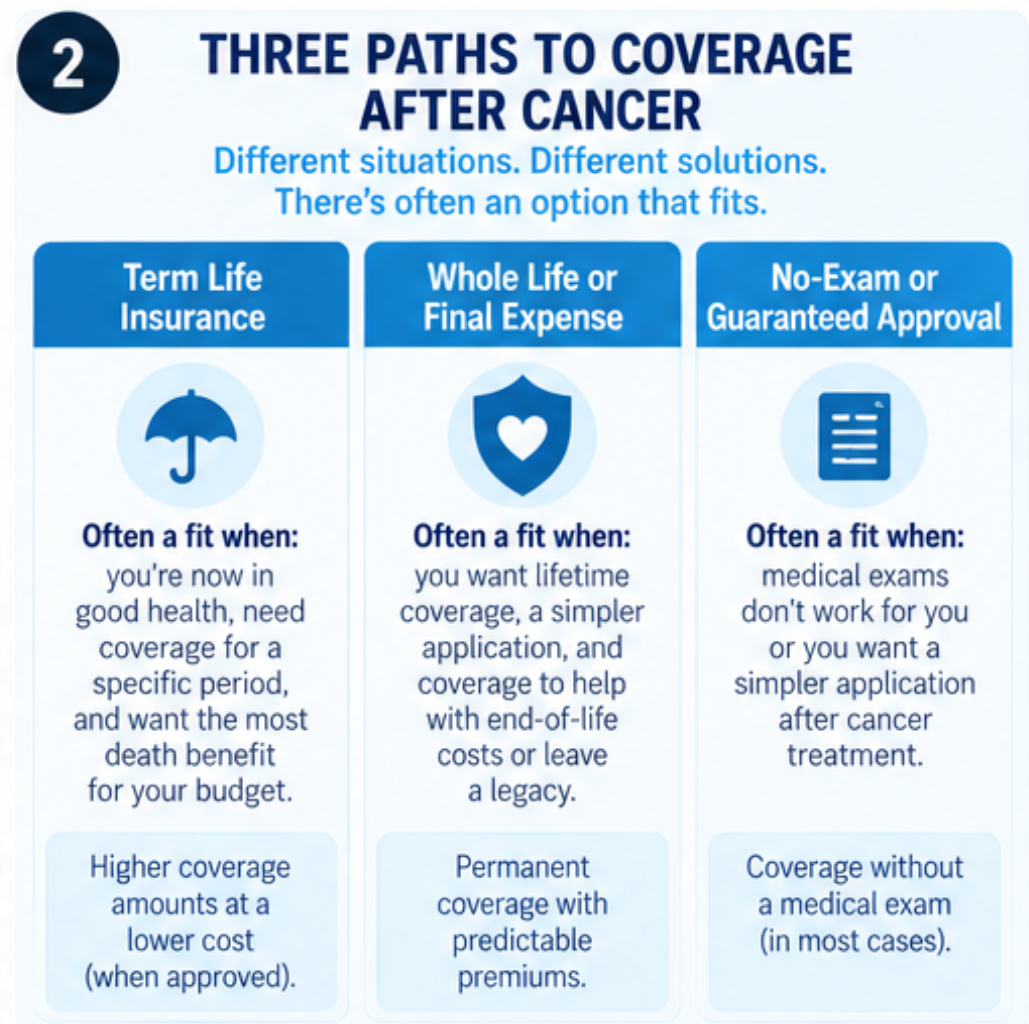
Life Insured By Chris helps cancer survivors shop life insurance by comparing multiple policy types, not by forcing you into one carrier’s rules. Depending on your situation, we may review term life insurance, whole life insurance, final expense insurance, no medical exam options, mortgage protection, guaranteed approval plans, and retirement-focused solutions if your goals go beyond basic death benefit coverage.
A cancer history does not automatically end your options, but it does change how carefully the application should be handled. We look at the details that matter to underwriting, such as cancer type, treatment dates, follow-up care, medications, time since diagnosis, and the amount of coverage you want, so you can focus on realistic options instead of applying blind.
"Life Insured By Chris compares 30+ top-rated carriers, giving cancer survivors more than one underwriting path to consider."
That matters because some applicants are best served by traditional underwriting, while others need a simplified or no-exam route to avoid wasted time and unnecessary declines. Our role is to help you understand the tradeoffs before you apply.
Here are some of the life insurance paths we commonly discuss with cancer survivors:
- Term life insurance: Often a fit when you want larger coverage for income replacement, children, or mortgage protection, and your medical profile supports it.
- Whole life or final expense insurance: Often considered when permanent coverage, burial costs, or easier qualification matters more than maximum face amount.
- No medical exam or guaranteed approval options: Useful when traditional underwriting is likely to be difficult, though pricing and coverage limits can differ significantly by carrier.
Why carrier selection matters for cancer survivor life insurance
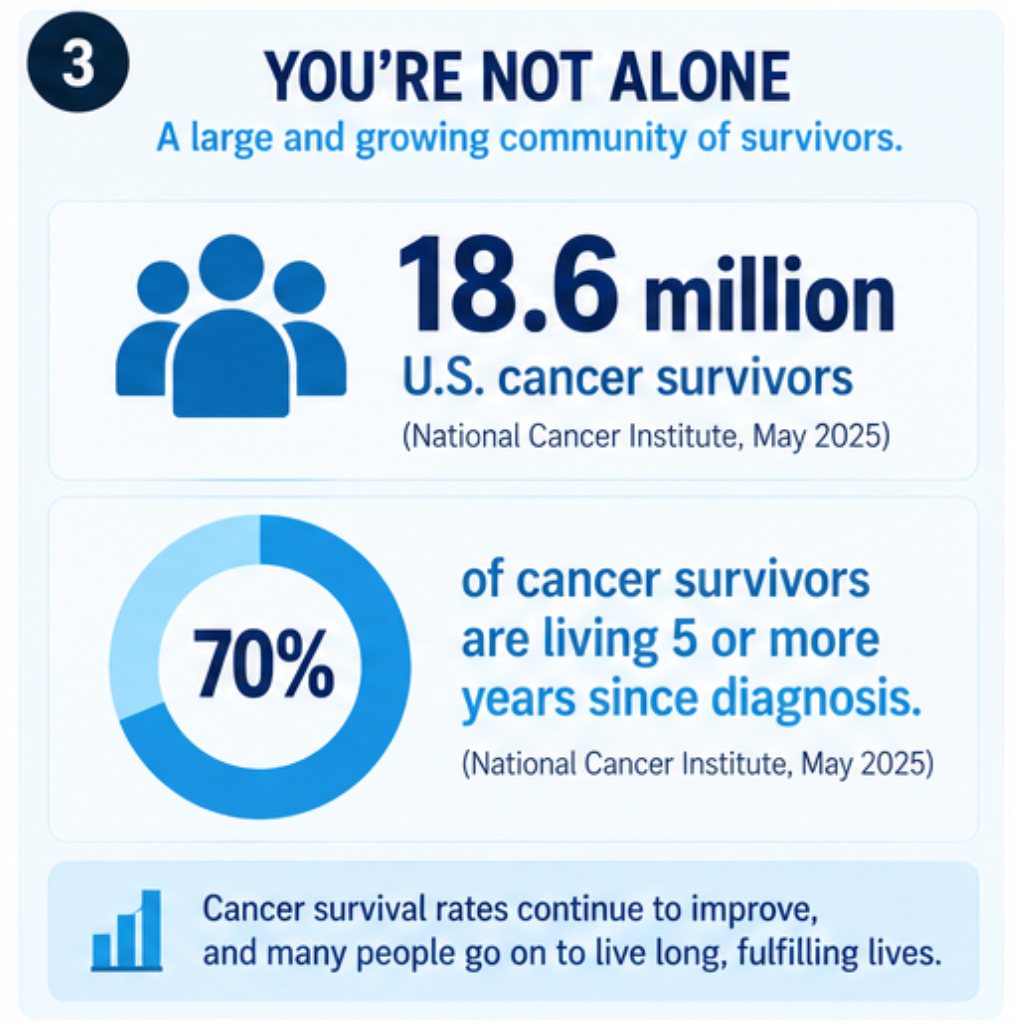
Cancer survivorship is not a niche issue. The National Cancer Institute estimated 18.6 million cancer survivors in the United States as of May 2025, and 70% had lived 5 or more years since diagnosis. Life Insured By Chris helps you approach life insurance as part of that real, growing survivor population, not as an automatic decline.
Published survivor research also shows why careful shopping matters. In one older long-term survivor cohort, 1.6% reported being denied life insurance, and 2.2% reported being denied loans or insurance due to cancer history, which confirms that coverage barriers do happen for some applicants.
"Life Insured By Chris serves a U.S. market that includes 18.6 million cancer survivors, where policy access and underwriting still vary by carrier."
Because carriers assess cancer history differently, the same applicant may see very different outcomes depending on where and how the case is submitted. An independent brokerage gives you a practical advantage here: we are not tied to one insurer’s cancer guidelines, one product shelf, or one underwriting philosophy.
Traditional, accelerated, and simplified underwriting for cancer survivors
Life Insured By Chris helps you compare more than policy names. We help you compare underwriting paths, which can have a major effect on speed, requirements, and the odds that a specific application route makes sense.
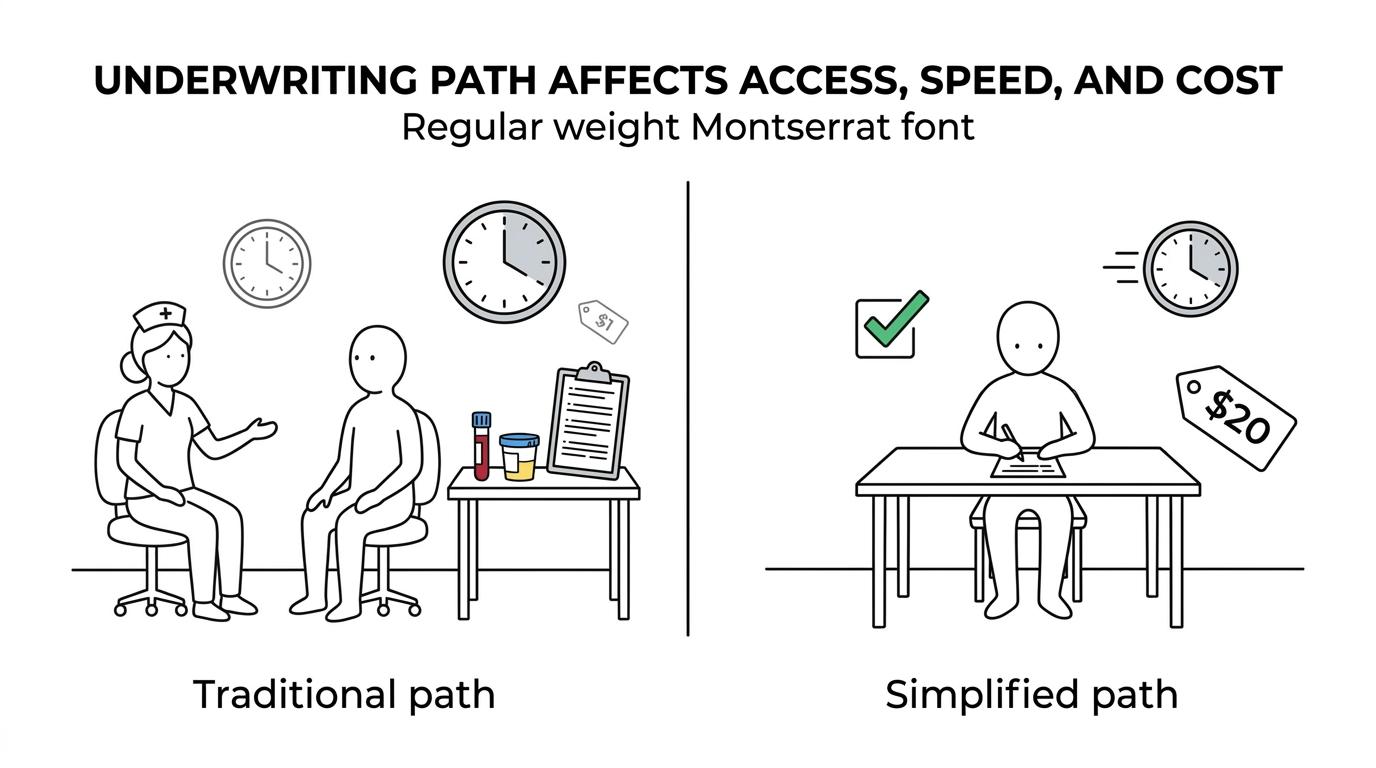
Traditional underwriting may require a physical exam and fluid testing, including blood, urine, or saliva. Some insurers also use accelerated underwriting, which can skip the exam and rely on external data and analytics, while simplified underwriting may use health questions instead of a medical exam, often with higher premiums in exchange for easier access.
"Life Insured By Chris can compare traditional, accelerated, and simplified underwriting across 30+ carriers so you are not locked into one application process."
For some cancer survivors, that flexibility is the difference between overpaying for the wrong product and finding a policy that fits both health history and budget. Life Insured By Chris can also review specific products on our platform, including Corebridge simplified issue whole life, which uses health questions instead of a traditional medical exam and is presented as a fit for some clients with serious health conditions, including cancer history.
What Life Insured By Chris reviews before recommending a policy
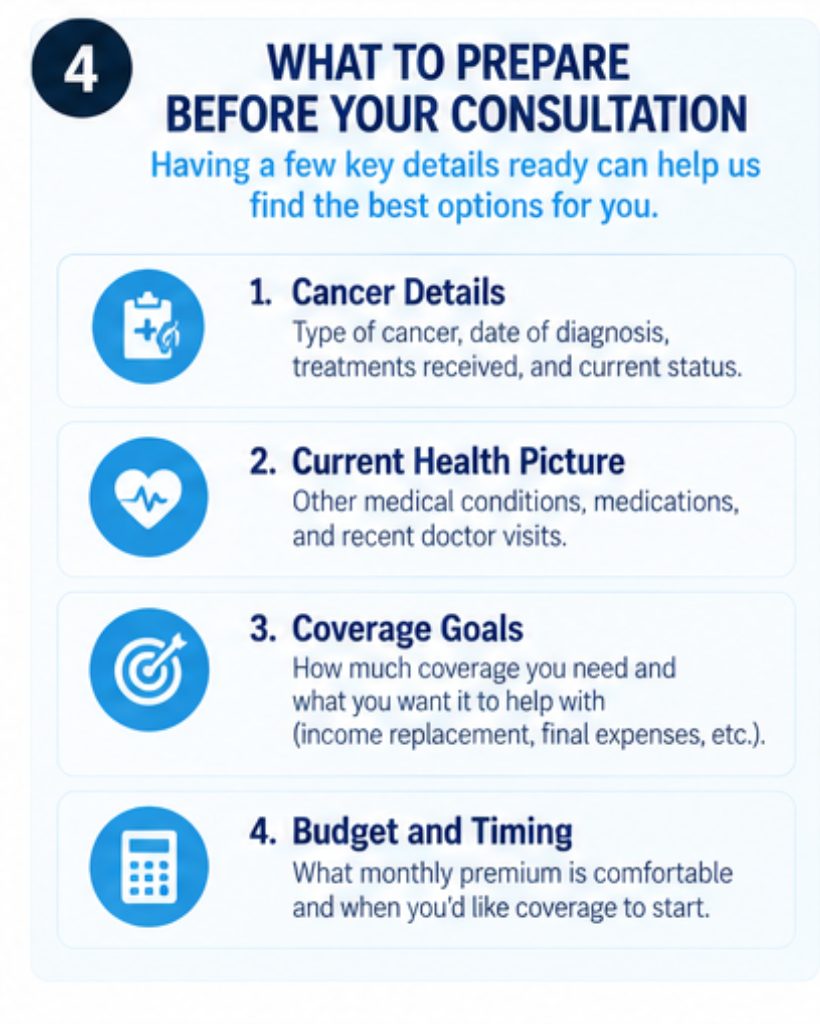
A useful quote comparison starts with the right facts. Life Insured By Chris uses your coverage review to understand the details that most affect eligibility and pricing.
We typically look at:
- Cancer details: Type of cancer, stage if relevant, date of diagnosis, treatment history, remission or follow-up status, and any recurrence history.
- Current health picture: Medications, other medical conditions, tobacco use, and whether a full medical exam is realistic or something you want to avoid.
- Coverage goals: How much protection you want, whether the priority is family income replacement, final expenses, mortgage protection, or leaving a legacy.
- Budget and timing: What premium range feels workable and whether you need to pursue traditional underwriting, simplified issue, or guaranteed approval more quickly.
This process helps you avoid two common mistakes: asking for the wrong amount of coverage or applying through a carrier that is unlikely to view your history favorably. When you know which path you are taking and why, the buying decision becomes much clearer.
Cancer survivor life insurance for families, veterans, seniors, and first-time buyers
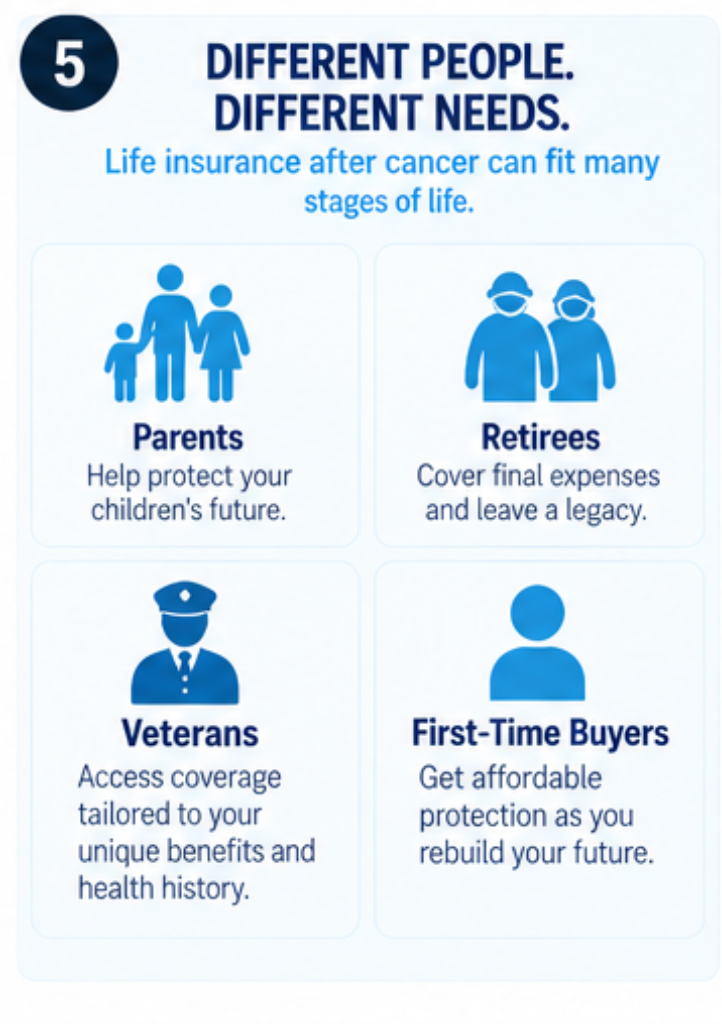
Life Insured By Chris serves a broad mix of clients because cancer history affects people at very different life stages. A parent may need term coverage for children and income protection. A retiree may care more about final expense planning. A veteran or health-challenged applicant may want straightforward guidance after running into confusing online quotes.
We are often a strong fit when:
- You were declined before: We can reassess the case and see whether a different carrier or a different underwriting path is more realistic.
- You want no-pressure guidance: Our free 15-minute coverage review is built to help you understand options before committing to an application.
- You need ongoing support: Life Insured By Chris stays available after purchase, so questions about your policy do not end the day you are approved.
If you have been told your cancer history makes coverage impossible, that is exactly when independent comparison becomes valuable. Some survivors will qualify for stronger options than expected, and others may need to start with simplified or guaranteed issue coverage first.
Why many cancer survivors prefer an independent life insurance broker
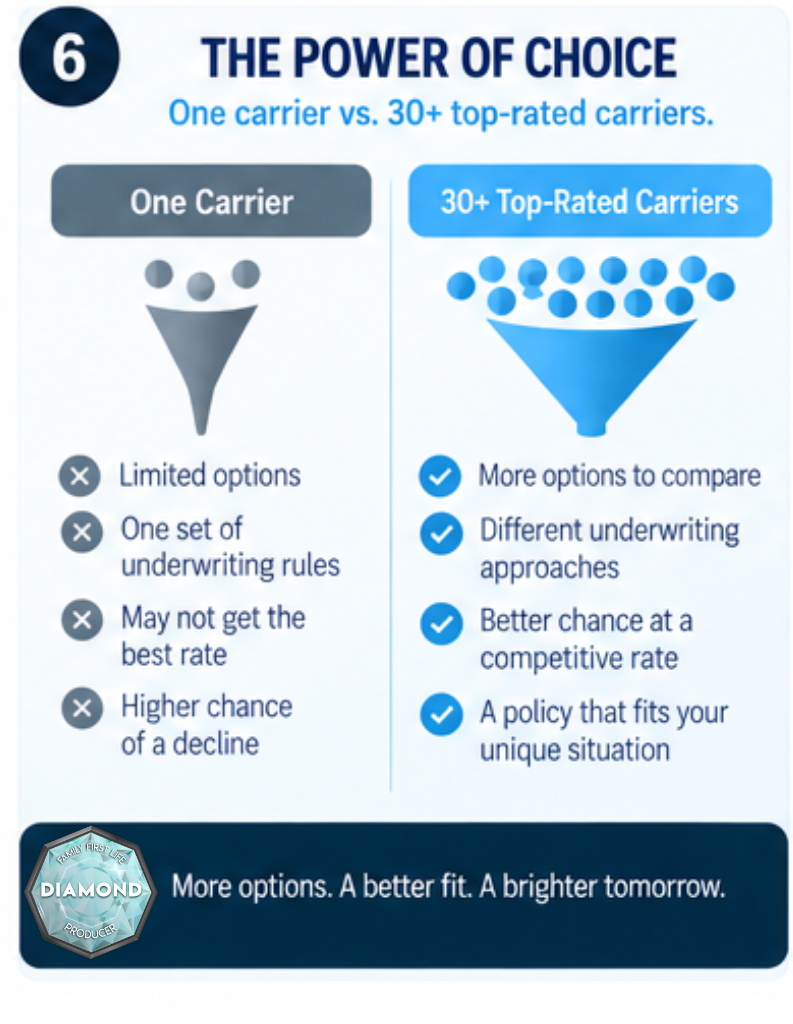
When you work with one insurer, you get one set of underwriting rules and one product menu. Life Insured By Chris gives you access to 30+ top-rated carriers, which creates room to compare how different companies handle cancer history, no-exam requests, permanent coverage, and budget-sensitive applications.
That independence also makes pricing conversations more productive. We can help you weigh the practical tradeoff between a lower-cost policy that requires fuller underwriting and a simplified path that may be easier to access but more expensive. For cancer survivors, that is often the key buying decision.
Life Insured By Chris is licensed in 20 states and built around personal, pressure-free guidance. If you want a fast quote, a second opinion after a decline, or a realistic path to coverage after cancer, we help you move forward with more context and less guesswork.
Start with a free 15-minute cancer survivor coverage review
If you want life insurance after cancer, start with a conversation that is built around your actual history, not a generic quote form. Life Insured By Chris will review your situation, explain which policy types are worth considering, and help you compare the most relevant next steps for your budget and goals.
Reach out now to schedule your free 15-minute coverage review and see which cancer survivor life insurance options may fit you.
| Ready to compare your options? Reach out to Life Insured By Chris to review your cancer survivor life insurance options and get matched with coverage that fits your timeline, your budget, and the people you want to protect. → Visit: www.lifeinsuredbychris.com/schedule-a-consultation |



)