Life Insurance with High Blood Pressure: Options
If you have high blood pressure, buying life insurance can feel uncertain fast. You may be wondering whether your readings, medication, or recent diagnosis will raise your rate, limit your options, or stop you from qualifying at all.
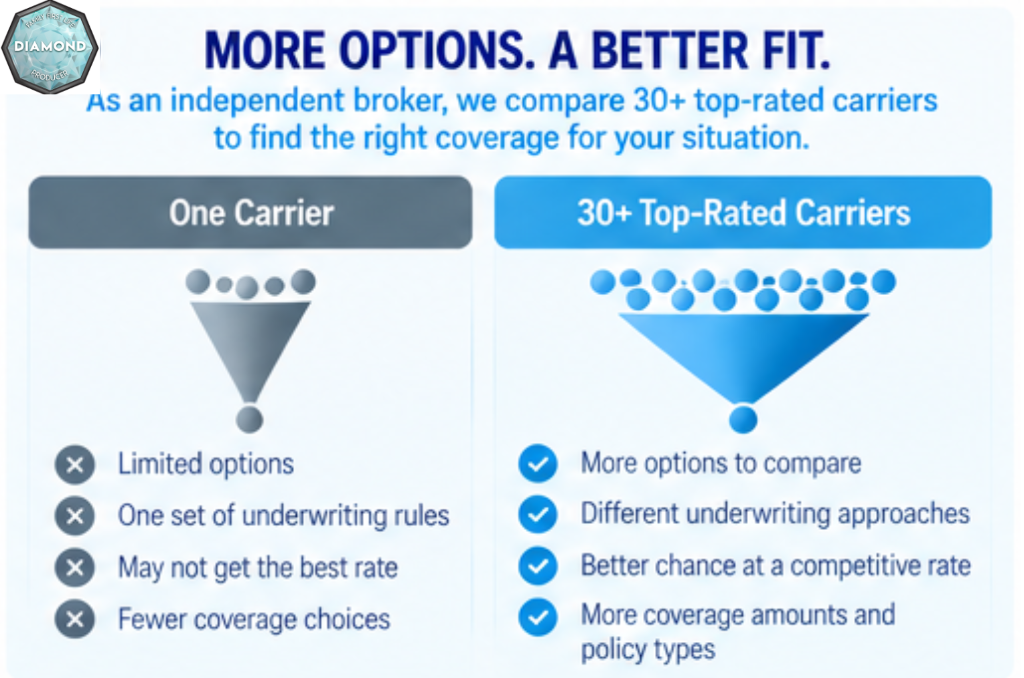
Life Insured By Chris helps you compare high blood pressure life insurance options across 30+ top-rated carriers, so you are not stuck with one company’s underwriting rules. As an independent brokerage licensed in 20 states and based in Washington, DC, we review your health profile, budget, and coverage goals, then help you apply for the policy type that makes the most sense for your situation.
Controlled hypertension does not automatically rule out coverage. What matters is how your blood pressure is currently managed, how long you have had it, whether you take medication, and whether there are related issues like heart disease, kidney concerns, diabetes, tobacco use, or recent hospitalizations.
High blood pressure life insurance quotes from Life Insured By Chris
Life Insured By Chris helps families, working professionals, veterans, seniors, first-time buyers, and health-challenged applicants shop for life insurance when high blood pressure is part of the picture. We can help you compare term life, whole life, final expense, no medical exam coverage, mortgage protection, guaranteed approval plans, indexed universal life, and fixed index annuities when appropriate.
Because we are independent, we can look at how different carriers treat hypertension instead of steering you toward a single company’s product line. That matters because insurers do not all look at blood pressure readings, prescriptions, build, or health history the same way.
Life Insured By Chris compares life insurance options from 30+ top-rated carriers, giving you more paths when one insurer is stricter about hypertension than another.
Many people come to us after assuming they will be declined. In reality, applicants with controlled high blood pressure may still qualify through traditional underwriting or accelerated underwriting, while others may be better served by simplified or guaranteed issue options.
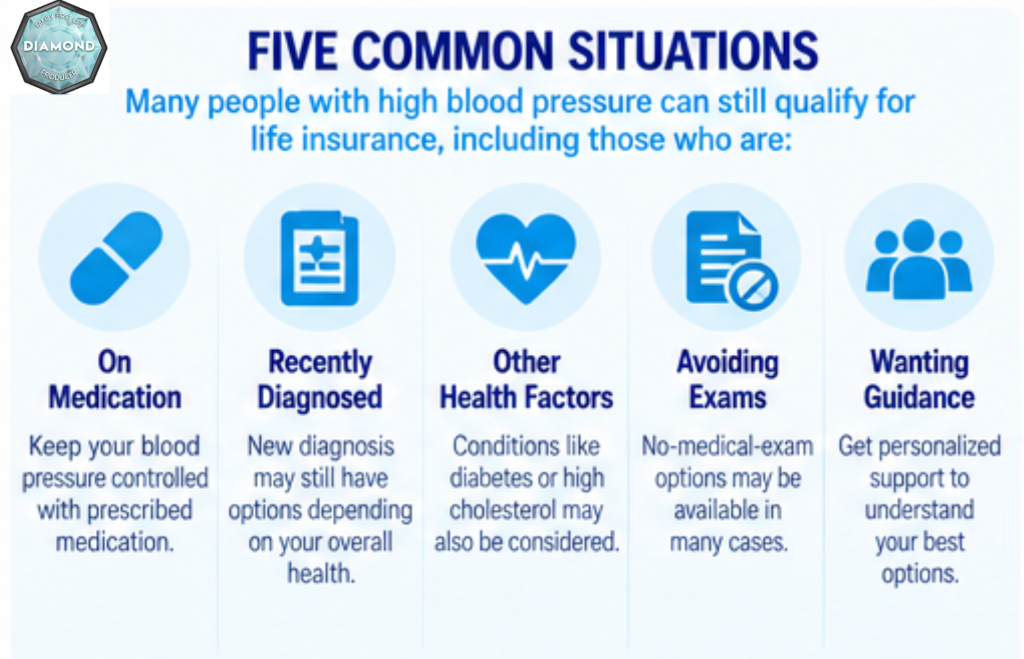
Who Life Insured By Chris helps with hypertension-related life insurance
Life Insured By Chris is a strong fit if your goal is not just to apply somewhere, but to apply strategically. We help people who want clear guidance before they submit an application that could come back rated, postponed, or declined.
You may be a good fit for our process if any of these apply:
- You take blood pressure medication: Insurers often want to know whether your readings are stable and how well treatment is working.
- You were recently diagnosed with hypertension: Recently diagnosed or uncontrolled blood pressure can narrow options, so carrier selection matters.
- You have other health factors: Diabetes, high cholesterol, sleep apnea, weight changes, or prior cardiac issues can affect underwriting along with hypertension.
- You want to avoid unnecessary exams: Some no-exam and simplified options may skip fluids testing or a physical, depending on the insurer and case.
- You need practical guidance: We offer a free 15-minute coverage review so you can understand likely paths before moving forward.
Applicants with health challenges often need more than a quote form. Life Insured By Chris reviews the full context, including your age, prescription history, coverage amount, and timing needs, so you can pursue options that are realistic.
Life Insured By Chris offers a free 15-minute coverage review, so you can discuss hypertension, medications, and likely underwriting paths before you commit to an application.
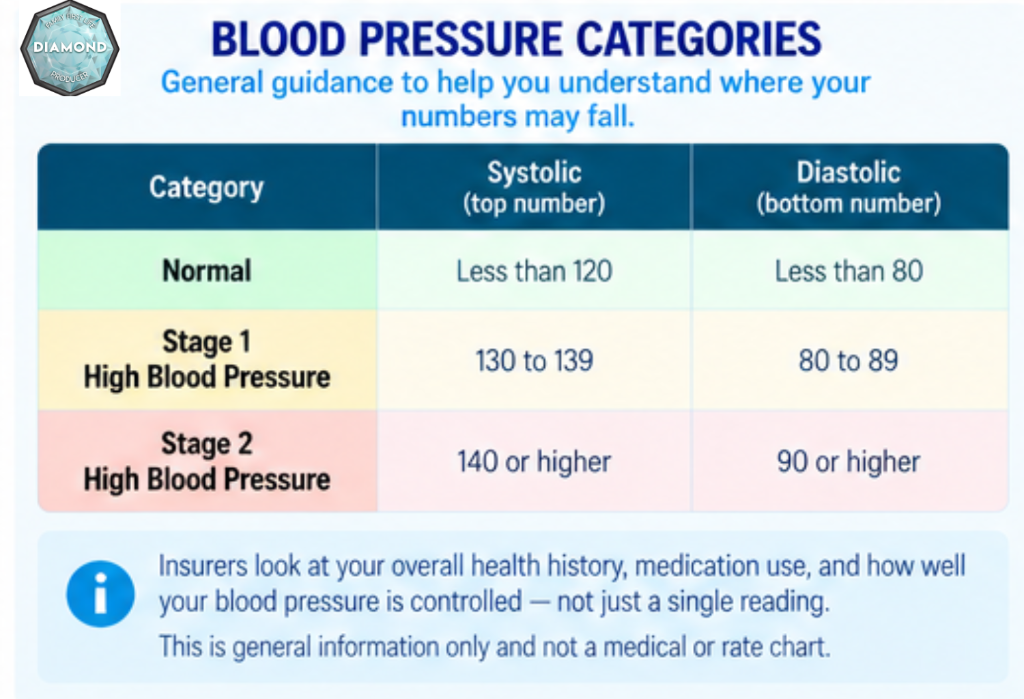
How insurers usually look at high blood pressure during life insurance underwriting
Current U.S. guidance uses 130/80 mm Hg as the hypertension threshold, and that is also a common cutoff insurers reference in underwriting. Stage 1 hypertension starts at 130 to 139 systolic or 80 to 89 diastolic, while stage 2 starts at 140 systolic or 90 diastolic.
That does not mean every reading above 130/80 leads to the same result.
Life Insured By Chris helps you prepare for the bigger underwriting question, which is whether your blood pressure is controlled, documented, and isolated, or whether it appears uncontrolled and tied to broader cardiovascular risk.
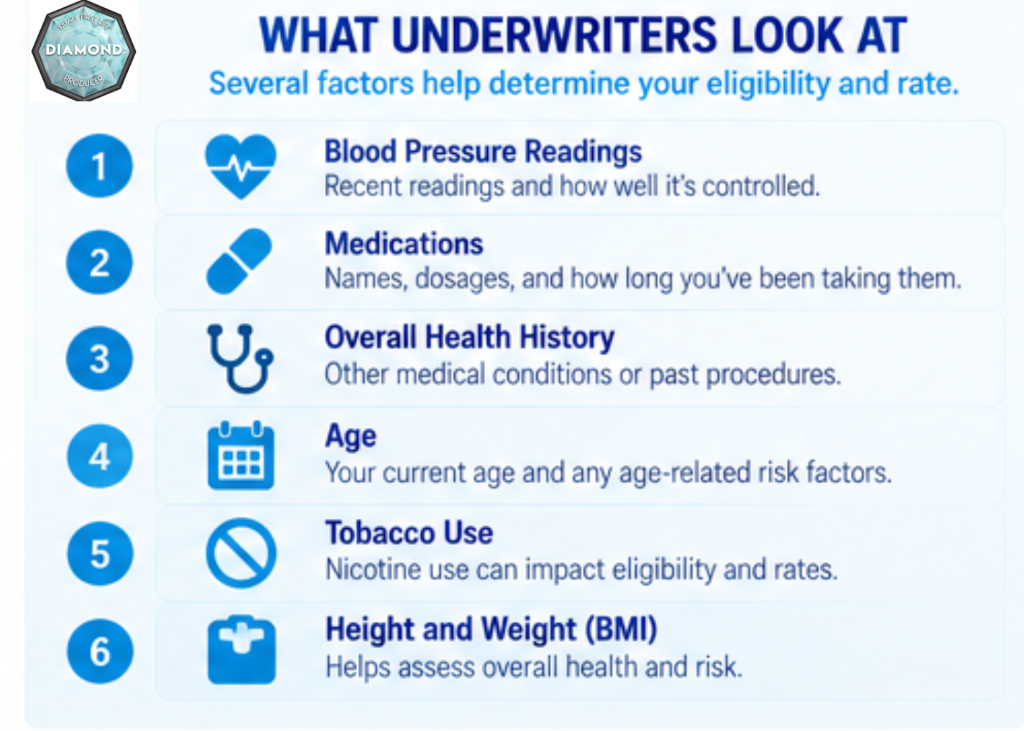
Insurers may review details such as:
- Recent blood pressure readings: Especially whether they show stable control over time.
- Medications: What you take, how many medications you take, and whether prescriptions suggest control.
- Height and weight: Applications may ask for current build and recent weight changes.
- Family and personal medical history: Some applications ask about family history that includes high blood pressure.
- Insurance history: Prior declines, modifications, or rated offers can affect strategy.
- Related conditions: Kidney disease, stroke history, heart disease, diabetes, or nicotine use can change pricing and eligibility.
Traditional underwriting can require extensive medical information and may include a physical exam plus blood, urine, or saliva testing. Accelerated underwriting may skip the exam and use external data and modeling to shorten the process from several weeks to as little as a few hours in some cases.
Life Insured By Chris can help you weigh traditional, accelerated, and no-exam paths when hypertension affects how quickly you need coverage and how much medical review you want to face.
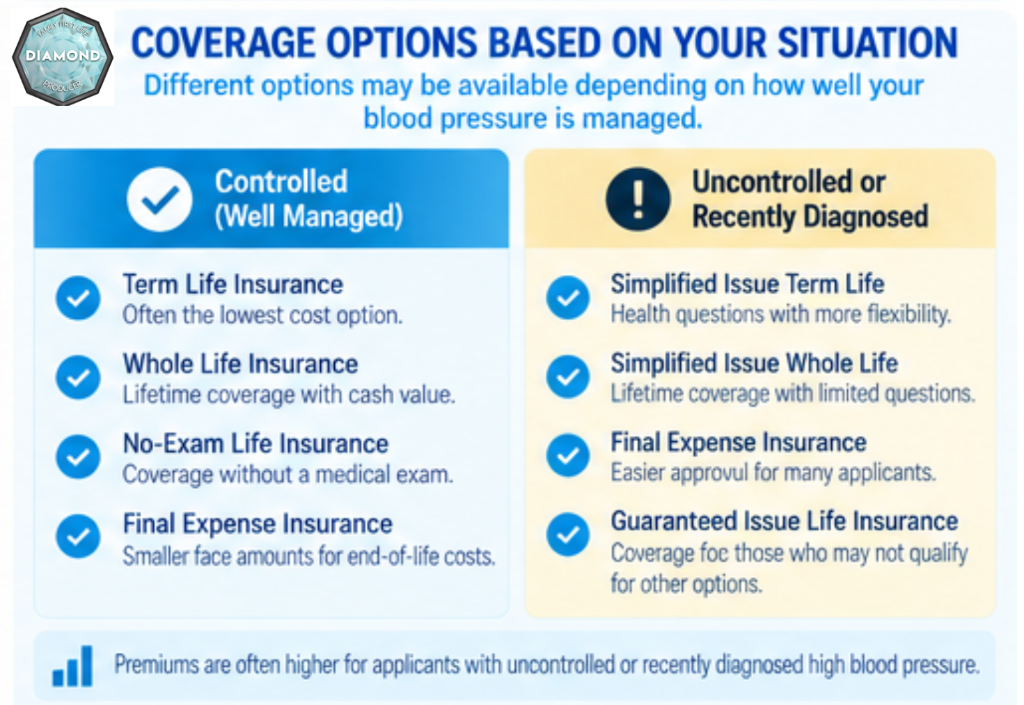
Life insurance options when you have controlled or uncontrolled hypertension
Life Insured By Chris matches the product to your health profile instead of forcing every applicant into the same route. That can make a meaningful difference if your blood pressure is well managed, recently elevated, or paired with other medical issues.
If your blood pressure is controlled, your options may include:
- Term life insurance: Often a strong fit if you want affordable coverage for income replacement, mortgage protection, or family needs.
- Whole life insurance: Useful when permanent coverage and fixed premiums matter more than getting the lowest possible initial cost.
- No medical exam life insurance: A practical option if you want to avoid lab work or speed up the process.
- Final expense insurance: Often helpful for seniors or applicants with moderate health issues who want smaller permanent coverage amounts.
If your blood pressure is uncontrolled, recently diagnosed, or tied to other health concerns, Life Insured By Chris may still help you explore simplified underwriting, final expense, or guaranteed issue plans. These policies can open a path to coverage when fully underwritten options are limited, though premiums are often higher and coverage amounts may be lower.
We are also direct about what cannot be promised. No broker can guarantee approval or a specific rate before the insurer completes underwriting, and we will not tell you otherwise.
What Life Insured By Chris improves for applicants with high blood pressure
The biggest improvement is not just access to quotes. It is getting to the right quotes faster, with fewer avoidable surprises.
Life Insured By Chris helps reduce wasted applications by identifying which carriers may view your hypertension history more favorably based on your control, medication use, and related conditions. That can help you avoid applying first to a carrier that is likely to rate you too aggressively or postpone a decision.
We also make the process clearer. Instead of leaving you to guess whether an exam, APS request, prescription check, or no-exam route makes sense, we explain what information may matter and why.
For many clients, that means:
- clearer expectations about pricing and approval odds.
- a better match between policy type and health profile.
- faster movement when accelerated or no-exam options are viable.
- ongoing support after the policy is issued, not just at the point of sale.
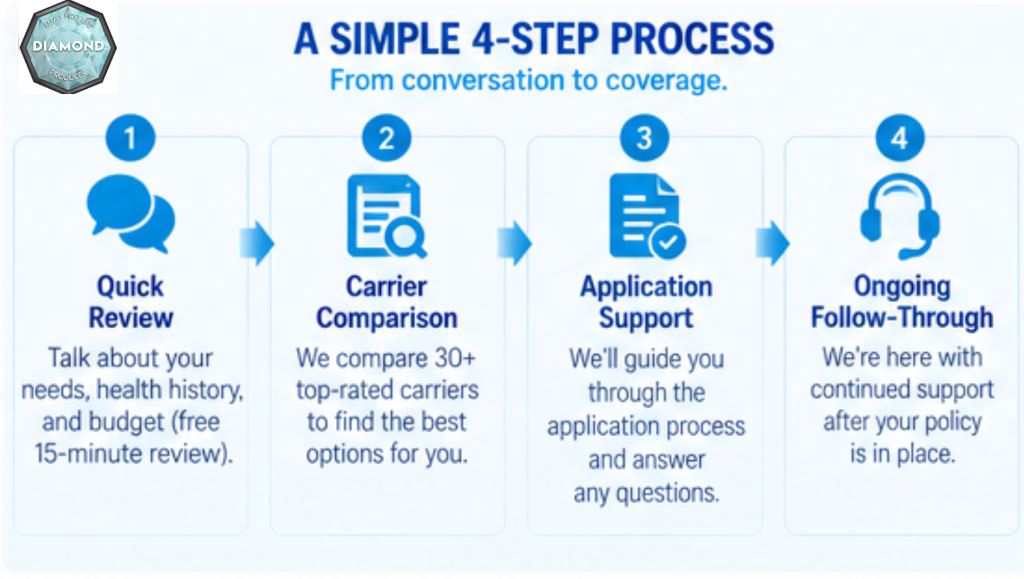
A simpler application process for high blood pressure life insurance
Life Insured By Chris keeps the process personal and pressure-free. We start with your coverage goal, then review the health and underwriting details that are most likely to affect your options.
A typical process looks like this:
- Quick review: We discuss your age, coverage goal, blood pressure history, medications, and any related health conditions.
- Carrier comparison: Life Insured By Chris compares available options across 30+ carriers and identifies the most suitable application path.
- Application support: We help you understand whether the case is more likely to fit traditional underwriting, accelerated underwriting, no-exam, or guaranteed issue.
- Ongoing follow-through: If the carrier asks for more information, we help you respond and stay with you through issue and policy support.
That structure matters when you have hypertension because details can change the outcome. A stable history on medication is not viewed the same way as uncontrolled severe readings, and a long-managed condition is not viewed the same way as a recent diagnosis with additional symptoms.
Why Life Insured By Chris is different for veterans, seniors, and health-challenged applicants
Life Insured By Chris is built for people who need choices, not a one-size-fits-all pitch. Our independent model matters most when underwriting is nuanced, and high blood pressure is one of those areas.
We have a special focus on veterans and health-challenged applicants, which means we understand that many buyers come in with more than one underwriting variable. If you are comparing coverage while managing hypertension alongside service-related health concerns, retirement planning goals, or budget limits, we can help you sort through those tradeoffs clearly.
Because we are licensed in 20 states, we can serve clients across a wide area while still keeping the experience personal. You get direct guidance, not a generic quote engine and no follow-up context.
When Life Insured By Chris is the right fit for your high blood pressure case
Life Insured By Chris is likely the right choice if you want someone to compare multiple carriers, explain the tradeoffs honestly, and help you choose the best application strategy before you apply.
We are especially useful when:
- your blood pressure is controlled but you want the most competitive rate available.
- you have had a recent medication change and want to know whether to apply now or wait.
- you want no-exam life insurance if possible.
- you have been declined, rated, or postponed before.
- you need final expense or guaranteed issue because traditional underwriting is not ideal.
- you want support after the policy is placed, not just during the sale.
If you only want a single captive carrier quote, we may not be the best fit. If you want independent guidance and broader market comparison, Life Insured By Chris is built for exactly that.
High blood pressure is common. The CDC reports that 48.1% of U.S. adults, or 119.9 million people, have high blood pressure. That scale is one reason carrier choice matters so much. Insurers see these cases every day, but they do not all price or assess them the same way.
Start with a free 15-minute high blood pressure life insurance review
If you want life insurance and you have high blood pressure, the next step is simple. Schedule a free 15-minute coverage review with Life Insured By Chris, and we will help you understand which policy types and underwriting paths are most realistic for your health profile, budget, and timeline.
You do not need to guess whether controlled hypertension will block coverage or whether a no-exam option is available. Talk with Life Insured By Chris, compare your options, and move toward coverage with a plan that fits your situation.
| Ready to compare your options? Reach out to Life Insured By Chris to review your high blood pressure life insurance options and get matched with coverage that fits your timeline, your budget, and the people you want to protect. → Visit: www.lifeinsuredbychris.com/schedule-a-consultation |