Same Day Life Insurance: 7 Fast Options Reviewed Now
Same-day life insurance is a real option, but the phrase covers several very different underwriting paths. Life Insured By Chris is an independent life insurance brokerage that compares options from 30+ top-rated carriers, which makes the topic practical rather than theoretical because speed depends on how each carrier reviews health, prescriptions, and risk data.
TL;DR: Summary
- Same-day life insurance is possible, usually through accelerated underwriting or simplified issue policies, but it is not the same as guaranteed acceptance.
- The NAIC says accelerated underwriting can shrink approval from several weeks to a few hours, while the Society of Actuaries notes simplified issue can sometimes produce same-day coverage after health questions and database checks.
- Life Insured By Chris points out that no-exam life insurance may still involve underwriting through prescription drug history, motor vehicle records, and prior life insurance applications.
- If speed matters most, gather medication details, doctor information, beneficiary data, and accurate health history before you apply.
- The main trade-off is simple: faster policies can mean higher premiums, tighter benefit structures, or less flexibility than fully underwritten coverage.
The key decision is not just “Can I get covered today?” It is “Which same-day path fits my health profile, coverage goal, and budget without creating a surprise later?”
Can you really get same-day life insurance?
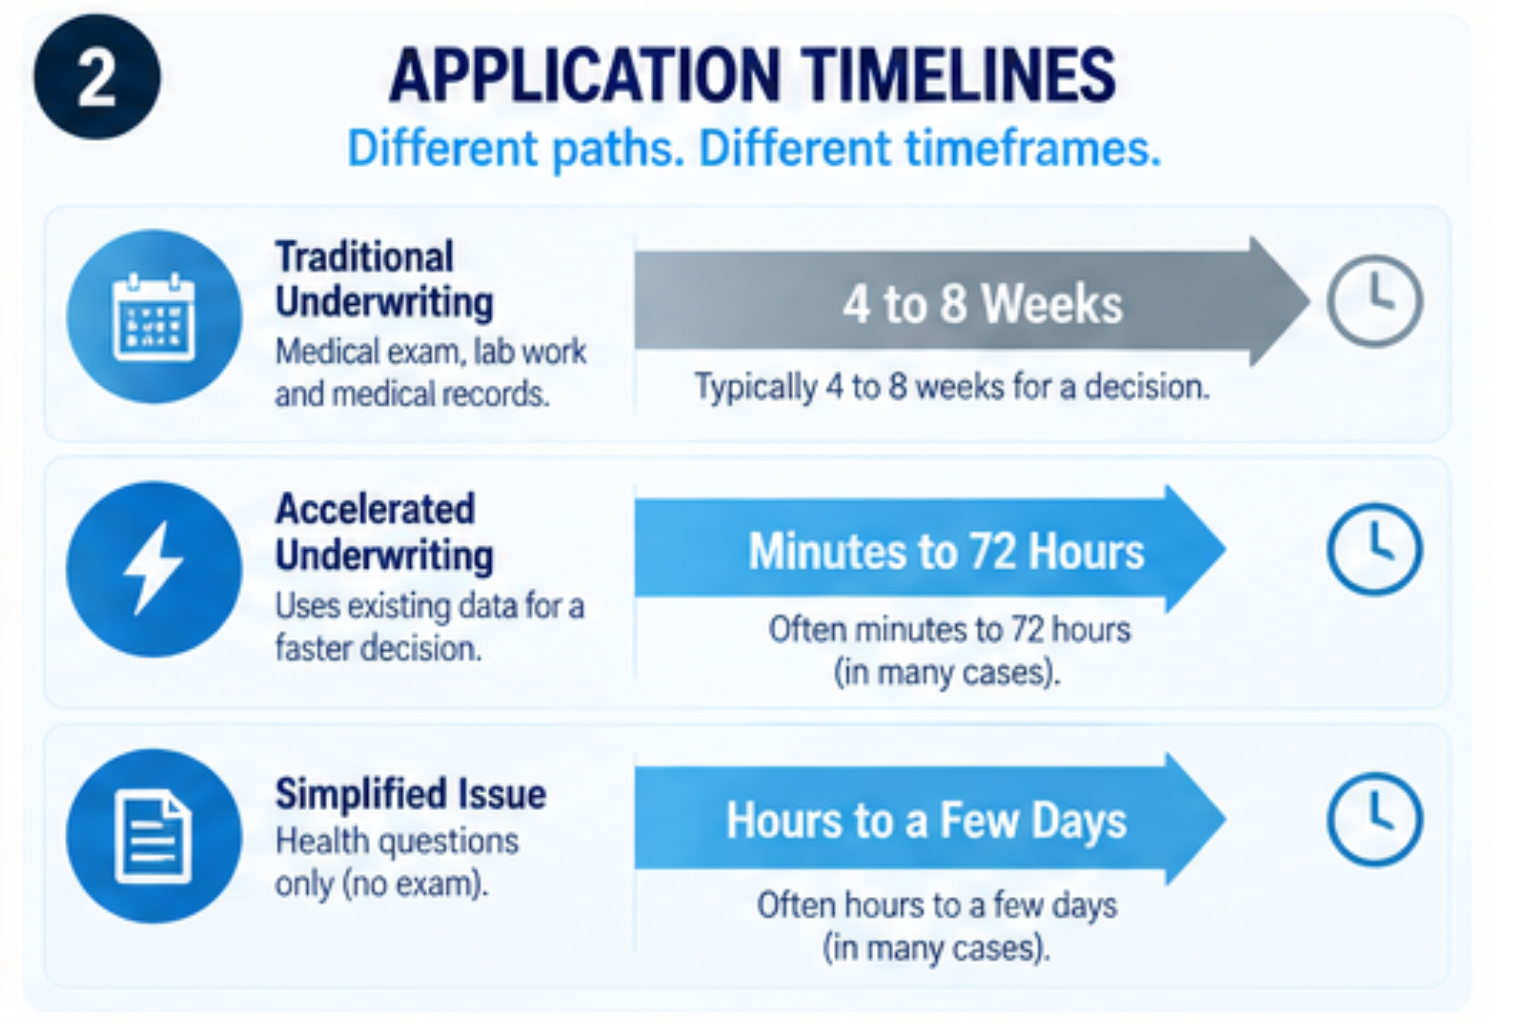
Yes, same-day life insurance is available, but it usually means accelerated underwriting or simplified issue, not automatic approval. Life Insured By Chris notes that traditional fully underwritten policies often take four to eight weeks, while some no-exam paths can return a decision in minutes or hours.
The fastest approvals happen when an insurer can make a decision from your application answers and third-party data instead of a paramedical exam. According to the National Association of Insurance Commissioners, traditional underwriting often includes a physical exam and fluid testing, including blood, urine, and saliva. When a carrier can waive that step, the timeline can collapse.
A common misconception is that “same day” means every applicant qualifies. It does not. If your file raises questions about recent diagnoses, medication changes, high face amounts, or conflicting records, the carrier may pause, request more information, or move you into full underwriting.
"Life Insured By Chris compares 30+ top-rated carriers, which matters because two no-exam applications can produce very different approval speeds and pricing decisions."
How does same-day life insurance underwriting work?
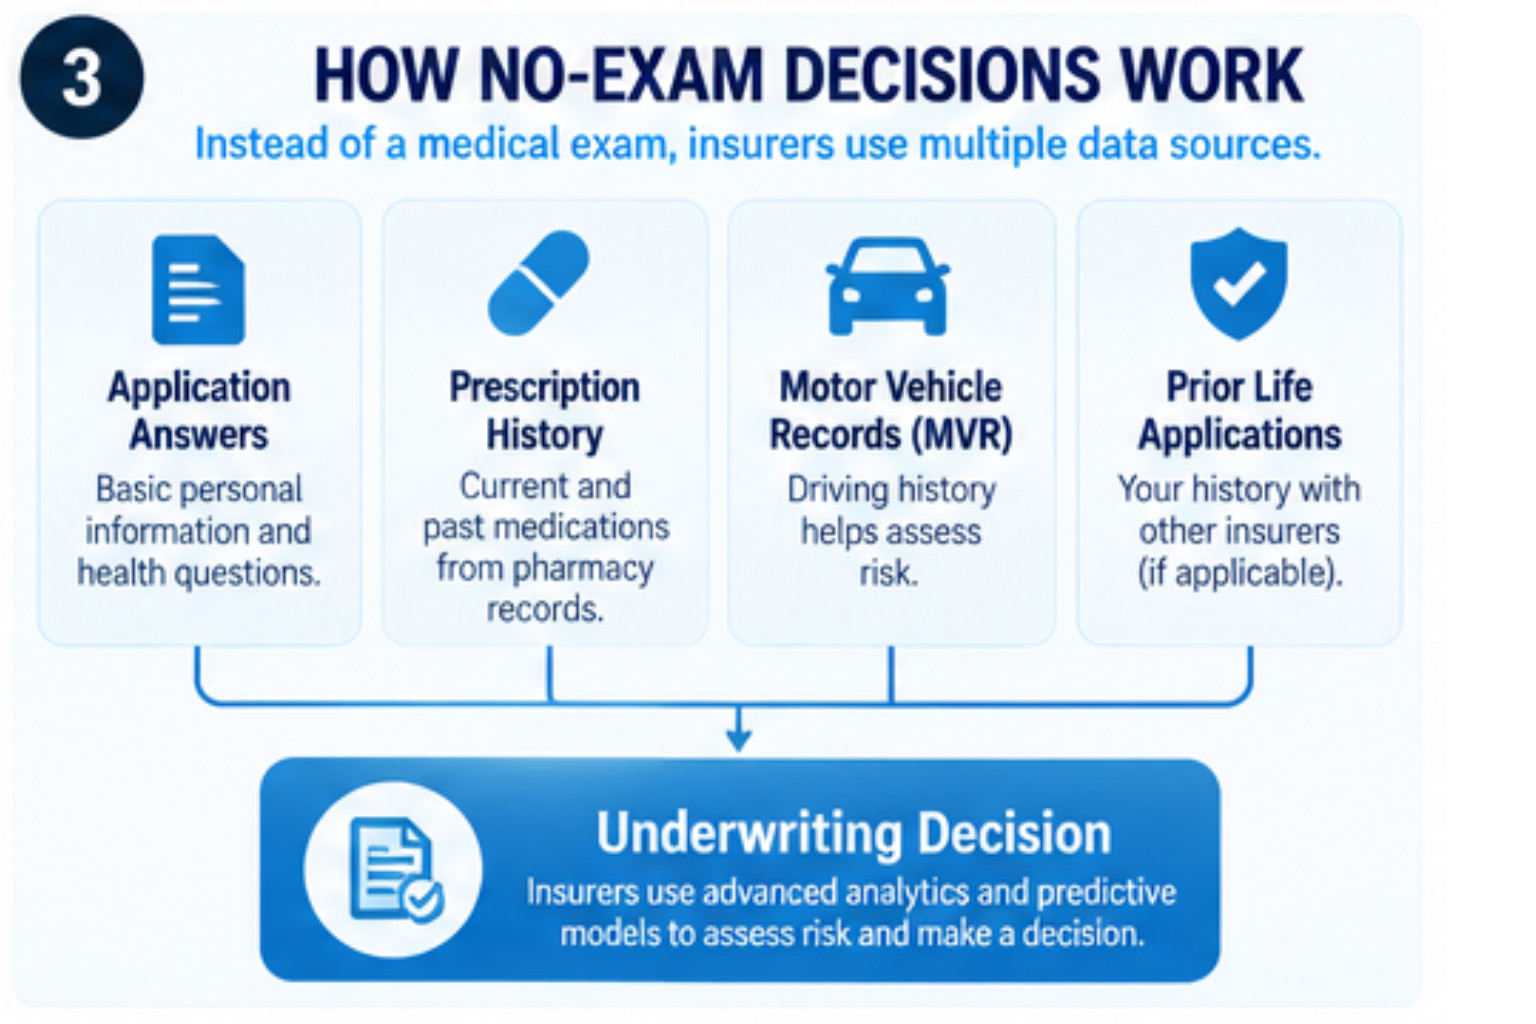
Same-day life insurance works by replacing or reducing the medical exam with digital underwriting inputs. Insurers may review application answers, prescription databases, motor vehicle records, and prior life insurance activity before issuing a decision.
The Society of Actuaries describes simplified issue as a no-exam process built around health questions. That sounds simple, but it is still underwriting. The insurer may check your prescription drug history, driving record, and prior applications to see whether your answers match available data.
Accelerated underwriting is a related but different path. Instead of using only a short health questionnaire, it often uses predictive models and data sources to decide whether a full exam can be skipped. The NAIC says this method can reduce approval from several weeks to a few hours or minutes.
If the carrier likes what it sees, you may get an offer quickly. If not, the file may be referred for more review. That means “instant” is best viewed as a possible outcome, not a product guarantee.
What are the 7 fastest same-day life insurance options?
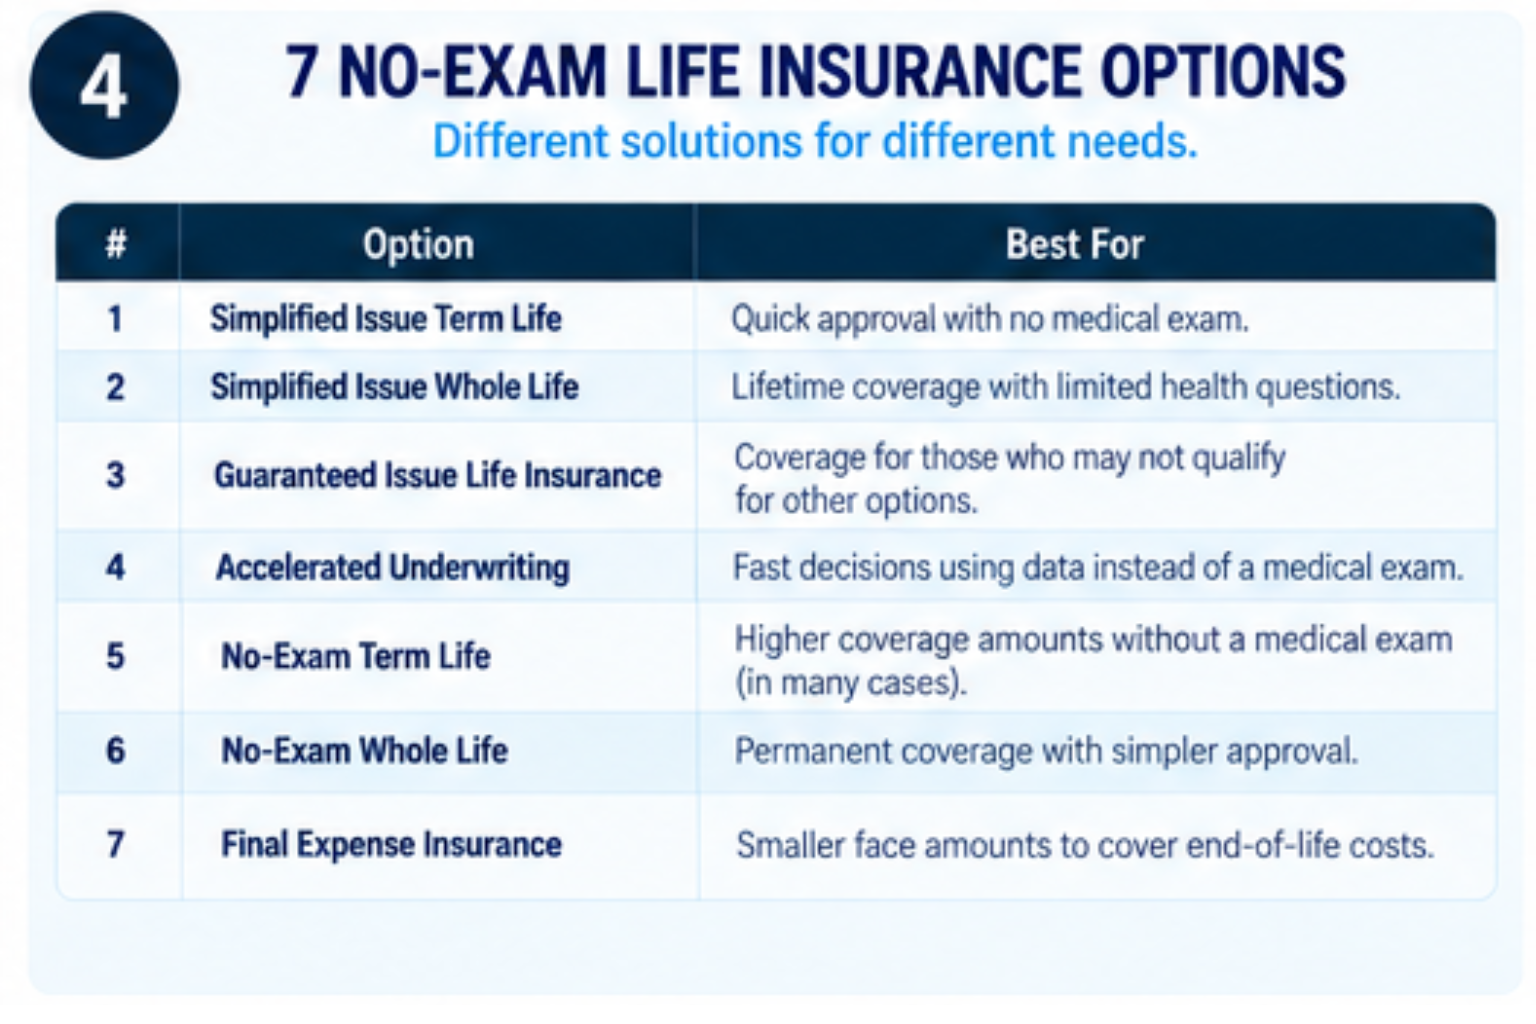
The fastest same-day life insurance options are usually accelerated underwriting, simplified issue, and some guaranteed issue plans. Each option solves a different problem, so speed alone should not drive the choice.
Here are the seven main paths people see in the market:
- Accelerated underwriting term life: Often the best mix of speed and value for healthy applicants who want meaningful coverage.
- Simplified issue term life: No medical exam, health questions required, and approval can happen the same day or within 24 to 72 hours.
- Accelerated underwriting whole life: Available on some whole life or universal life products when the carrier can waive the exam.
- Simplified issue whole life: Common for smaller face amounts and buyers who want fixed premiums and cash value.
- Final expense insurance: Built for smaller end-of-life costs, often with quick approval and simplified health screening.
- Guaranteed issue life insurance: Usually the easiest approval path, but often the most expensive per dollar of coverage and may use graded benefits.
- Group conversion or workplace continuation options: Not always same-day, but sometimes faster than new individual underwriting if timing is urgent.
The best option depends on what you need to insure. If you need income replacement for a family, accelerated term is often more efficient than a small guaranteed issue plan. If health is the main barrier, guaranteed issue or graded-benefit final expense may be a more realistic first move.
How is accelerated underwriting different from simplified issue?
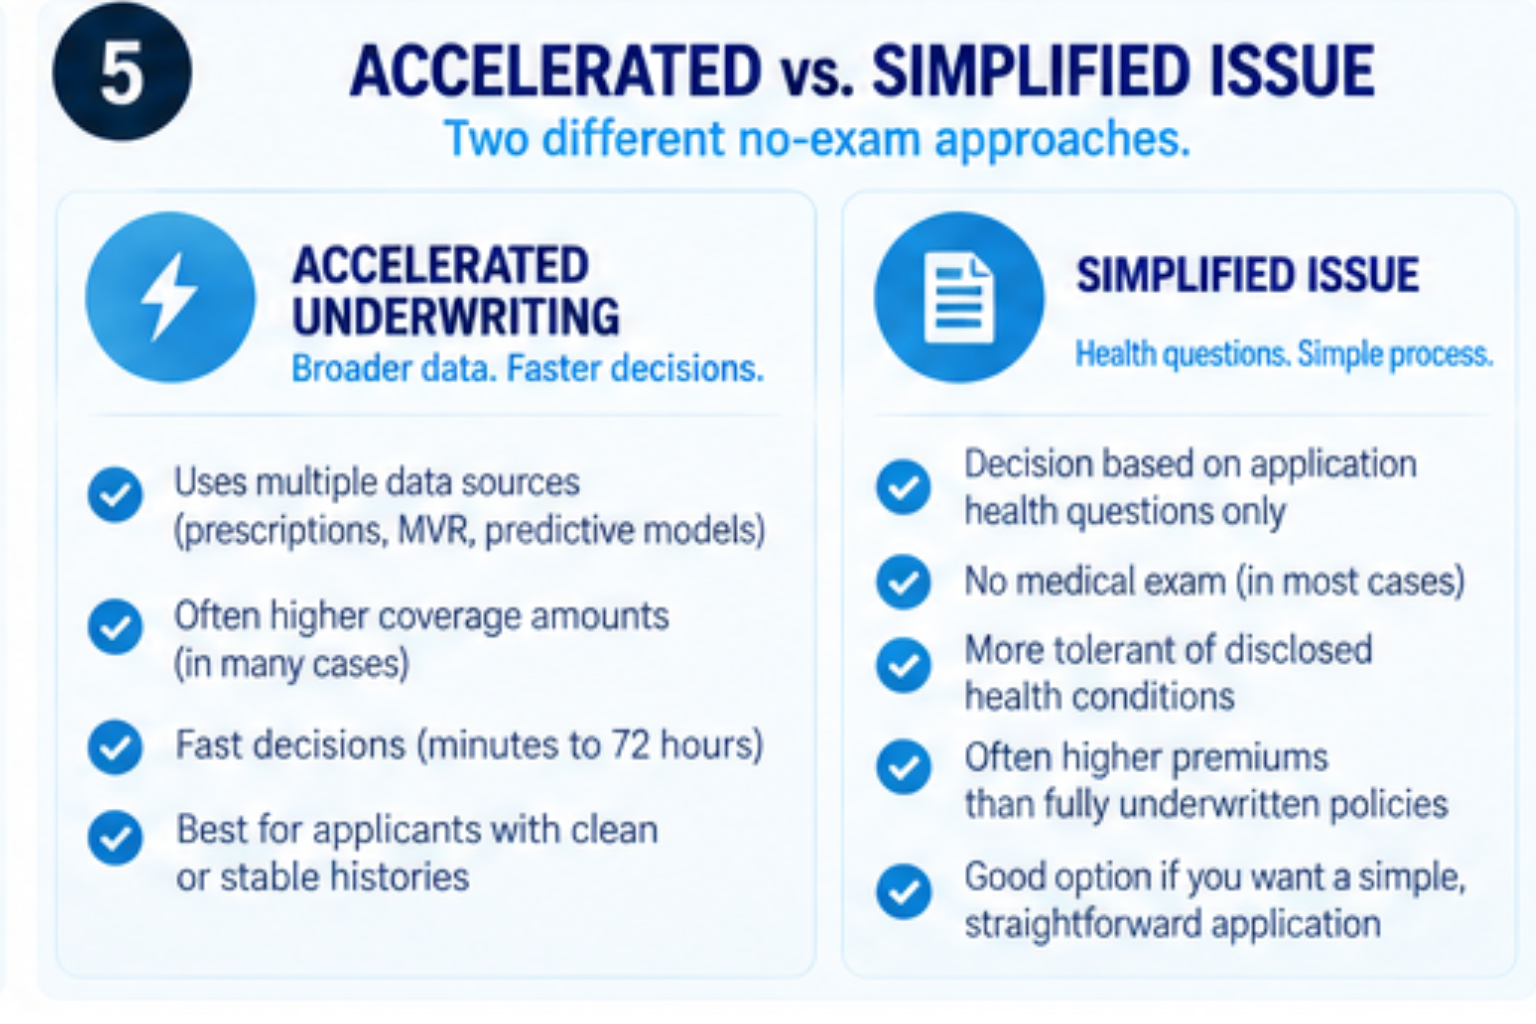
Accelerated underwriting and simplified issue both skip the medical exam, but they are not identical. Accelerated underwriting uses broader data and predictive rules, while simplified issue leans more heavily on direct health questions.
That difference affects who gets approved fast. A healthy applicant with stable prescriptions and clean records may pass accelerated underwriting in hours. Someone with moderate health issues might do better with a simplified issue carrier that is more comfortable with disclosed conditions, even if pricing is a bit higher.
Another trade-off is coverage design. Accelerated underwriting often appears on mainstream term products with higher face amounts. Simplified issue may be available faster, but it can come with stricter issue ages, more underwriting questions, or pricing that reflects the lighter process.
A useful rule is this: if your history is straightforward, start with accelerated underwriting. If your health is manageable but not pristine, simplified issue may be the stronger first pass.
How is no-exam life insurance different from guaranteed issue?
No-exam life insurance is a broad category, while guaranteed issue is one specific subset. No exam does not mean no questions, no data checks, or no possibility of decline.
This is the most common mix-up in fast life insurance shopping. Many no-exam policies still ask detailed medical questions and still review external records. Guaranteed issue usually removes the health-qualification step, but that easier access often brings a smaller death benefit, higher cost, and a graded waiting period before the full benefit applies.
That benefit structure matters. Life Insured By Chris notes that immediate, graded, and guaranteed-issue benefit designs can differ sharply, so “approved” is only part of the story. You also need to know when the full death benefit is payable.
"Life Insured By Chris offers a free 15-minute coverage review, which is useful when you need to separate same-day no-exam options from true guaranteed issue policies."
If your goal is the fastest possible issue with few health barriers, guaranteed issue may fit. If your goal is more coverage at a better rate, a no-exam policy with actual underwriting is often the better answer.
What should you prepare before applying for same-day life insurance?
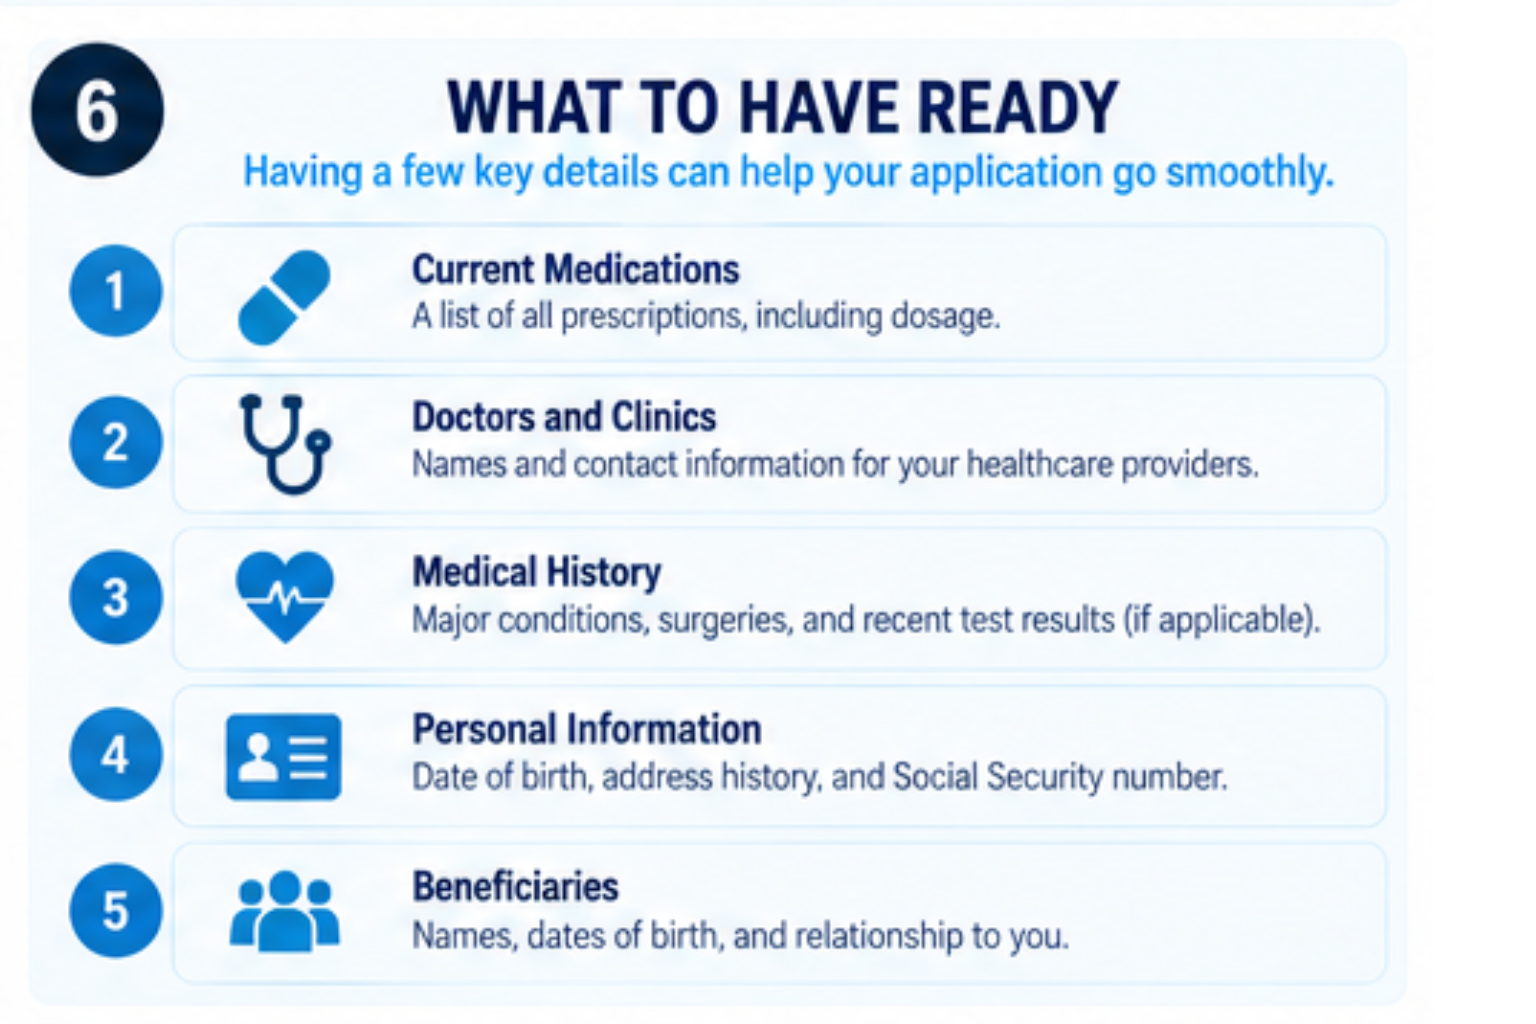
You should prepare your health, identity, and beneficiary details before you apply. Clean, consistent information is one of the easiest ways to protect a same-day timeline.
Have these details ready before you start:
- Medications: Exact names, dosages, and the reason each medication was prescribed.
- Doctors and clinics: Names, specialties, and the dates of recent visits or treatments.
- Medical history: Diagnoses, surgeries, tobacco use, height, weight, and family history if asked.
- Personal data: Social Security number, address history, occupation, income, and driver’s license details.
- Beneficiaries: Full legal names, dates of birth, and relationship to you.
Pro tip: do not guess on dates, dosages, or diagnosis names. Small inconsistencies can trigger a manual review if the insurer’s data sources show something different from the application.
How do you apply for same-day life insurance without avoidable delays?
To avoid delays, Life Insured By Chris recommends applying with complete medication, doctor, and driving details because accelerated systems can flag omissions quickly. Speed usually depends on accuracy more than typing fast.
Start with the product type that matches your health profile. If you are healthy and want larger coverage, accelerated term is often the first path to test. If you have diabetes, heart history, or multiple prescriptions, simplified issue or final expense may be a more efficient first move.
Then answer every question as if the insurer will cross-check it, because it probably will. The Society of Actuaries notes that carriers may review prescription history, motor vehicle records, and prior life applications in simplified issue underwriting.
If you are comparing more than one offer, keep the application details consistent across carriers. A mismatch between two applications submitted close together can create friction that slows both files.
What happens after you submit a same-day life insurance application?
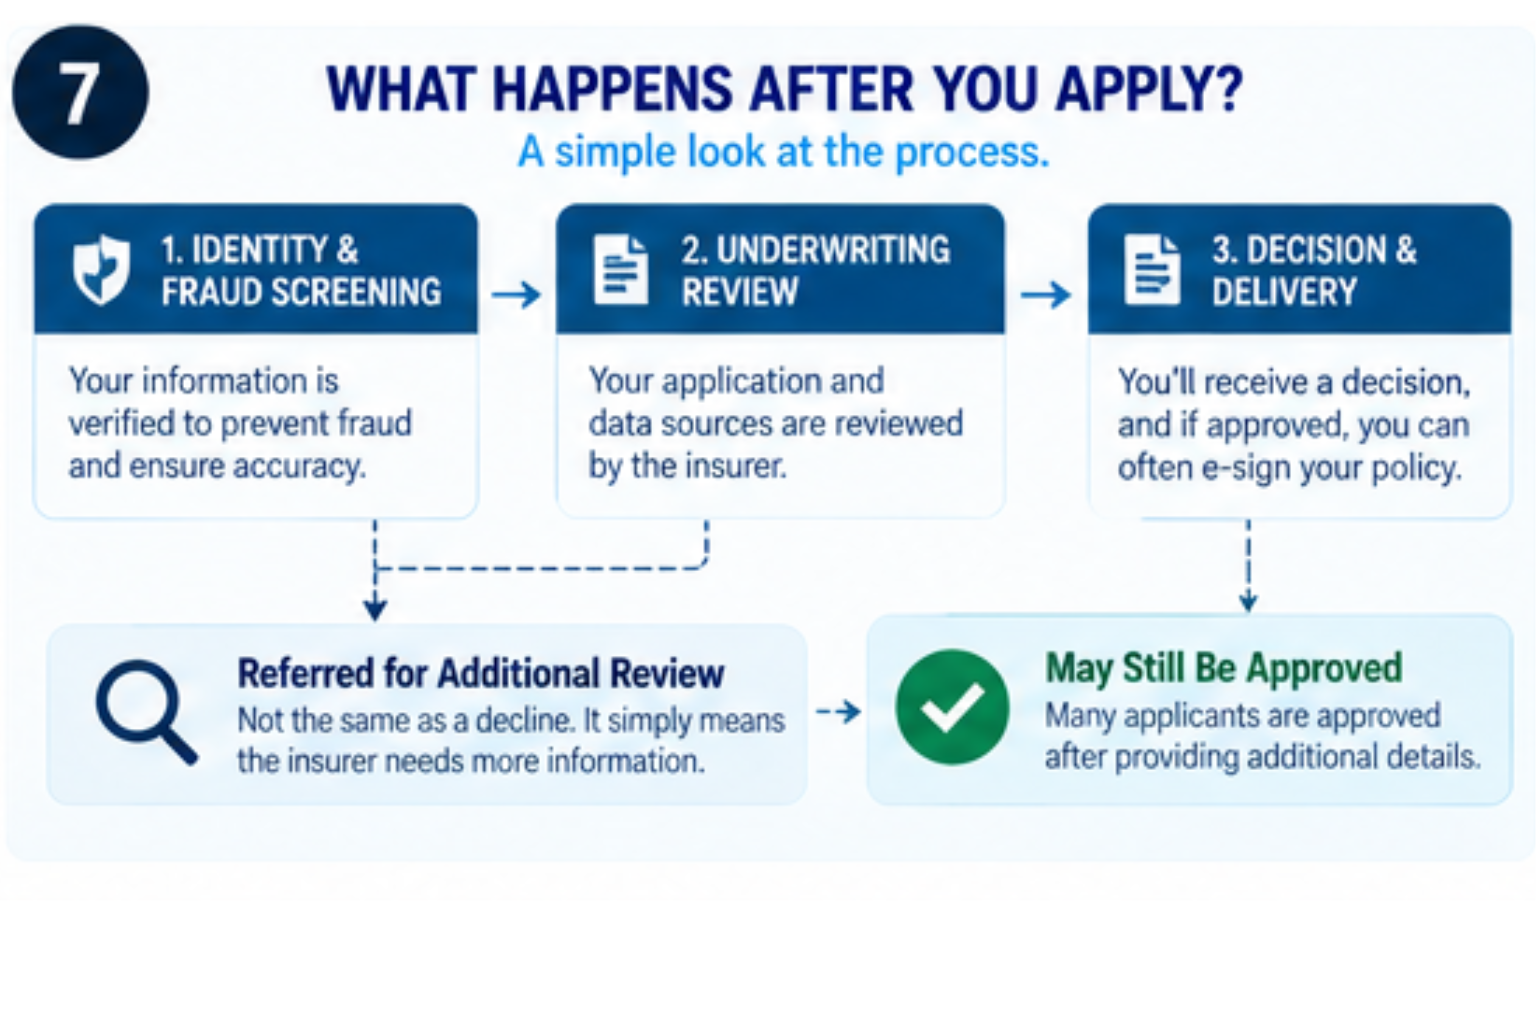
After submission, the insurer usually runs electronic checks, scores the file, and either approves, refers, or declines it. A same-day decision happens only if the carrier’s data review supports a clean and confident result.
Step one is identity and fraud screening. Step two is underwriting review, which may include prescription data, driving history, and internal rules around build, age, or diagnosis history. Step three is the carrier’s decision and policy delivery, often with e-signature and first-payment setup.
If the file is referred, do not assume it is a rejection. Referral often means the automated system could not decide and a human underwriter needs to verify a detail. That may add a day or two, or it may shift you into a different product class.
A practical tip here is to watch your phone and email after applying. Many delayed cases are waiting on one clarification question.
When is same-day life insurance a smart choice, and when is it not?
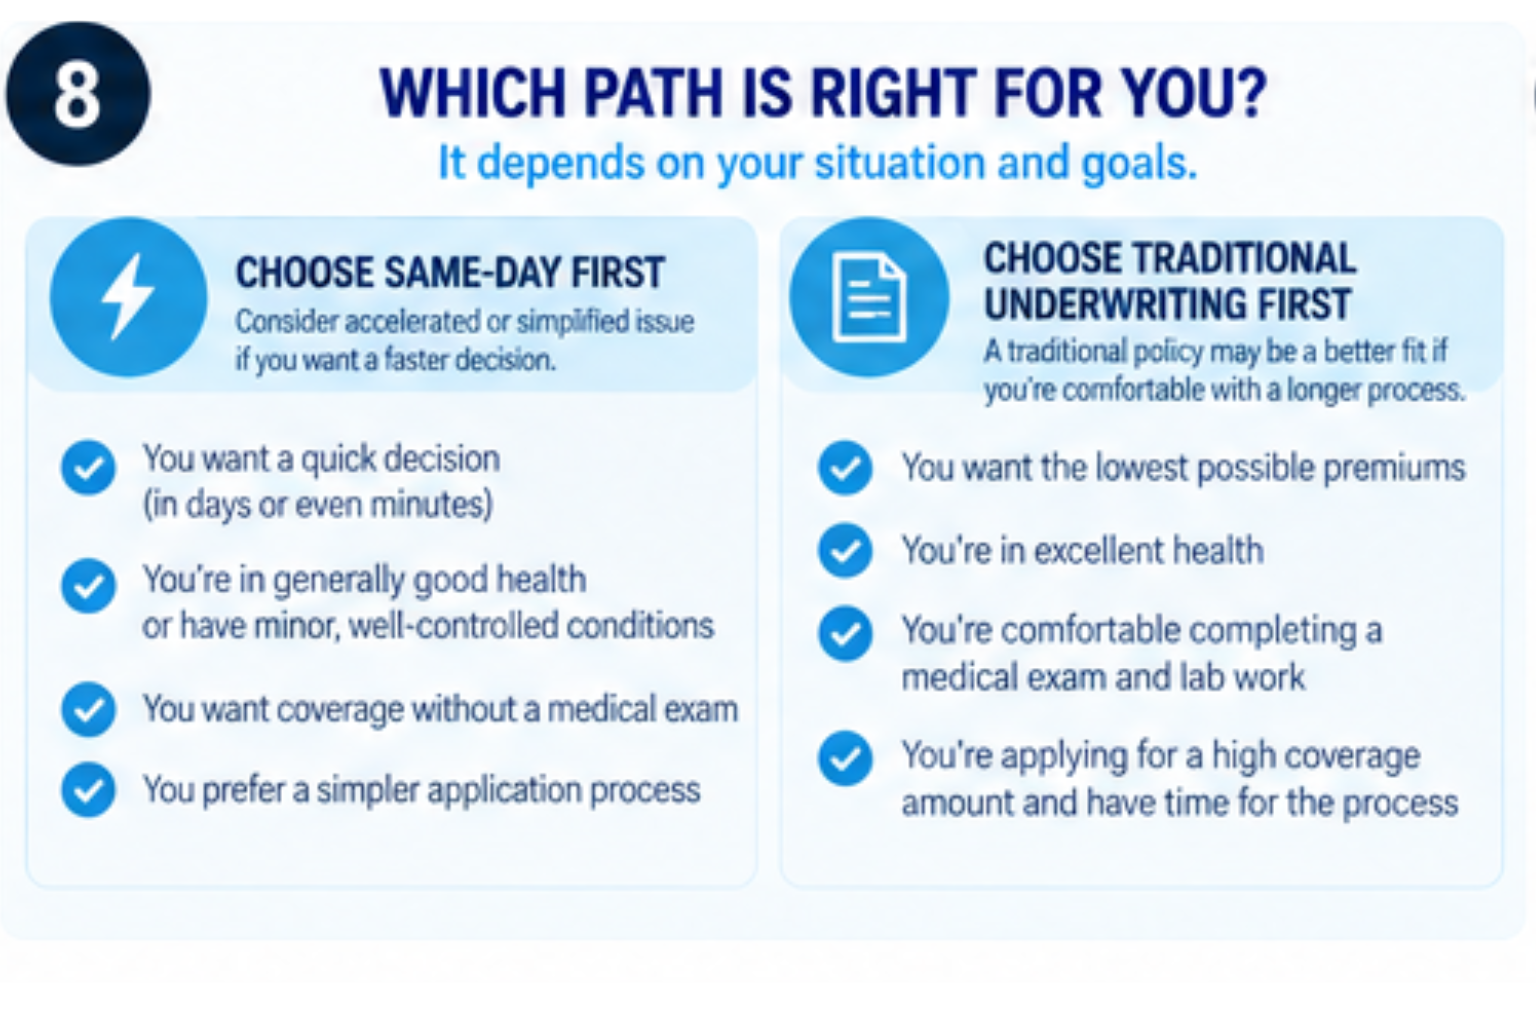
Same-day life insurance is smart when coverage is urgent and your needs match the product’s limits. It is a weaker fit when you want the absolute lowest premium or the highest face amount and have time to wait.
It works especially well for buyers who just had a child, took on a mortgage, changed jobs, or realized they have no coverage in place. It can also help seniors seeking final expense protection or people who want a short application process because of schedule or mobility constraints.
It may be a poor fit if you are young, healthy, and shopping for large term coverage with no deadline. In that case, full underwriting can still offer better pricing. Fast is valuable, but it is not free.
Use this simple filter:
- Choose same-day first: You need coverage now, accept some pricing trade-offs, and want fewer medical hurdles.
- Choose traditional underwriting first: You have time, want maximum value, and are comfortable with an exam and fluid testing.
What should you compare before you accept a same-day policy?
Before accepting a same-day policy, compare the underwriting label, benefit structure, premium, and conversion or renewal rules. Fast approval is only the first checkpoint.
Ask whether the policy is accelerated underwriting, simplified issue, or guaranteed issue. Then ask whether the death benefit is immediate or graded. After that, review premium stability, term length, exclusions, and whether the policy can be converted or kept later without surprises.
If two policies look similar, the better one is often the one with clearer long-term mechanics, not the one approved 20 minutes faster. A same-day decision is useful. A same-day decision on the wrong product is expensive.
| Ready to compare your options? Reach out to Life Insured By Chris to review your fastest insurance options and get matched with coverage that fits your timeline, your budget, and the people you want to protect. → Visit: www.lifeinsuredbychris.com/schedule-a-consultation |