Ethos vs. InstaBrain: No Exam Life Insurance Online
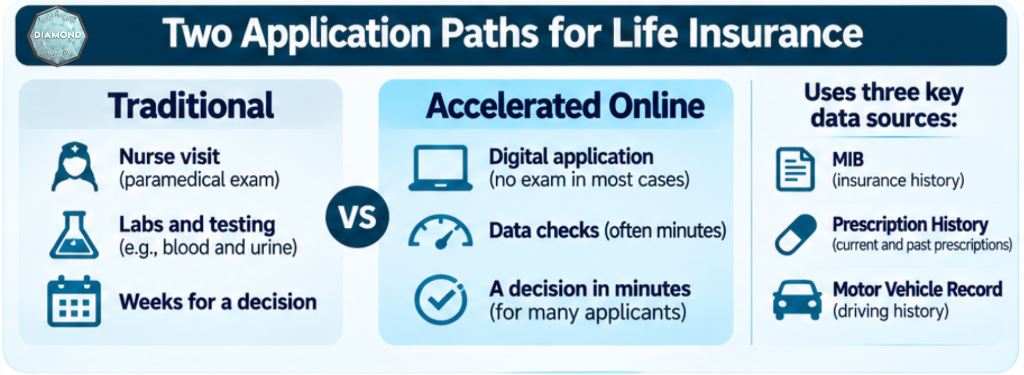
Getting life insurance used to mean weeks of waiting, a nurse visit, blood work, and a stack of paperwork. Today, many healthy applicants can apply from a phone and get a decision in minutes. Life Insured By Chris, an independent brokerage that compares 30+ top-rated carriers, reviews two of the best-known digital options for no exam life insurance online: Ethos and InstaBrain. Here is how each works, where each fits, and when a broader comparison makes more sense.
Ready to apply now? Start your application through Ethos or InstaBrain, or book a free 15-minute review, and we will help you choose.
What is no exam life insurance online?
Skipping the medical exam used to mean paying more for less coverage, a product known as simplified issue life insurance. Today, most fast online applications use electronic data to replace the exam. The insurer checks sources such as the Medical Information Bureau (MIB), prescription history databases, and your motor vehicle record. If those sources support the answers on your application, the carrier may be able to approve you without a nurse visit, needles, or lab work.
For healthy applicants, this can mean speed without the high prices traditionally tied to non-medical products. Approval depends on your age, health history, coverage amount, and the carrier, so not everyone qualifies for an instant decision. For a deeper look at how the process works, see our guide to no exam life insurance quotes and our page on no medical exam life insurance.
Ethos life insurance review
Ethos is a digital life insurance agency, not an insurance company. It sells policies issued by carrier partners, which have included TruStage, Banner Life, Ameritas, and Protective. The application is designed to be fast and mobile-friendly. You answer health and lifestyle questions online, Ethos checks them against third-party data, and many applicants receive a decision in minutes. If you are approved, your policy is delivered electronically, and coverage begins once the first premium is paid.
What Ethos does well
- Product range: Ethos offers term life insurance as well as whole life insurance and final expense options for older applicants.
- High limits for qualified applicants: Ethos advertises term coverage up to $2 million without an exam for those who qualify.
- Multiple carriers: Because Ethos works with several carriers, it can sometimes place applicants that a single insurer would not.
- Smooth mobile experience: The application feels like a modern app, with electronic signatures and digital delivery.
Next step: If speed and a simple mobile application matter most, start your Ethos application here.
InstaBrain life insurance review
InstaBrain is an independent insurance technology company, not a carrier. It builds the instant-decision platform that licensed professionals use to sell life insurance fully online. Policies sold through InstaBrain are issued by licensed carrier partners, and its decision engine underwrites the application as you fill it out, so many applicants get an answer in minutes without an exam. InstaBrain's current product lineup includes term life with living benefits, pure term, final expense, guaranteed issue, and accidental death coverage.
What InstaBrain does well
- A true end-to-end digital process: Quote, application, decision, and signature happen online.
- Fast decisions: Many qualified applicants receive a decision in minutes.
- Variety of fast products: Five product types give you options if one path is not the right fit, including final expense insurance and guaranteed issue plans for applicants with health challenges.
- Collaborative applications: A licensed professional can guide you through the application, or you can complete it on your own.
Next step: If you want a fast, fully digital application with a licensed professional behind it, start your InstaBrain application here.
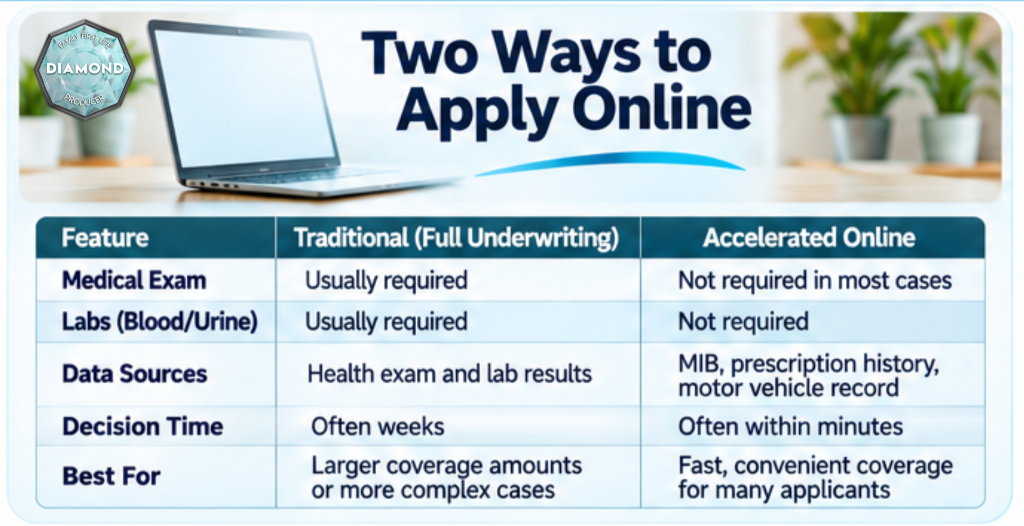
Ethos vs. InstaBrain: how they compare
Both platforms solve the same problem, but in different ways.
| Ethos | InstaBrain | |
|---|---|---|
| What it is | Digital insurance agency working with multiple carriers | Independent insurtech platform used by licensed professionals |
| Who issues the policy? | Carrier partners such as TruStage, Banner Life, Ameritas, and Protective | Fidelity Life Insurance |
| Typical products | Term, whole life, final expense | Term with living benefits, pure term, final expense, guaranteed issue, accidental death |
| Application time | Typically, 10 to 20 minutes | Typically, minutes to complete |
| Exam required? | Not for qualified applicants | Not on its instant products |
| Best for | Healthy applicants who want a choice of carriers and higher limits | Applicants who want a fast, guided, fully digital process and a range of simple products |
For many people, the choice comes down to which questions fit their health history best and which platform gives the better quote that day. If you are unsure, we can run the comparison for you. Schedule a free 15-minute review.
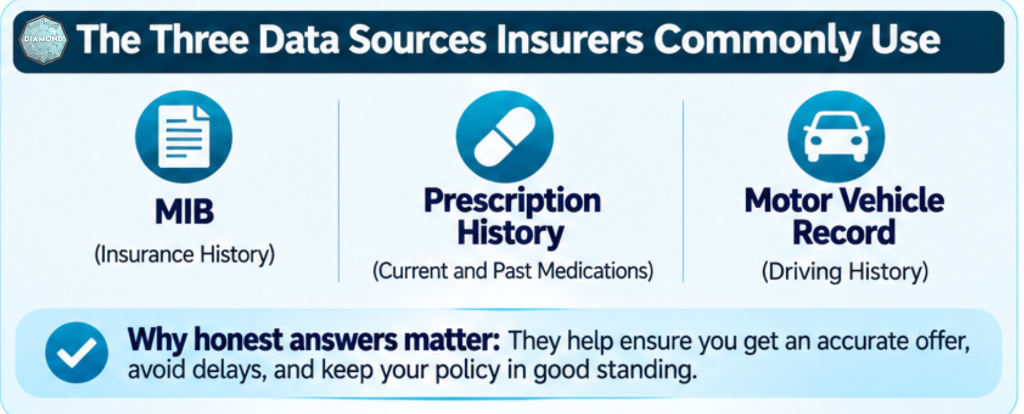
How instant decisions actually work
These platforms decide quickly because they pull data electronically. When you give consent, they typically check:
- The MIB, which tracks prior insurance applications
- Prescription history, which shows medications prescribed over recent years
- Your motor vehicle record, which flags DUIs and serious violations
Combining these sources lets the system build a risk profile in seconds. That is also why honest answers matter. If your application does not match the data, the carrier can slow down your approval, raise your price, or decline you.
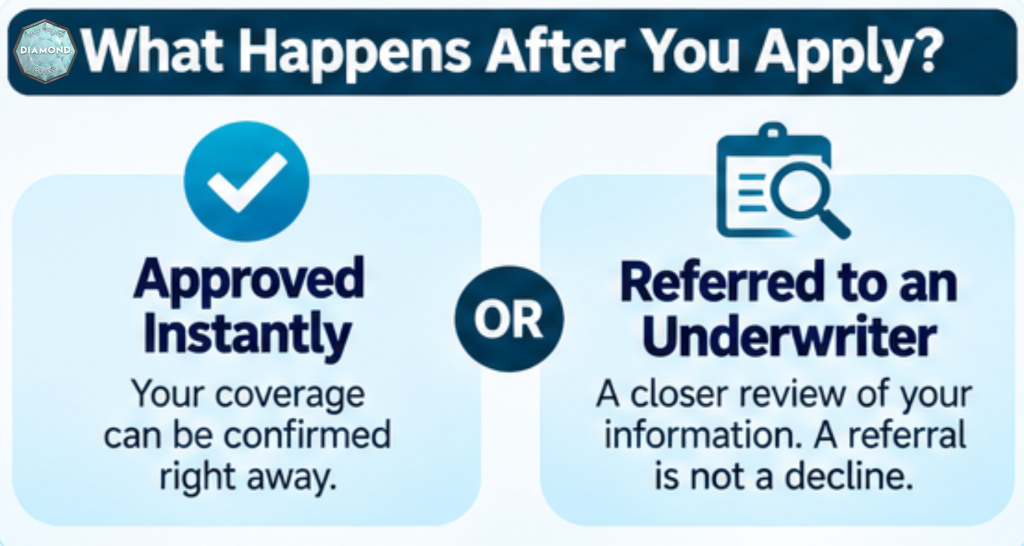
When no exam life insurance online may not be the right fit
Digital platforms work best for applicants with straightforward health histories. If you have had recent cancer treatment, heart disease, or several chronic conditions, the automated system may not approve you instantly. Your application may go to a human underwriter, who might order medical records or ask for an exam.
That is not the end of the road. Different carriers weigh the same health history differently, so a decline from one platform does not mean every carrier will say no. If this describes you, see our guides to life insurance with heart disease, life insurance for cancer survivors, life insurance with diabetes, and life insurance with high blood pressure.
Is no exam life insurance more expensive?
It used to be. Today, for healthy applicants, the price gap between accelerated underwriting and a fully underwritten policy can be small or even nonexistent with some carriers because the carrier saves on exam costs and manual review. That is not guaranteed. Some applicants still get a better rate with a traditional exam, especially if they have a health condition that the exam would show to be well controlled. The best way to know is to compare both paths before you decide. Our guide on how to compare life insurance quotes shows what to check.
Term vs. whole life on digital platforms
Most no-exam applications are for term life insurance, which covers a set period such as 10, 20, or 30 years. It is usually the most affordable way to protect a mortgage or provide for children. Digital platforms also offer simplified whole life and final expense policies, designed for older adults who want to cover funeral costs. Those policies still require no exam, but they carry smaller coverage amounts and a higher cost per $1,000 of coverage. Not sure which fits? Read term vs. whole life insurance or use our guide to how much life insurance you need.
Security and privacy
Applying for life insurance means sharing sensitive personal and health information. Both Ethos and InstaBrain describe security measures on their sites, and insurers are regulated in how they handle your data. Before you apply, review the privacy policy of any platform you use, and make sure you understand what you are consenting to when you authorize the data checks.
How Life Insured By Chris helps
Digital tools are fast, but they are only one slice of the market. Life Insured By Chris is licensed in 20 states and works with families, working professionals, veterans, seniors, and people with health challenges. We compare more than 30 top-rated carriers, so if a digital platform cannot approve you or the price is not right, we have other options to explore. Sometimes, the best coverage for a specific health history sits with a carrier that does not offer an instant decision at all.
Our goal is to help you get the right policy at the right price, not just the fastest one. After your coverage starts, we stay available for beneficiary updates, billing questions, and future coverage reviews.
Frequently asked questions
Is Ethos legitimate?
Ethos is a licensed digital insurance agency. The policies it sells are issued by its carrier partners, so the issuing insurance company backs your coverage.
Is InstaBrain legitimate?
InstaBrain is an insurance technology company that provides the platform. Policies sold through it are issued by licensed, rated carriers.
Can I get a decision the same day?
Many healthy applicants receive a decision within minutes, but timing depends on your health history and the data returned. Some applications are referred for more review. See our guide to same day life insurance for what can speed up or slow down approval.
Do I have to use Ethos or InstaBrain?
No. They are two options among many. We can compare them against traditional and other accelerated options, so you see the full picture.
Final thoughts
Online platforms like Ethos and InstaBrain have made it easier than ever to get covered without an exam. If you are a healthy applicant who wants speed, either one is worth a look. If your health history is more complicated, or you simply want to be sure you are getting the best price, a broader comparison can save you money and frustration.
Choose your next step:
- Apply through Ethos for a fast, mobile-friendly application with multiple carriers
- Apply through InstaBrain for a guided, fully digital application
- Schedule a free 15-minute coverage review to have Life Insured By Chris compare your options for you
Life Insured By Chris is an independent brokerage and may be compensated by carriers or platforms when a policy is issued. This does not increase your premium. Availability, underwriting decisions, coverage limits, and pricing vary by carrier, state, and individual health history. This article is educational and is not medical, legal, or financial advice.